UBS: Samsung SDI (006400.KS) — BESS Order Book and EV Recovery Drive Re-Rating
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
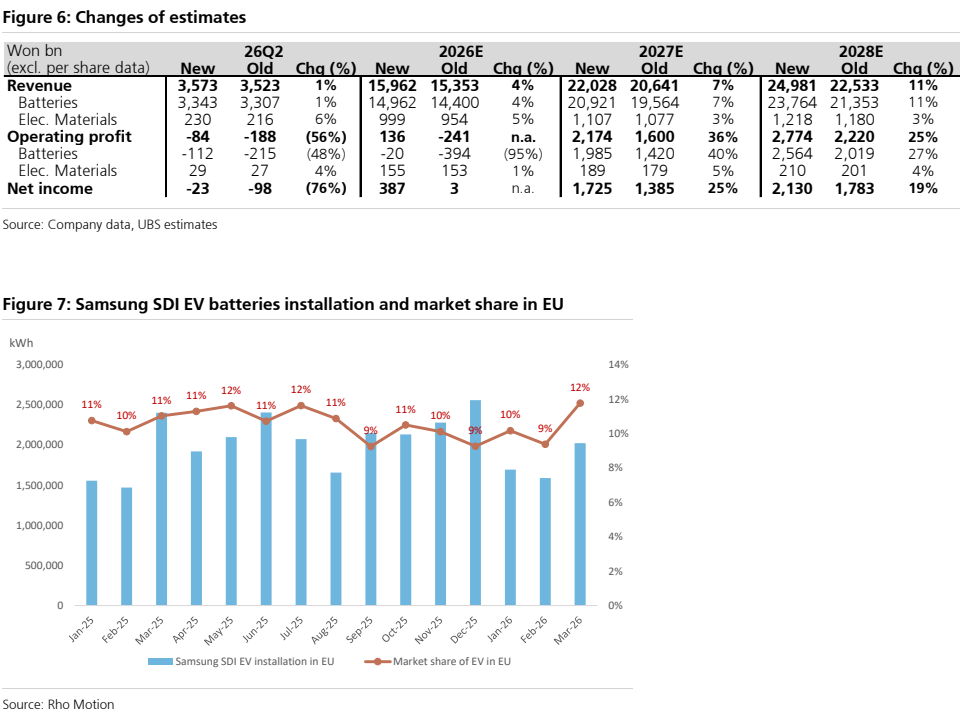
UBS highlights that Samsung SDI is positioned for a potential re-rating, propelled by a robust battery energy storage system order book and an anticipated recovery in electric vehicle battery demand. The report emphasizes that the company's BESS order book has already surpassed its full-year 2025 targets, reflecting strong global market recognition of its energy storage solutions and surging customer demand.
Simultaneously, the electric vehicle battery business is expected to gain meaningful traction starting in the second half of 2026. This projected rebound aligns with a broader recovery in global EV demand, which should subsequently improve the overall profitability of the battery division. The convergence of these two powerful trends within the energy storage and electric mobility segments forms the primary catalyst for the company's improving earnings outlook.
According to UBS, the impressive order growth not only validates the structural strength of the energy storage market but also creates a highly visible revenue pipeline. As EV battery volumes recover and capacity utilization improves, Samsung SDI should witness expanding margins across its core operations. While the report notes that specific numerical targets and detailed timelines remain limited, the fundamental direction is clear. The combination of sustained BESS momentum and improving EV dynamics establishes a compelling case for a market re-rating of the stock.
Key exhibits
Exhibit 1