JPM Flows & Liquidity: A $100bn Rebalancing Flow Boosted April's Equity Rally
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
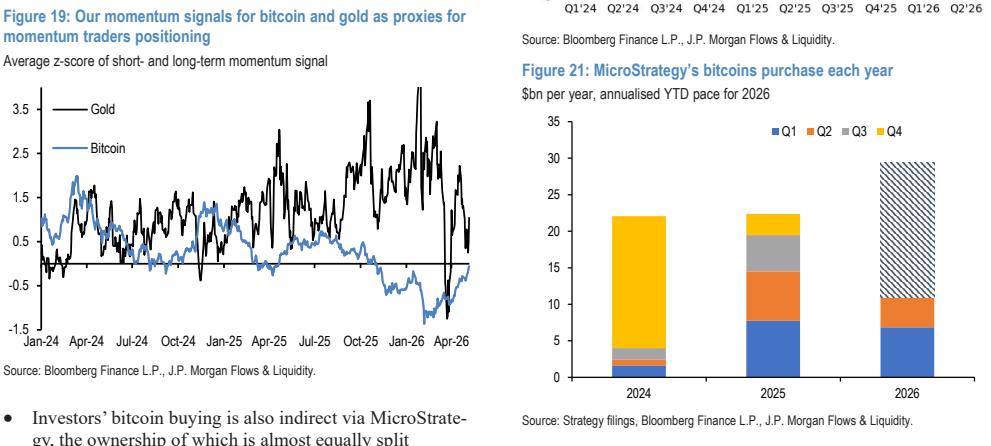
JPMorgan's latest Flows & Liquidity report identifies a massive institutional rebalancing flow of approximately $100 billion as the primary catalyst behind April's equity market rally. This substantial capital movement originated from quarter-end asset allocation adjustments executed by major institutional investors, predominantly pension funds and sovereign wealth funds. The report emphasizes that the sheer magnitude of this rebalancing significantly exceeded historical quarter-end averages, fundamentally driving the sharp upward trajectory observed across the US stock market. While broader macroeconomic anxieties regarding inflation and interest rates persist, this overwhelming technical support from the flows side enabled equities to secure substantial gains. Asset class flow analysis reveals a stark divergence: equity funds captured massive net inflows, while bond funds experienced notable redemptions, highlighting a systematic rotation from fixed income to equities. US equity funds emerged as the principal beneficiaries, supplemented by steady international inflows. Conversely, outflows from bond funds were heavily concentrated in government debt and investment-grade credit. JPMorgan warns that should this rebalancing momentum decelerate in May, equity markets may face heightened correction risks, as the current rally appears driven by structural liquidity shifts rather than fundamental economic improvements.
Key exhibits
Exhibit 1
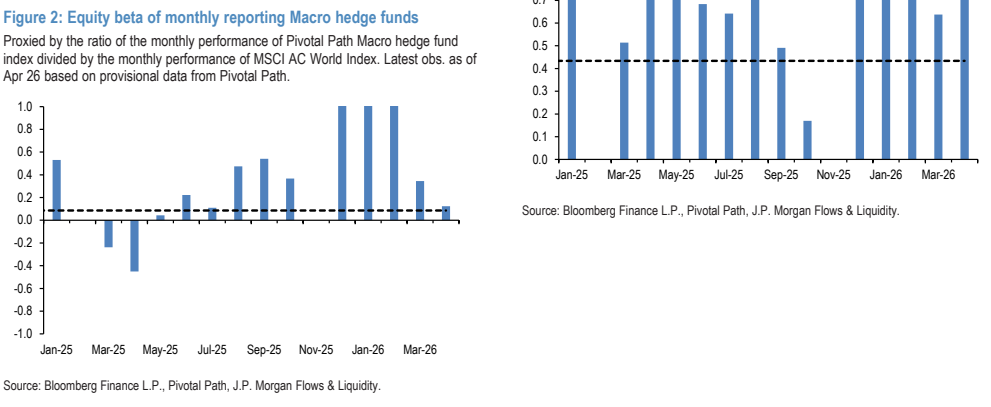
Exhibit 2
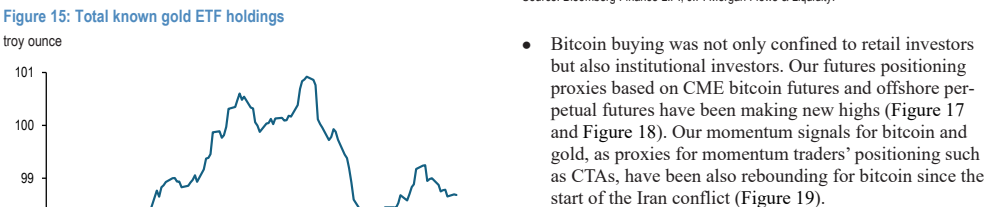
Exhibit 3
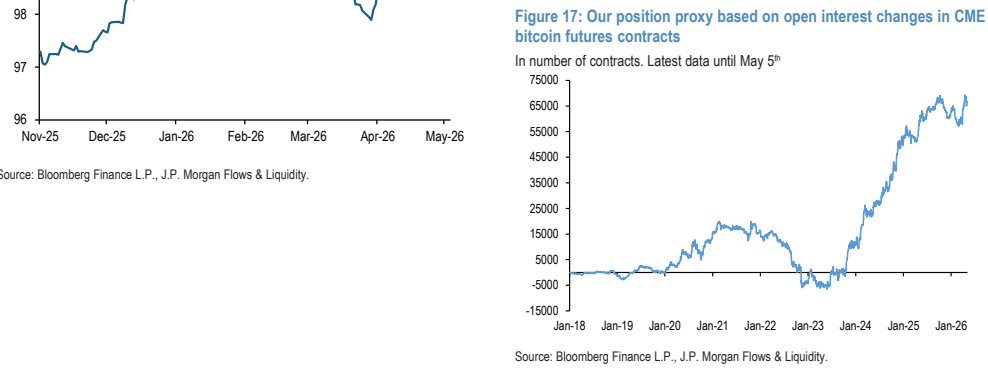
Exhibit 4