Bernstein: Delta Air Lines — 2Q26 Earnings Beat, Target Price Raised to $106
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Diversified revenue streams, accounting for 61% of total revenue (up 2 percentage points year-over-year), continue to underpin growth. Premium product revenue grew 17%, MRO surged 32%, and cargo jumped 39%. Domestic corporate sales remained robust, with core/coastal hub growth exceeding 20% and cities like Los Angeles and Boston reaching 30%.
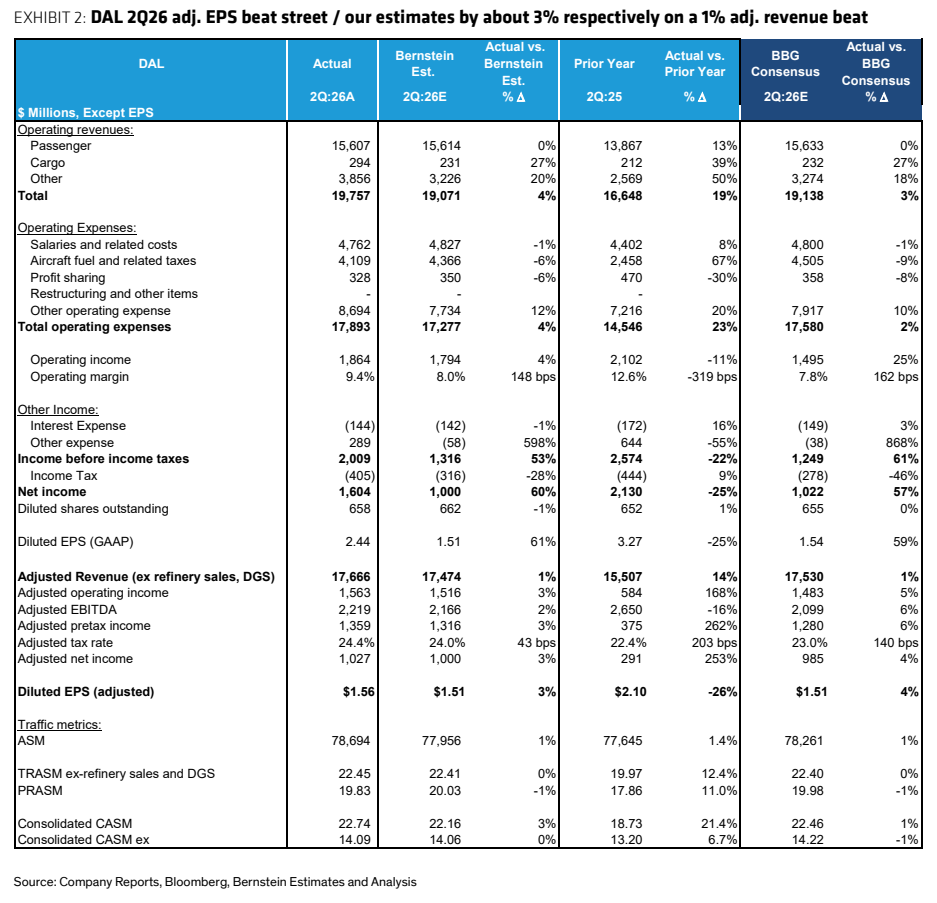
Bernstein raised its FY26 adjusted EPS estimate by 18% to $6.92 and subsequent years by approximately 9%, driven by growing confidence in a structural pricing shift. Industry capacity discipline persists, with 3Q ASM growth of around 1% and 4Q at 2–3%. Low-cost carrier constraints further support yield sustainability.
Outlook
3Q TRASM growth is expected to accelerate from 2Q's approximately 12.4%. Fourth-quarter profitability signals indicate fare declines will be smaller than fuel price decreases, enabling Delta to retain partial benefits. Bernstein remains modestly cautious on 4Q, with its EPS estimate approximately 3% below the implied $2.54.
Recommended Securities
Delta Air Lines (DAL): Outperform; target price raised to $106 (from $93), based on an NTM+1 EBITDAR multiple of 6.8x (previously 6.5x).
Key exhibits
Exhibit 1
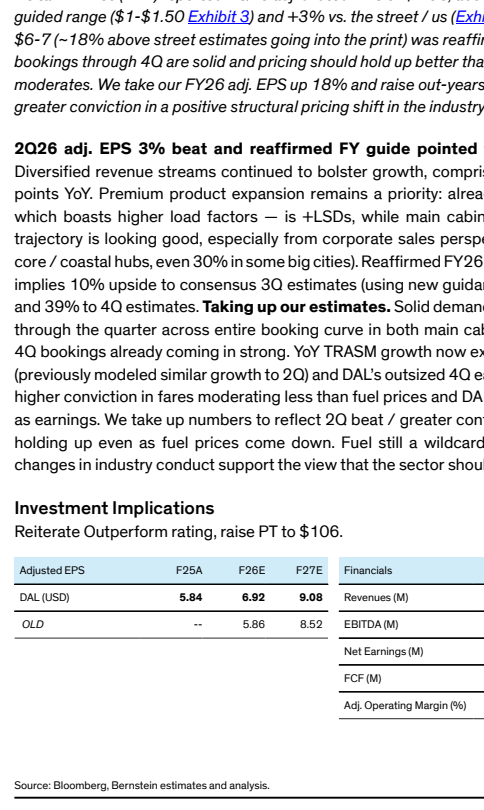
Exhibit 2
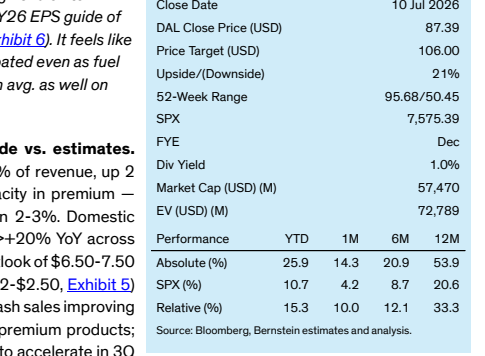
Exhibit 3
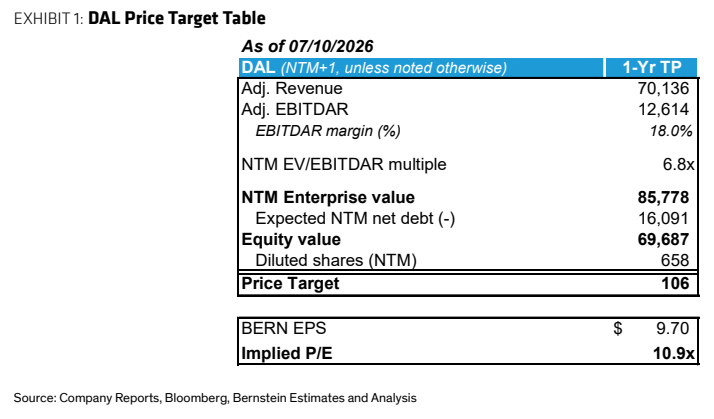
Exhibit 4
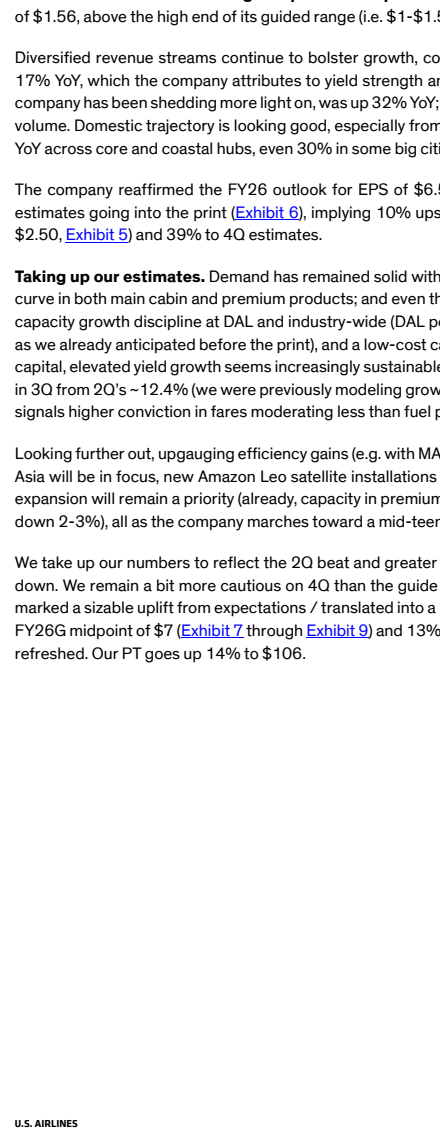
Exhibit 5
Exhibit 6
Exhibit 7
Exhibit 8