Yum China (9987.HK) Q3 Preview: Moderate Same-Store Sales Growth, but Margins Remain Supported
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Deutsche Bank's preview of Yum China's (9987.HK) third-quarter 2026 results projects high-single-digit YoY revenue growth in constant currency, with net profit up low-single-digits to more than US$300 million. Adverse weather and a soft macro environment may leave company-level same-store sales slightly negative YoY, but restaurant margin should rise about 0.3 percentage points, helped by licensing-fee savings from the Pizza Hut brand ownership consolidation and operational efficiencies that offset labor-cost pressures. Operating margin is expected up 0.1pp, while net margin dips 0.1pp on higher G&A costs.
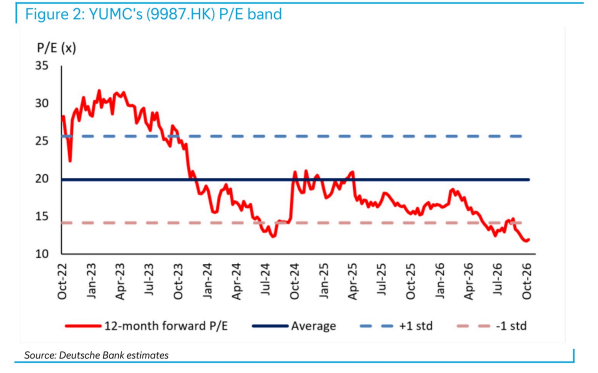
Store expansion continues at KPRO, which reached 600 outlets by September, and Pizza Hut Burger Bar, which passed 300 outlets by August. The analyst maintains a Buy rating and a target price of HK$487.0, arguing the market has already priced in weak third-quarter same-store sales. Key watch items are the boost to fourth-quarter same-store sales from expanded autumn holiday policies and refinancing plans once the Pizza Hut transaction bridge loan matures.
Key exhibits
Exhibit 1
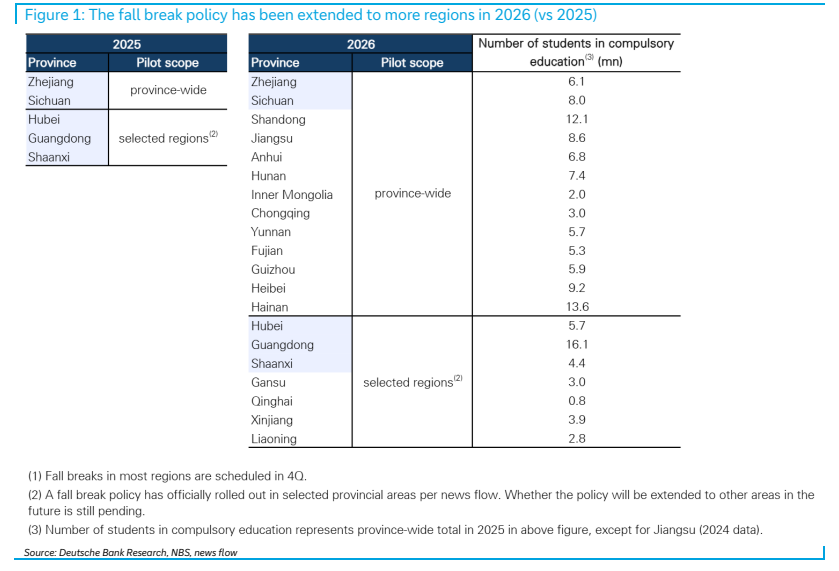
Exhibit 2