HSBC Wuxi Biologics (2269.HK) Buy: Lifting Three-Year Growth Outlook, Driven by Accelerating CMO and IP-Based Revenue
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
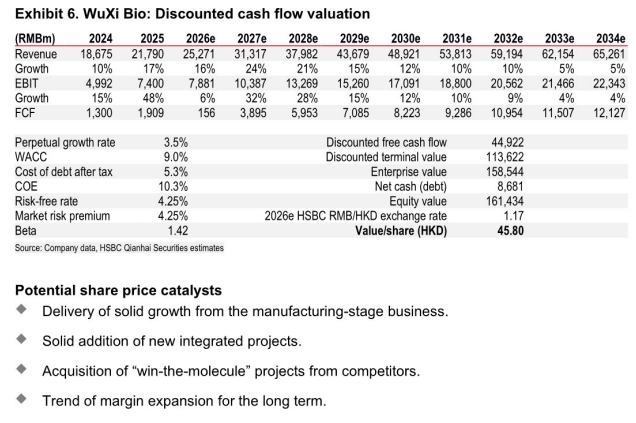
HSBC upgraded Wuxi Biologics to a Buy rating, lifting the target price and the three-year growth outlook based on accelerating contract manufacturing organization and intellectual property licensing revenue. The firm anticipates that a rapidly expanding CMO project pipeline and significant IP licensing contributions will serve as primary growth catalysts through 2026. Management raised its revenue guidance, reflecting strong confidence in order momentum and capacity utilization. The CMO business is experiencing rapid growth, with an increasing number of new projects expected to drive substantial revenue increases in 2025 and 2026. Simultaneously, IP licensing has emerged as a meaningful revenue driver, supported by multiple new agreements expected to generate material contributions. Capacity utilization rates are improving steadily, which, combined with ongoing cost optimization initiatives, should expand gross margins over the forecast period. While geopolitical headwinds and customer concentration remain identifiable risks, the company has successfully diversified its client base, significantly reducing reliance on its top five customers. This strategic diversification lowers the overall risk profile. Sustained research and development investments further reinforce the long-term technological advantage of the firm. HSBC views the combination of robust top-line acceleration, margin expansion, and a de-risked customer portfolio as compelling indicators of sustained fundamental outperformance.
Key exhibits
Exhibit 1
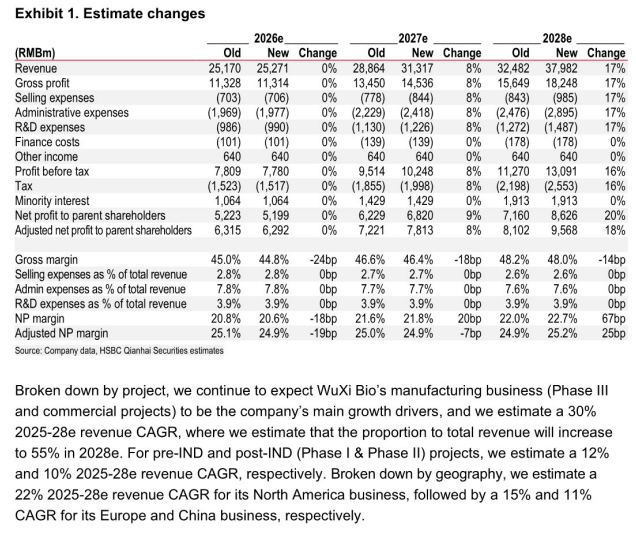
Exhibit 2
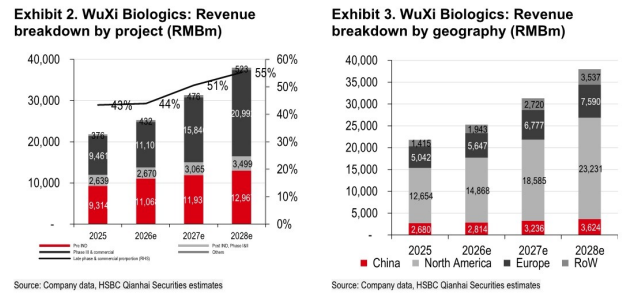
Exhibit 3
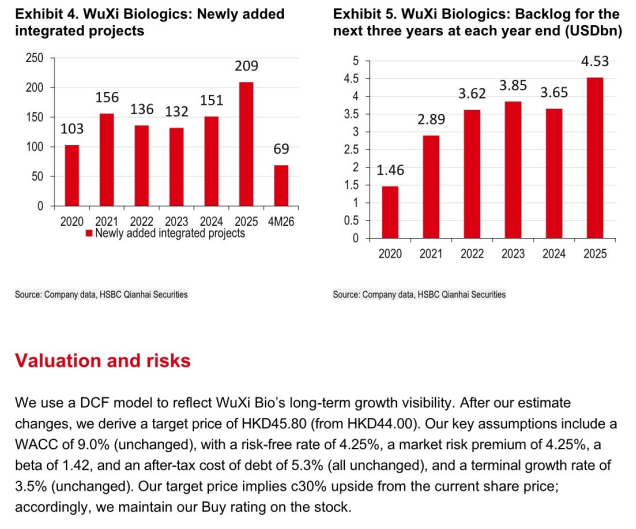
Exhibit 4