Goldman Sachs on Australian Healthcare: Limited Credit Risk, but Rising Yields May Constrain SHL Growth; Downgraded to Neutral
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
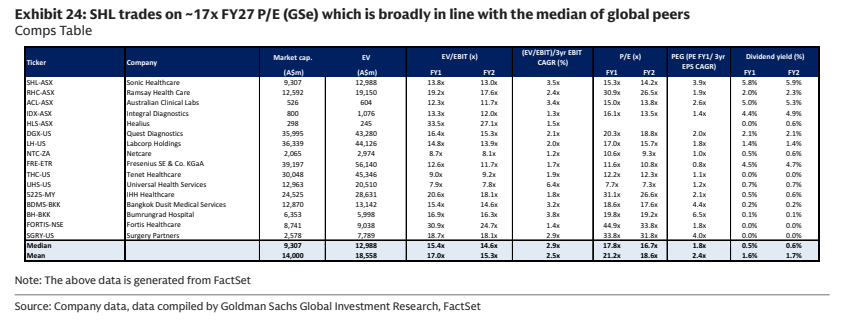
Goldman Sachs' report on Australian healthcare argues that while sector-wide credit risk remains contained, rising bond yields are becoming a constraint on Sonic Healthcare (SHL). The bank downgraded SHL from Buy to Neutral and cut its target price from A$23.70 to A$19.20, reflecting higher debt costs and the risk of deferred M&A. EPS forecasts for FY28 and FY29 were reduced by 4% and 7% respectively, with roughly 48% of SHL's interest-bearing debt floating-rate in FY26 and exposure to potential healthcare spending cuts in Germany and the US. The A$19.20 target blends a DCF value of A$19.60 with an EV/EBIT-based A$18.80; SHL trades at about 17x FY27 estimated P/E, broadly in line with the global peer median. By contrast, Ramsay Health Care (RHC) and CSL retain Buy ratings, as prudent hedging policies limit sensitivity to rate volatility. Integral Diagnostics (IDX) stays Neutral given higher leverage and unhedged debt exposure, with FY27 debt costs expected to rise around 80 basis points.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
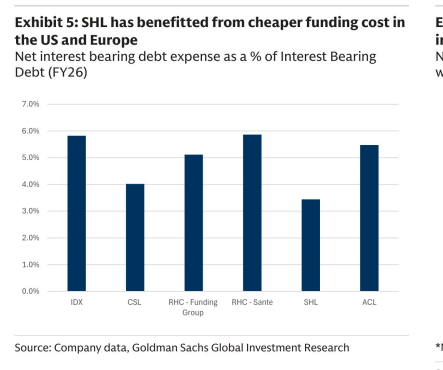
Exhibit 4

Exhibit 5
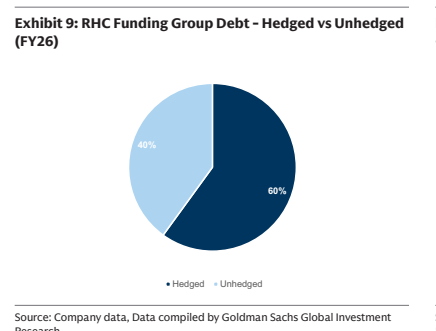
Exhibit 6
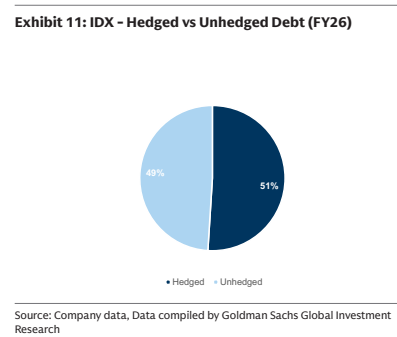
Exhibit 7
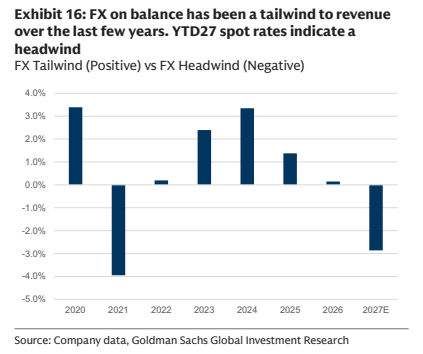
Exhibit 8
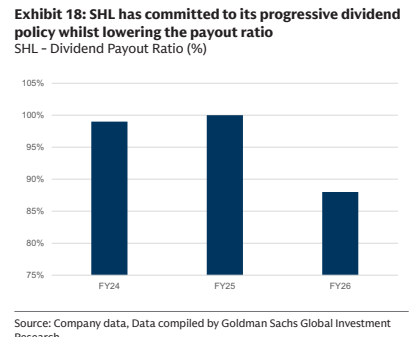
Exhibit 9
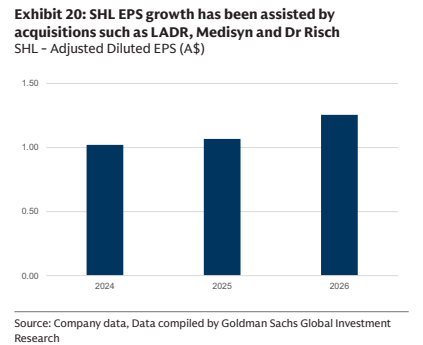
Exhibit 10
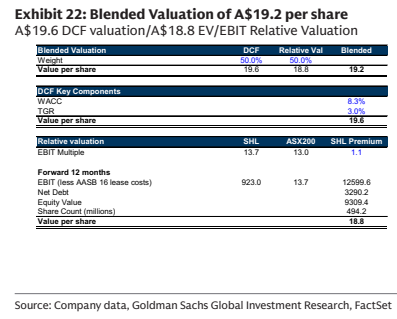
Exhibit 11