Guotai Haitong Securities: Jinpan Technology (688676) — Q3 Orders Accelerate as Gross Margin Keeps Improving
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Guotai Haitong Securities highlights a strong Q3 2026 for Jinpan Technology (688676): revenue growth accelerated markedly, with overseas business the clear driver, while gross margin continued to improve despite rising raw material costs. Margin gains reflect the company's digital transformation and an optimizing order mix. Newly signed orders grew rapidly, with Q3 growth especially pronounced, and data center orders expanded explosively; overseas and AIDC businesses now anchor the order backlog. The period expense ratio rose on foreign-exchange swings and higher interest expense.
The investment logic runs from a deepening globalization strategy and released AI demand, to an improved order structure and surging data center orders, to revenue acceleration and margin improvement, and ultimately to profit growth. Analysts expect revenue and net profit attributable to shareholders to keep growing through 2026–2028, underpinned by digital transformation and customer-structure optimization that supports a solid medium-term foundation.
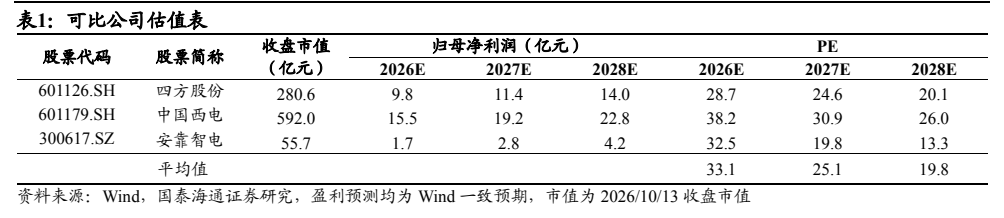
Guotai Haitong maintains an overweight rating with a target price of RMB 72.58; a comparable-company valuation table accompanies the note.
Key exhibits
Exhibit 1