Johnson Electric (00179.HK): FX Losses and Cost Pressures Drag on Near-Term Profit; New Business Direction Unchanged
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Abstract
Johnson Electric Holdings (00179.HK) expects profit attributable to shareholders of US$50-58 million for the first half of fiscal 2027, a year-on-year decline of 56-62%, driven mainly by foreign-exchange losses and cost pressures, while revenue should remain broadly flat against the same period last year. Although near-term earnings are under strain, the company continues to build out new businesses such as liquid-cooling pumps, solid-oxide fuel cells (SOFC) and robotics, and CICC believes the medium- to long-term growth thesis is intact. The interim results came in below expectations, with currency losses accounting for most of the shortfall; even excluding FX, profit still fell on rising costs, including pricing pressure and higher raw-material and labor expenses. Revenue nonetheless outperformed the global auto industry, with ramping liquid-cooling and SOFC products contributing. CICC cut its FY27/FY28 earnings forecasts and lowered its target price by 33.6% to HK$20.25, maintaining an Outperform rating. Auto-sector conditions should improve in the second half versus the first, with profit recovery hinging on price adjustments and cost pass-through. CICC remains positive on liquid cooling, SOFC and robotics as a second growth curve.
Key exhibits
Exhibit 1
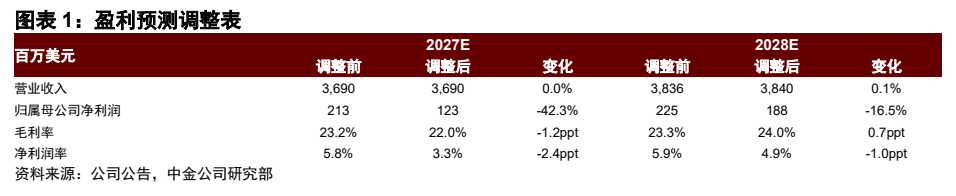
Exhibit 2
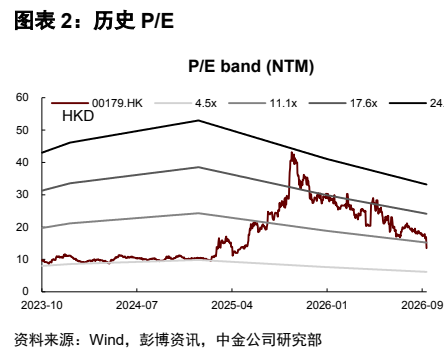
Exhibit 3
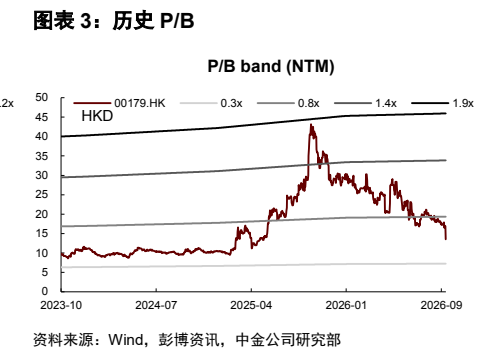
Exhibit 4
