UBS: Lumentum Holdings (LITE.US) Resetting Numbers Following a Raise and Channel Checks
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Following Lumentum's upward revision of its financial guidance and comprehensive channel checks, UBS updated its financial models for the company. The firm maintains a Buy rating and raises its target price from $85 to $95. Lumentum is benefiting from surging artificial intelligence demand within data centers, particularly the ramp of 800G and 1.6T optical transceivers, alongside a recovery in the broader telecommunications market.
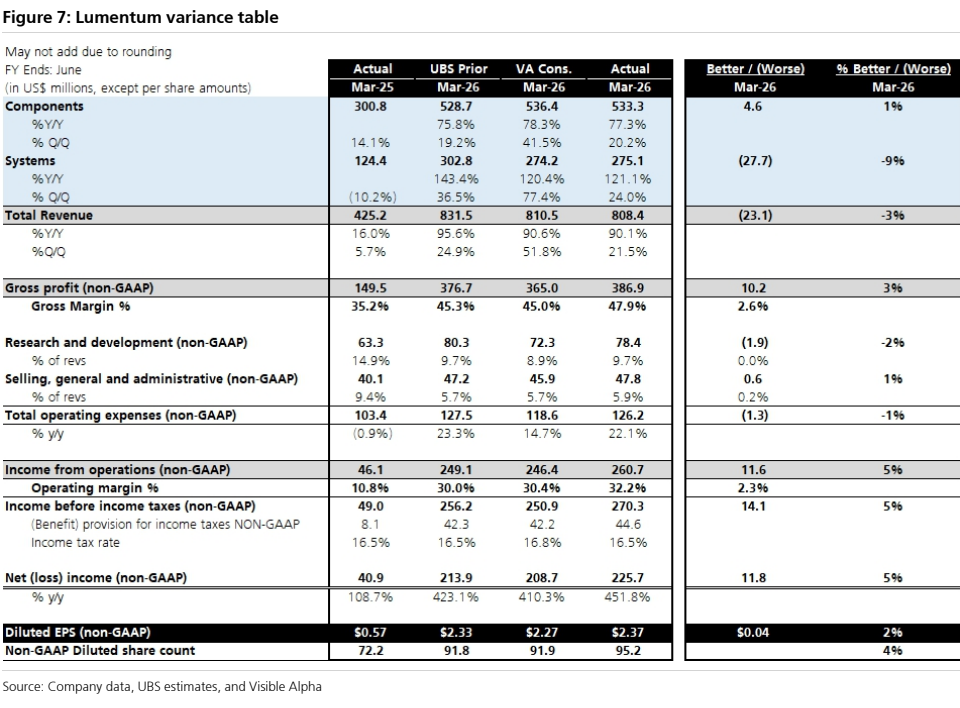
Lumentum raised its fiscal 2026 first quarter revenue guidance to a range of $350 million to $380 million, well above UBS's prior estimate of $320 million. Channel checks indicate that customer inventories have normalized and order visibility is improving. The company expects data center revenue to grow more than 50% year-over-year, while telecommunications revenue is projected to increase by 20% to 30%, driven by coherent pluggable product demand. Gross margins are forecasted to improve to a range of 45% to 47% due to favorable product mix shifts.
Consequently, UBS increased its fiscal 2026 EPS estimate to $4.50, up from $4.00. Management also indicated that second quarter revenue will fall between $360 million and $390 million. UBS views Lumentum's current valuation as attractive, trading at roughly 18 times forward earnings. The firm notes that Lumentum holds a leading position in high-speed optical modules. Key downside risks include a slower telecommunications recovery, intensifying competition, and potential supply chain disruptions.
Key exhibits
Exhibit 1
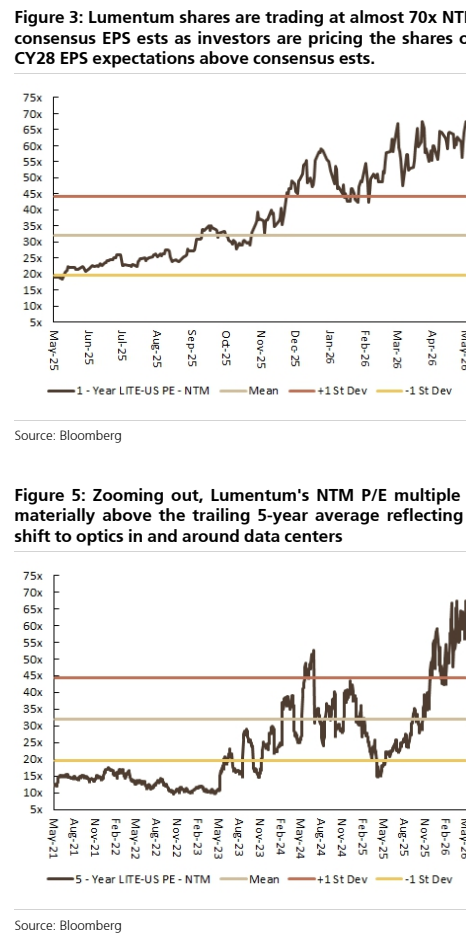
Exhibit 2
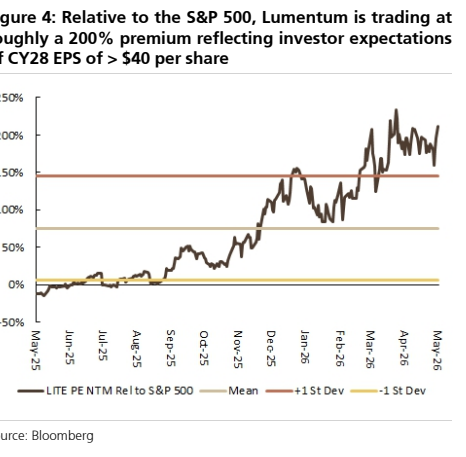
Exhibit 3
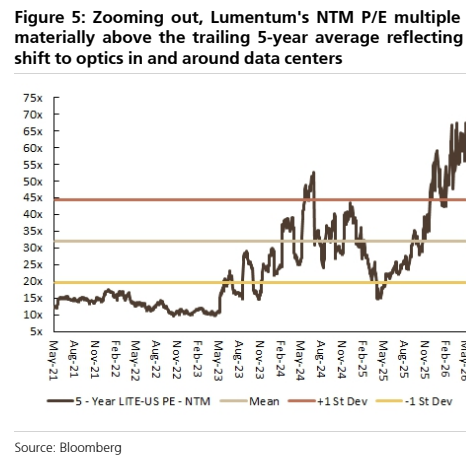
Exhibit 4
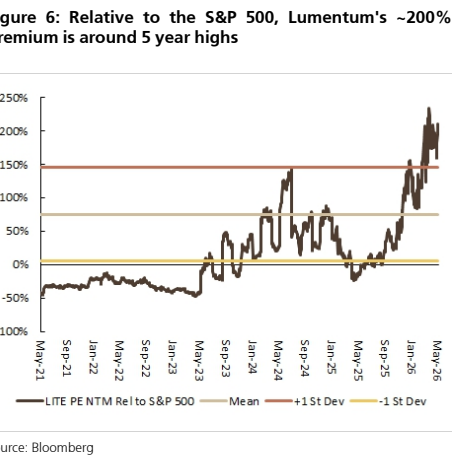
Exhibit 5