J.P. Morgan Electronic Components: SEMCO 1Q FY2026 Results and Implications for Japan's Sector
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
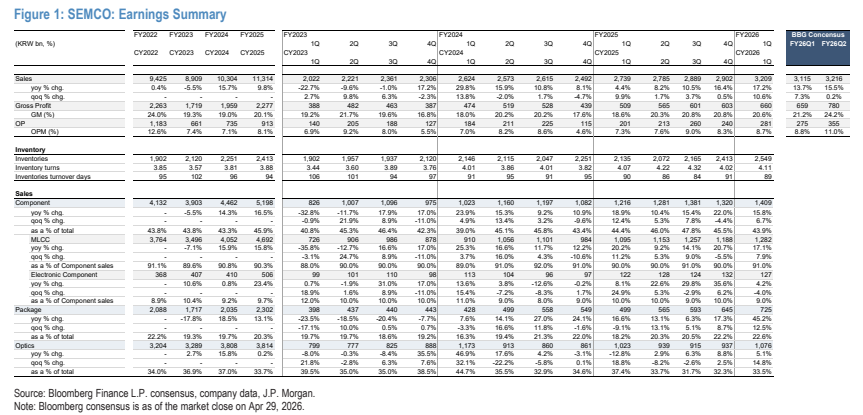
J.P. Morgan highlights the strong first-quarter fiscal 2026 results from Samsung Electro-Mechanics (SEMCO) and its positive read-through for the Japanese electronic components sector. SEMCO reported revenue of 2.5 trillion Korean won, representing 12% year-over-year growth and exceeding market expectations. Operating profit surged 25% to 350 billion won, driven by robust MLCC shipments and an improved product mix.
This outperformance signals broader industry strength. SEMCO's MLCC shipments grew 8% sequentially, fueled by smartphone and PC restocking alongside surging AI server demand. High-capacity MLCCs now account for 35% of the product mix, up from 30% last year.
J.P. Morgan anticipates that leading Japanese suppliers, including Murata, TDK, and Taiyo Yuden, will directly benefit from these identical demand tailwinds. AI server MLCC demand alone is projected to grow 50% year-over-year in 2026. Consequently, the firm expects Murata to post 10% revenue growth with a 22% operating margin, TDK to grow 8% driven by inductors, and Taiyo Yuden to achieve 12% growth with MLCC capacity utilization reaching 90%.
Maintaining an Overweight rating on the Japanese electronic components sector, J.P. Morgan cites attractive valuations and powerful secular growth drivers. Key downside risks include slower smartphone demand recovery, intensified MLCC price competition, and potential yen appreciation eroding export competitiveness.
Key exhibits
Exhibit 1