Goldman Sachs Asia Economics Analyst: How Much More Can China's Exports Grow?
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
This report sizes China's remaining export headroom, concluding exports can stay strong for at least the next few years, while longer-run share gains require faster growth in importing economies. China's share of global nominal goods exports rose from 4% in 2000 to nearly 15% in 2025, surpassing Germany's 1970s peak of 13% and Japan's 1980s peak of 10%; the 2025 surplus is roughly 1% of global GDP. Profitability checks suggest 'China Shock 2.0' is supply-driven: auto export values nearly doubled over 2021–25 while margins fell from 6.4% to 4.8%. Economies running deficits with China above 3% of GDP increased from 24 in 2005 to 82 in 2025 (67 low-income), together absorbing 44% of China's exports; substitution cushions the strain—each 1pp-of-GDP rise in China deficits cut non-China deficits by 0.7pp on average in 2021–25. Benchmarking 98 economies with at least US$10bn of 2024 imports, China's share of global non-mineral imports could rise from 17.6% to 27.6% (23.0% if US/Canada/Mexico shares are frozen; about 19.2% freezing all developed-market shares). Each 1pp share gain equals 5.5% export growth; adding 2.5% trend global trade growth, even the most conservative scenario supports roughly 8% annual real export growth near term, with low-income countries' balance-of-payments constraints the key vulnerability.
Key exhibits
Exhibit 1
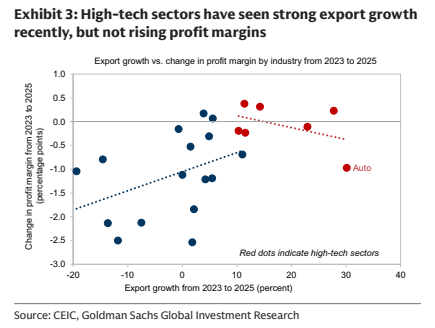
Exhibit 2
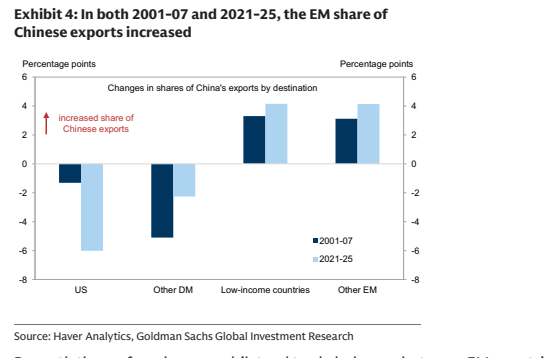
Exhibit 3

Exhibit 4
