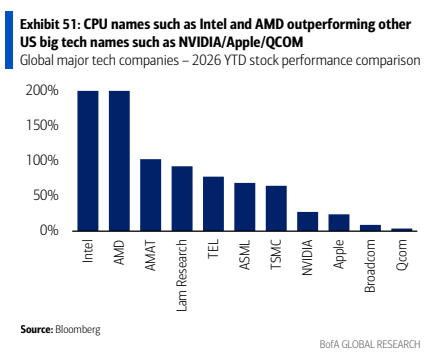
BofA Global Memory Technology Weekly: Samsung Q3 Results, Global Forecast Update and De-Spec Implications
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
BofA's global memory technology weekly reaffirms the durability of the memory supercycle after Samsung Electronics' preliminary third-quarter operating profit of KRW 107tn came in line with expectations, with DRAM and NAND contributing more than 100% of operating profit. Memory ASPs rose over 20% quarter-on-quarter while operating margins held around 70%. Rather than a demand cut, the de-specification trend (8-hi HBM4) is framed as a growth catalyst that supports GPU shipments and drives SOCAMM and eSSD demand. BofA raised its NAND ASP assumptions, lifting NAND revenue forecasts by 3-49%, and now expects the global memory market to grow from roughly USD 0.9tn in 2026 to USD 2.1tn in 2030. Memory capex is set to climb to KRW 67tn, 85tn and 92tn in 2026, 2027 and 2028 respectively, while annual free cash flow should exceed KRW 300tn in 2027-28. The BofA Memory Indicator stood at 179 in August, still at supercycle levels. Fourth-quarter operating profit is expected to top the third quarter, with 2027 above 2026. Samsung Electronics common stock: target price KRW 500,000, rating C-1-7; preferred stock: target price KRW 340,000, rating C-1-7.
Key exhibits
Exhibit 1
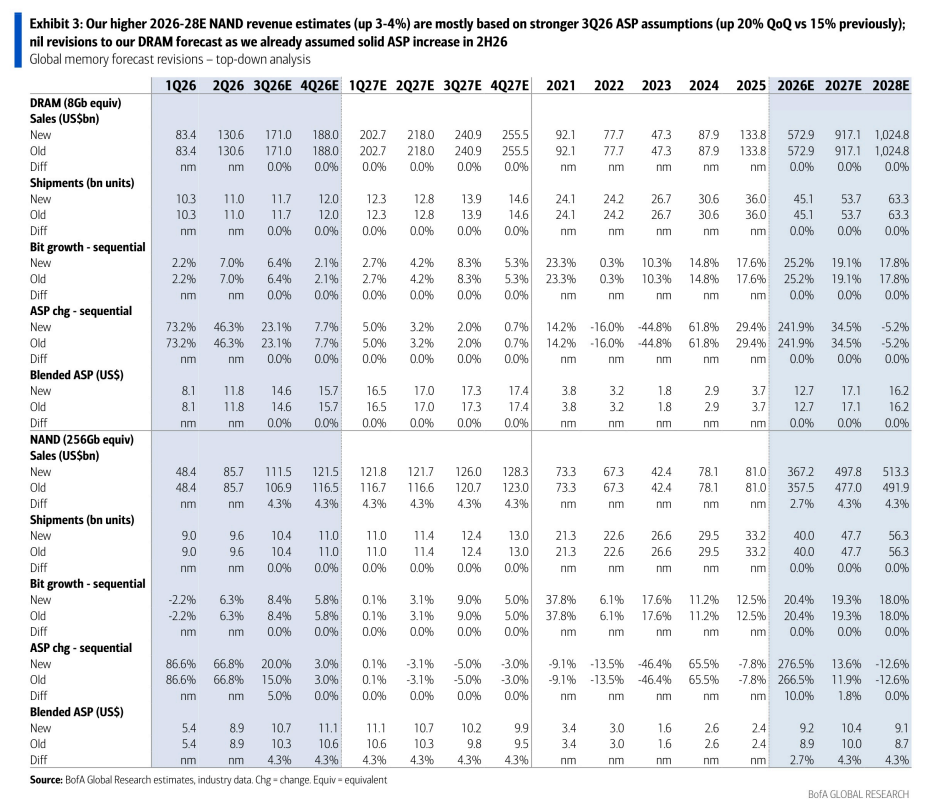
Exhibit 2
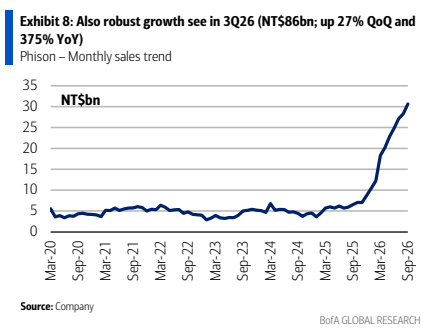
Exhibit 3
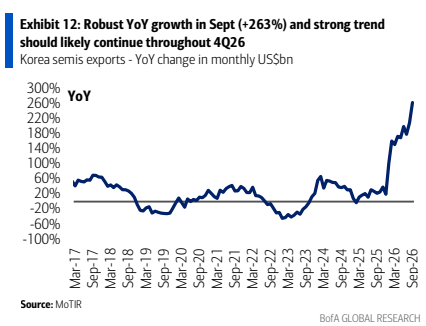
Exhibit 4
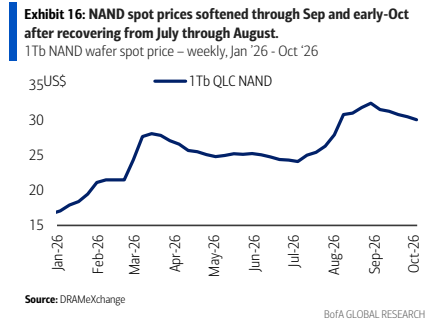
Exhibit 5
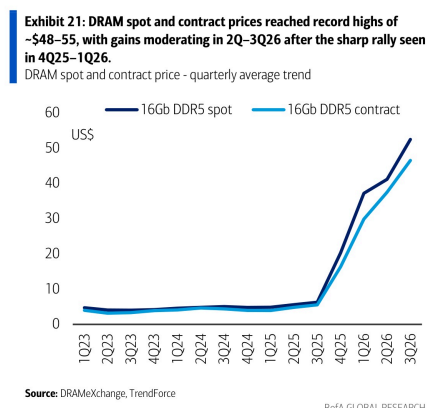
Exhibit 6
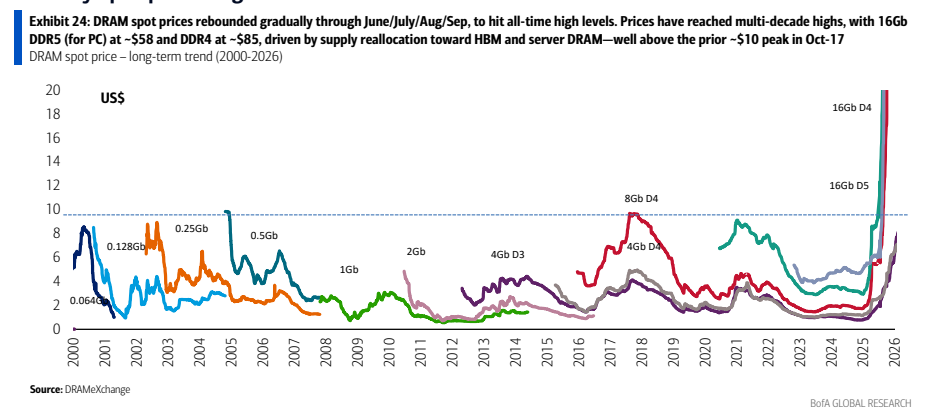
Exhibit 7
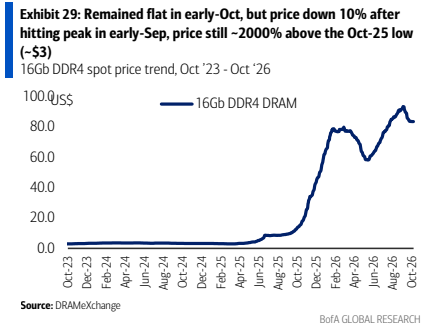
Exhibit 8
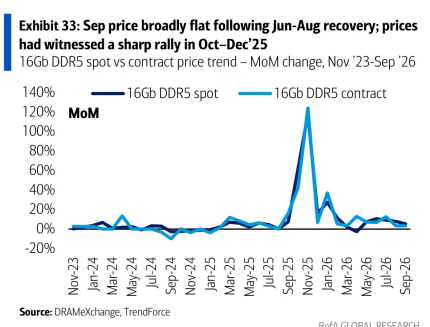
Exhibit 9
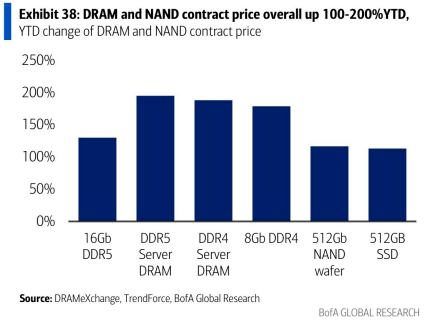
Exhibit 10
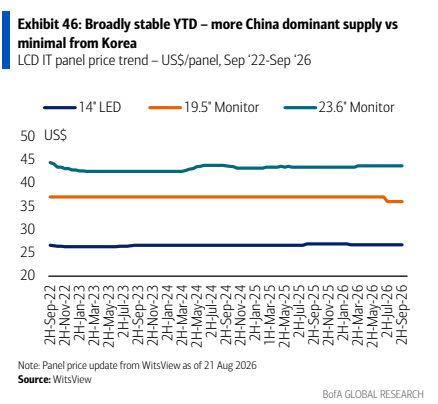
Exhibit 11