Citi | Laopu Gold (6181.HK): Earnings Estimates Cut as Q3 2026 Sales Recovery Undershoots
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Citi expects Laopu Gold's (6181.HK) third-quarter 2026 sales to improve sequentially while net profit weakens, as volatile gold prices weigh on consumer sentiment and the company's pricing strategy cuts both ways. Citi models Q3 revenue of RMB 3.6 billion and net profit of RMB 589 million, with gross margin contracting roughly 5 percentage points quarter-on-quarter to 41-42%. Management adopted more attractive discounted pricing in Q3 to broaden the customer base, but consumers who notice discounts may wait for even lower prices - a double-edged risk.
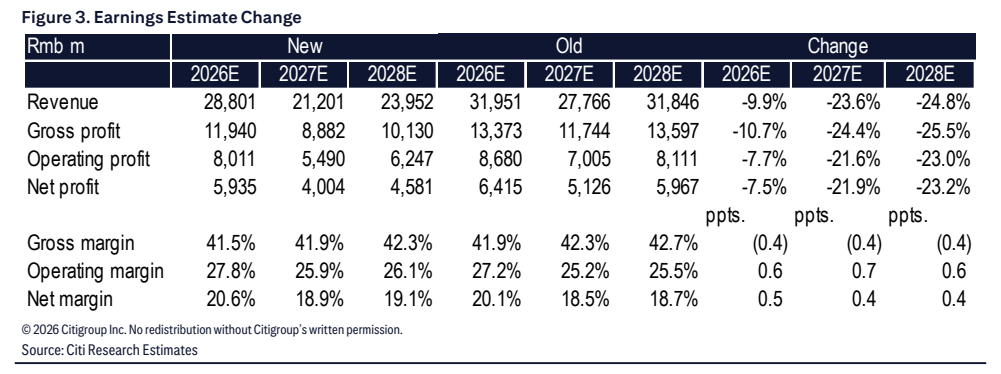
Improvements in operating leverage are insufficient to offset the gross margin decline, driving sequential net profit erosion. Citi cuts its 2026-2028 net profit forecasts by 7%, 22% and 23% respectively and lowers the target price from HKD 507.0 to HKD 400.0, while maintaining a Buy rating on the view that the market underestimates the brand's customer loyalty and competitive advantages. For Q4, it expects sales at 1.5x and net profit at 1.8x the Q3 level. Long term, Citi remains positive on brand loyalty and recovery potential, though the near term stays hostage to gold price volatility.
Key exhibits
Exhibit 1
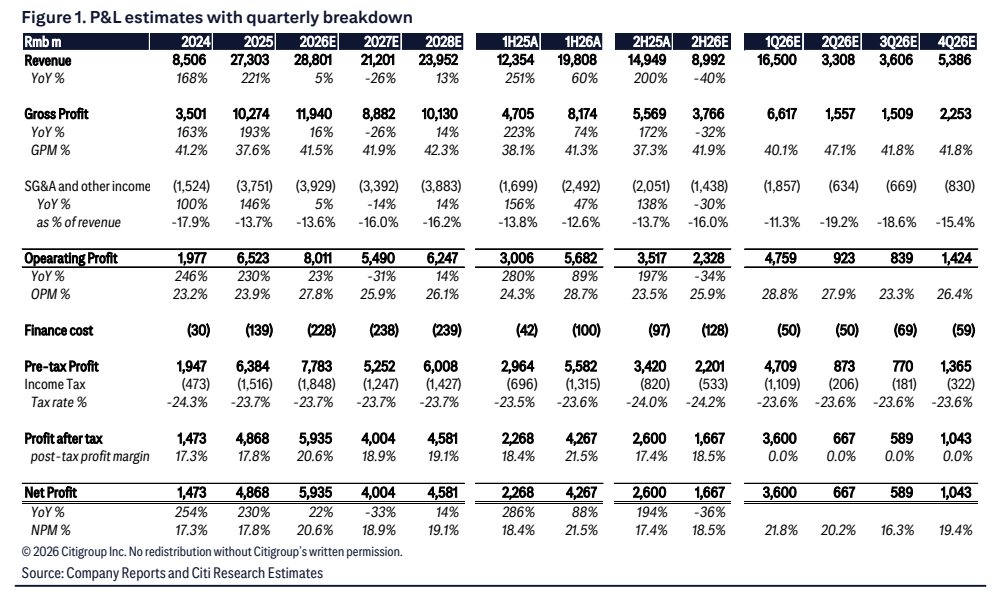
Exhibit 2