UBS: US Power - DCF Valuations for IPPs Support Bullish View
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS maintains a bullish outlook on US independent power producers, asserting that discounted cash flow valuations underscore significant upside potential. The report argues that current market pricing fails to fully capture the long-term cash flow capabilities of these companies, particularly the intrinsic value of their renewable energy assets.
UBS anticipates that structural growth in electricity demand, fueled by data center expansion and broader electrification trends, will sustain upward pressure on power prices. Additionally, tightening capacity markets are expected to provide stable revenue streams through capacity payments. Supportive policies, including the Inflation Reduction Act, further reduce project costs for renewable developments.
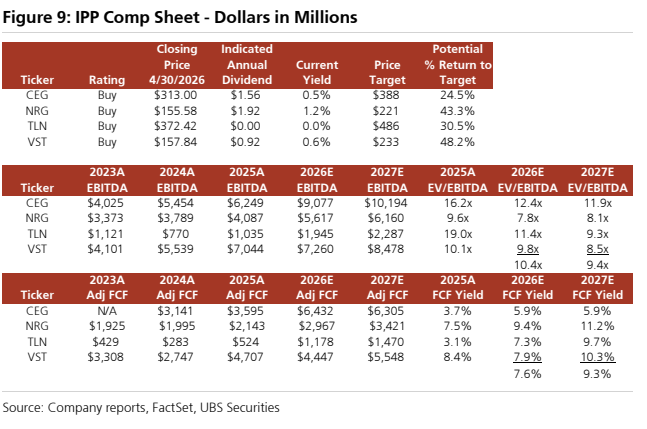
According to UBS DCF models, IPPs offer approximately 30% average upside from current trading levels. Renewable energy assets contribute the majority of this modeled value, a factor the market has yet to completely recognize. While leverage remains elevated for some entities, improving cash flows are expected to mitigate balance sheet risks.
Among UBS coverage, Vistra and NRG Energy present the most compelling valuations. Vistra carries a Buy rating with 35% projected upside, while NRG Energy also rates as a Buy with 28% upside. NextEra Energy is rated Overweight. Key risks include power price declines, adverse policy shifts, and rising financing costs.
Key exhibits
Exhibit 1
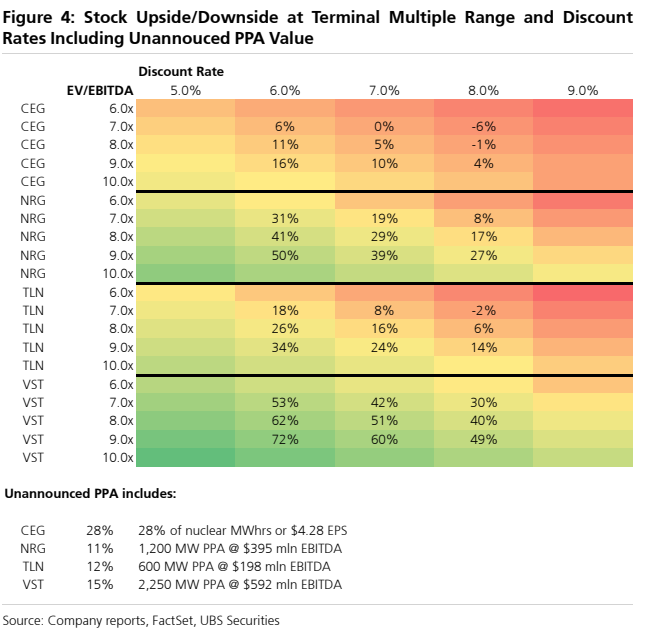
Exhibit 2
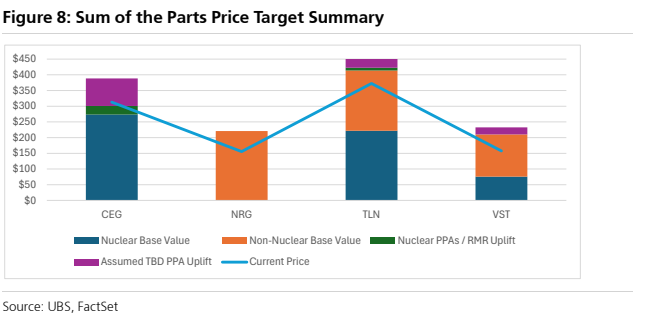
Exhibit 3