Goldman Sachs China Real Estate: Building Materials 3Q26 Preview — Persistent Demand Weakness, Divergent ASP Outlooks and Cost Inflation Pressure
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
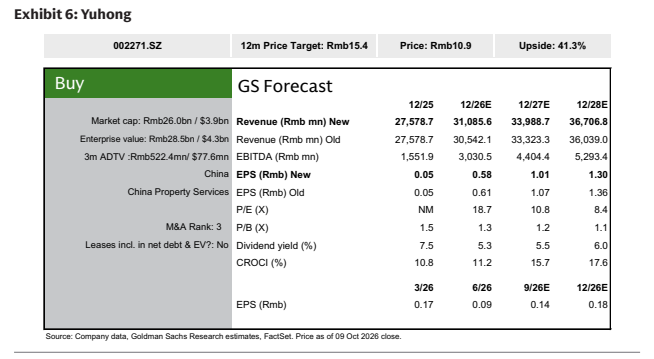
Goldman Sachs expects its covered Chinese building-materials companies to post average revenue growth of 1% but a 5% net profit decline year on year in Q3 2026. Underlying demand stayed weak, with subdued July-August activity and no clear September improvement, while rising raw-material costs — notably record-high bitumen prices — and low capacity utilization squeezed margins. Waterproofing, coatings and pipe makers diverge on average-selling-price trends and cost-inflation exposure. Firms are buffering profitability through channel deepening, product premiumization, volume-price discipline and overseas expansion. Oriental Yuhong (002271.SZ, Buy) should see faster Q3 revenue growth, but high bitumen costs pull its quarterly gross margin down to around 24%. BNBM (Buy, target price Rmb20.1) is expected to report broadly flat revenue with stable gypsum-board margins despite weak demand. SKSHU (Buy, target price Rmb28.4) faces persistent project-channel weakness, with engineering wall-paint volumes down 13% year on year. Weixing New Materials (Neutral, target price Rmb9.0) must balance margins against market share amid raw-material volatility. Goldman Sachs cut 2026-2028E EPS forecasts by 4%, 5% and 3% on average, and sees fiscal stimulus and faster fixed-asset investment as key swing factors for Q4 and next year's demand.
Key exhibits
Exhibit 1
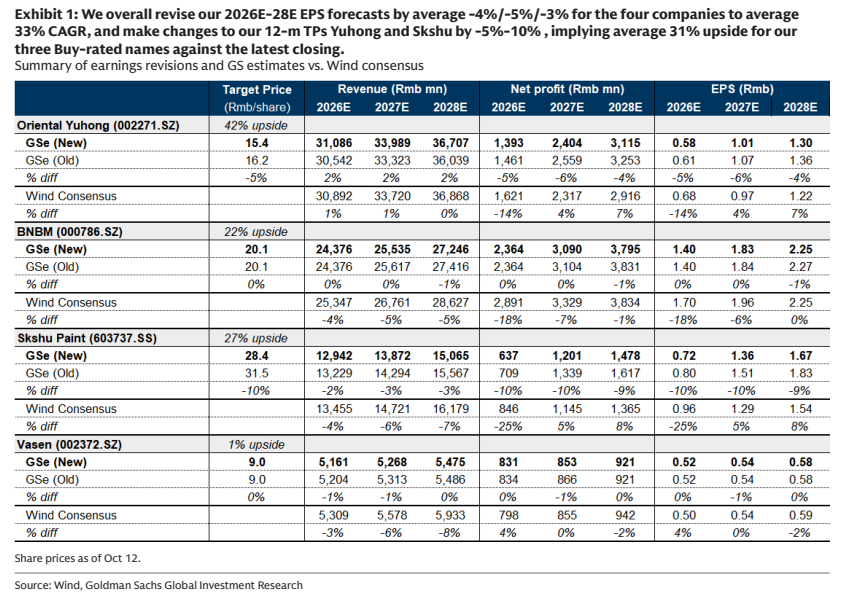
Exhibit 2
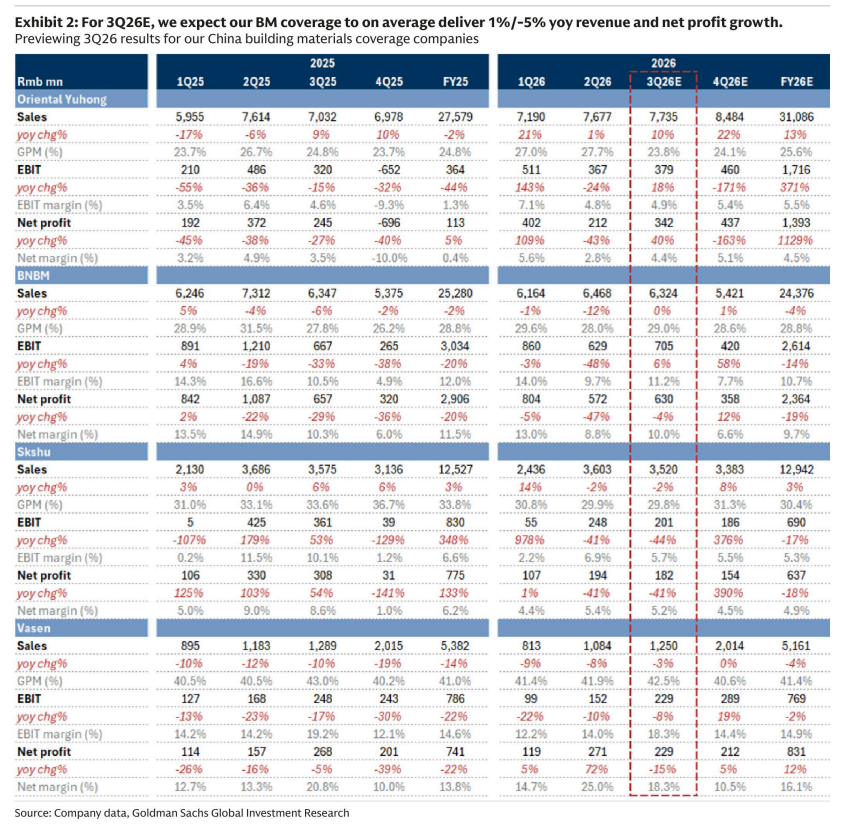
Exhibit 3
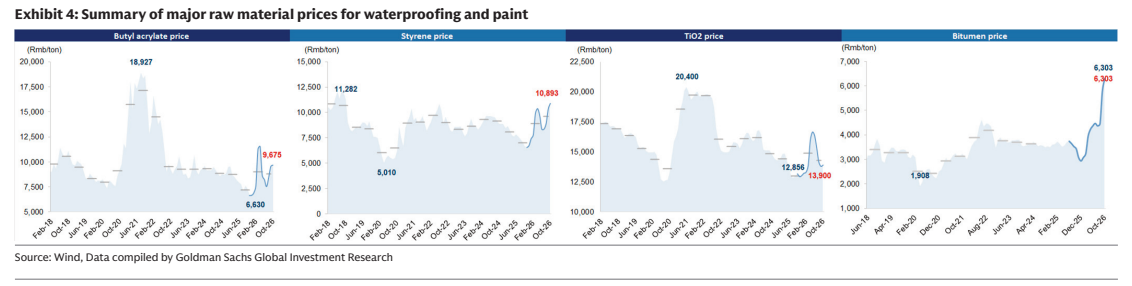
Exhibit 4
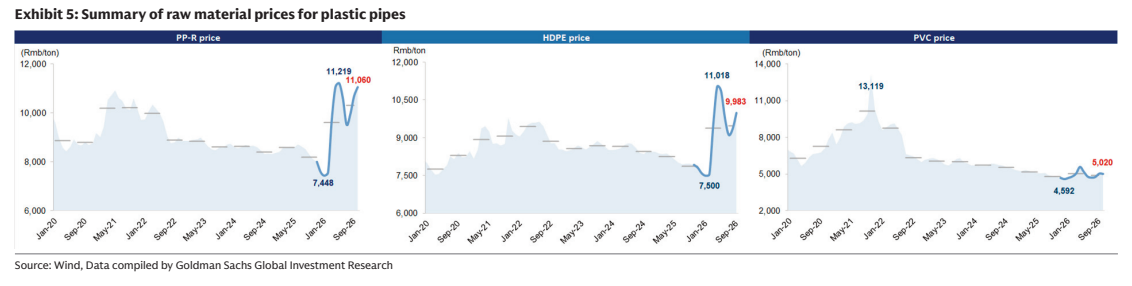
Exhibit 5