BofA Earnings Tracker, Q3 Preview: A Strong Quarter, But Tricky Questions Ahead
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Bank of America expects S&P 500 third-quarter EPS to grow 32% year-over-year, ahead of 27% consensus. The macro backdrop remains favorable—average ISM manufacturing PMI of 54.9—and corporate guidance is solid, but analysts flag downside risk to 2027 growth estimates (consensus 12%) as cost pressures build and pricing power comes under strain; mentions of 'materials costs' on earnings calls are the highest since mid-2022. AI and energy remain the primary earnings drivers, while growth outside energy, technology and the Magnificent 7 is expected to slow from 12% in Q2 to 7% in Q3. Technology ranks first for third-quarter earnings momentum and utilities last. Second-quarter capex rose 37% year-over-year, a record in the data history, and Q2 net income grew 34% with sales up 16% ex-financials. BofA notes earnings strength has not been matched by free cash flow, the mid-cap three-month earnings revisions ratio of 1.5x runs above the 1.0x long-term average, and investors will focus on the durability and monetization of the AI capex cycle. The report offers sector-level analyst previews rather than specific stock recommendations.
Key exhibits
Exhibit 1
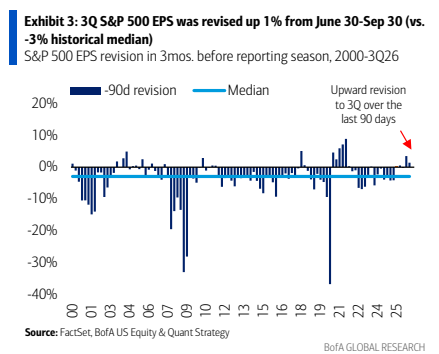
Exhibit 2
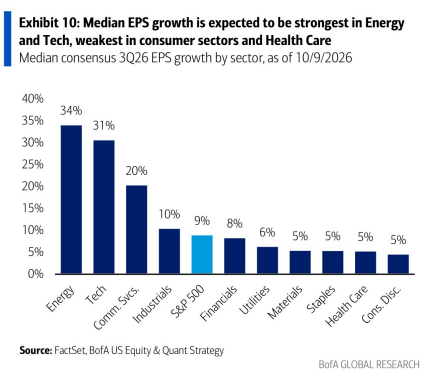
Exhibit 3
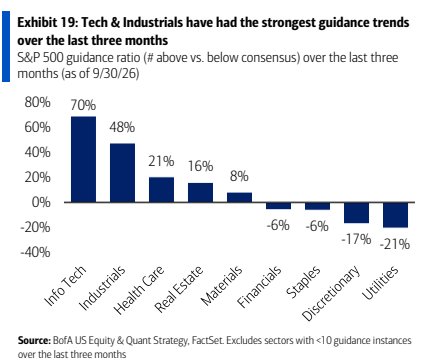
Exhibit 4
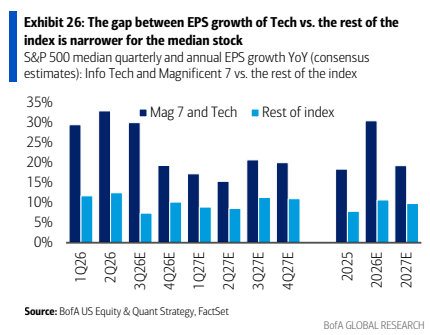
Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8
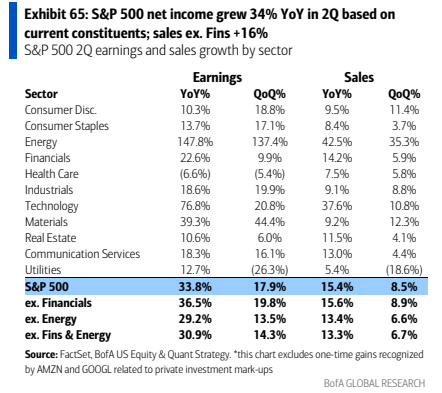
Exhibit 9

Exhibit 10
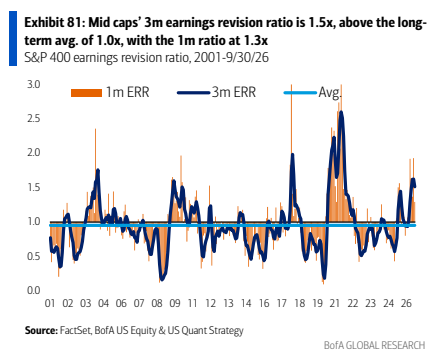
Exhibit 11
