J.P. Morgan: Hong Kong Residential Property
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
J.P. Morgan notes that Hong Kong secondary home prices have rebounded 10.4% year-to-date, or 17.9% from troughs, reaching the upper bound of the predicted 10-15% annual gain. However, price growth momentum is expected to moderate to below 5% in the second half. High-frequency data reveals emerging divergence, with primary market sales rates dropping to 64% due to aggressive developer pricing.
While capital outflow controls and interest rate hike concerns are extensively discussed, the firm identifies the persistent weakness in the Hang Seng Index as the primary downside risk. Historically, the index leads property prices by three to six months and has fallen 15% year-to-date.
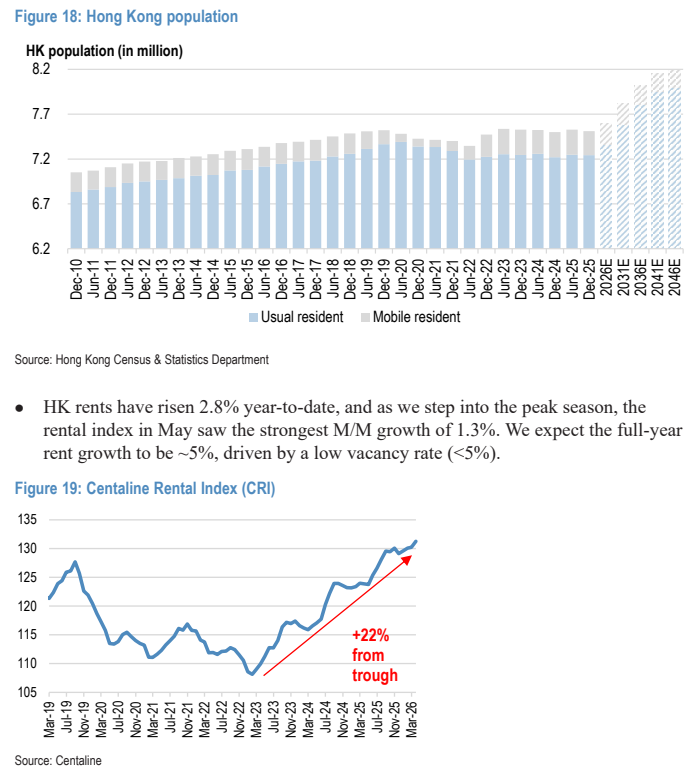
Fundamentals remain healthy, supported by optimal unsold inventory levels, rental growth, population expansion, and vacancy rates below 5%. Primary unsold inventory stands at 16,700 units, representing nine months of absorption.
Consequently, J.P. Morgan lowers target prices across covered developers by an average of 10%, adopting a defensive stock selection approach favoring net cash developers like CK Asset Holdings and Sino Group. Sun Hung Kai Properties remains a preferred pick for pullbacks despite short-term profit-taking risks. Conversely, highly leveraged developers such as New World Development and Henderson Land may lag. The sector currently trades at a 50% NAV discount and offers a 4.7% dividend yield.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
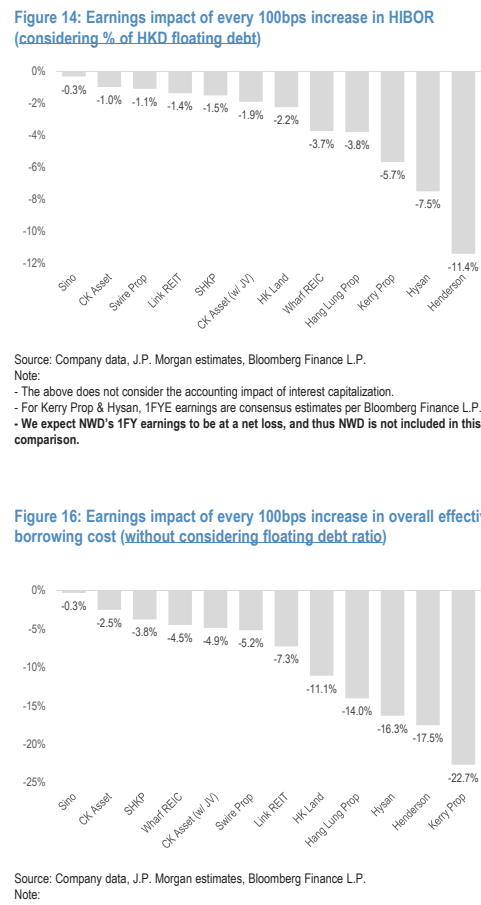
Exhibit 4

Exhibit 5