J.P. Morgan: Novo Nordisk (NOVOb.CO) Better Oral Wegovy Performance, Suggests FY'26 Sales Decline Could Be ~4%, But Even So 2027 Could Still See Limited Growth, With Only 3% Growth for 2027-30
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
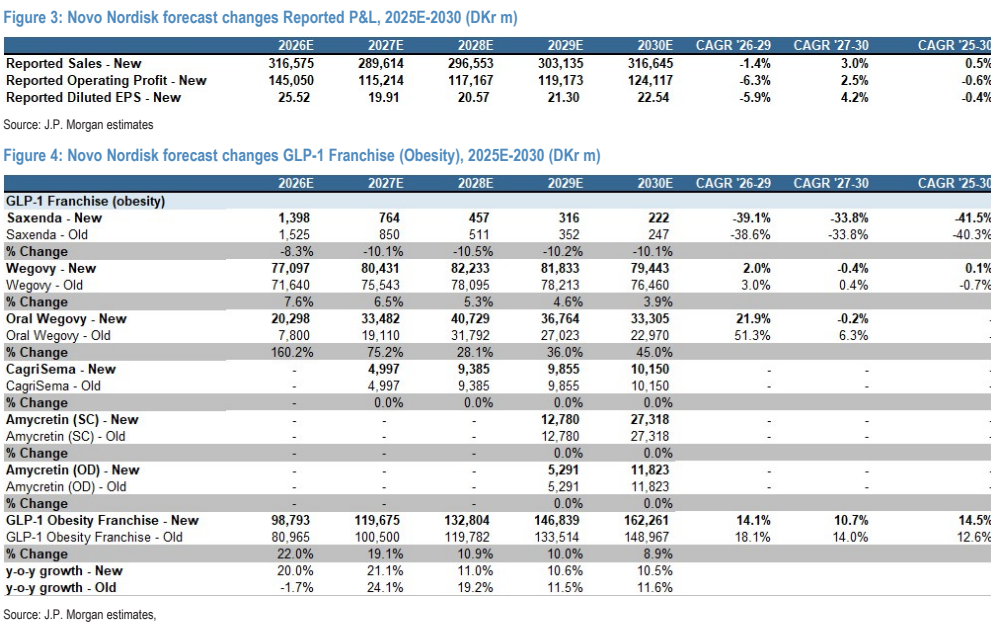
J.P. Morgan reviewed Novo Nordisk (NOVOb.CO) following improving performance trends for oral Wegovy. Despite recent positive prescription data, the bank suggests that fiscal year 2026 sales could still decline by approximately 4%. Looking further ahead, growth is projected to remain remarkably constrained, with an estimated compound annual growth rate of just 3% for the 2027 through 2030 period.
The report trimmed Novo Nordisk's 2026 to 2030 sales forecasts, reflecting intensifying competitive pressures and mounting pricing headwinds. While the near-term prescription trajectory for oral Wegovy appears encouraging, these favorable data points are ultimately insufficient to fundamentally alter the company's challenged long-term growth profile. The anticipated entry of competing oral GLP-1 therapies, particularly from Eli Lilly, is expected to erode market share and constrain pricing power.
Consequently, the competitive landscape deterioration serves as the primary risk to the bullish investment case. J.P. Morgan maintained its Neutral rating on the shares, reflecting a balanced view of the recent operational improvements against the structural challenges looming over the next several years. The investment bank did not explicitly detail a revised target price alongside this updated commercial framework. Investors are advised to monitor competitive launches and pricing dynamics as key variables influencing future revenue realization.
Key exhibits
Exhibit 1