UBS: Prada SpA (1913.HK) Q1 Signals a More Muted Earnings Cycle
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS observes that Prada's first-quarter 2026 results indicate the luxury earnings growth cycle is moderating. Although top-line growth remains positive, the pace has decelerated noticeably from previous quarters, while profitability faces mounting pressure. Prada reported Q1 revenue growth of 8% year-over-year, missing the market consensus estimate of 10%. Gross margin contracted by 1.2 percentage points to 74.5%, largely due to product mix shifts and promotional activities. Additionally, EBIT margin declined by 0.8 percentage points to 22.3%, as operating expenses outpaced revenue growth.
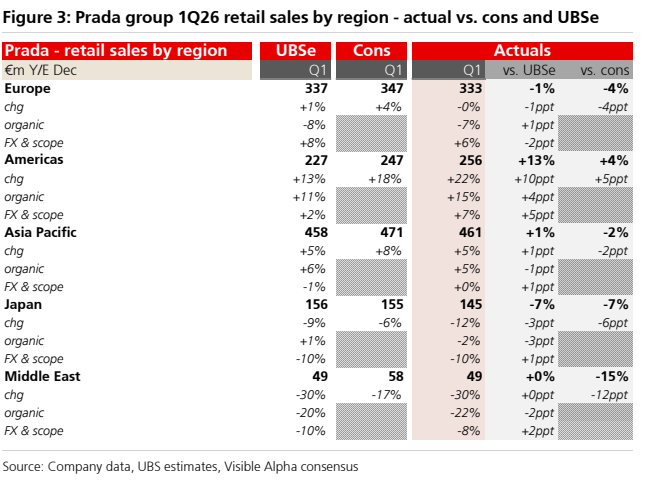
Regional performance highlights significant divergence. The Asia-Pacific region, excluding Japan, was the weakest performer with only 3% growth. In contrast, Japan surged 12%, Europe advanced 9%, and the Americas rose 7%. By category, apparel delivered the strongest performance at 11% growth, outpacing leather goods and footwear, which grew 6%.
UBS believes the peak of the earnings cycle has passed, forecasting full-year revenue growth to slow to 6-8% with an EBIT margin around 21.5%. Consequently, the bank trimmed its 2026-2028 earnings per share estimates by 3-5%. The firm maintains a Neutral rating on Prada, noting that while the current valuation of approximately 22 times forward earnings appears reasonable, the stock lacks immediate upward catalysts. While the core Prada brand momentum cools, the smaller Miu Miu brand continues to deliver robust growth.
Key exhibits
Exhibit 1
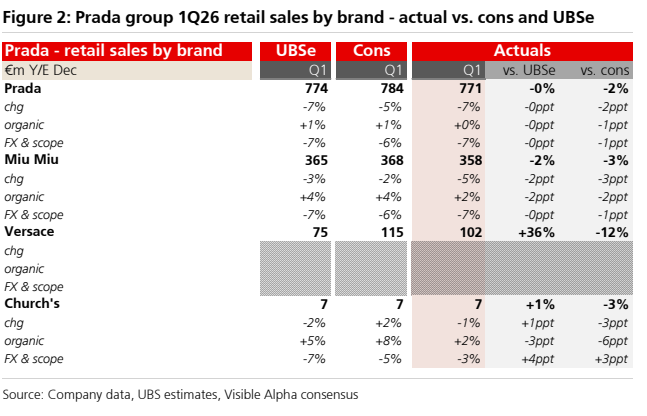
Exhibit 2