Barclays on LVMH (LVMH.PA): Beyond the Results: What Multiple Is Fair for 4% Luxury Growth?
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
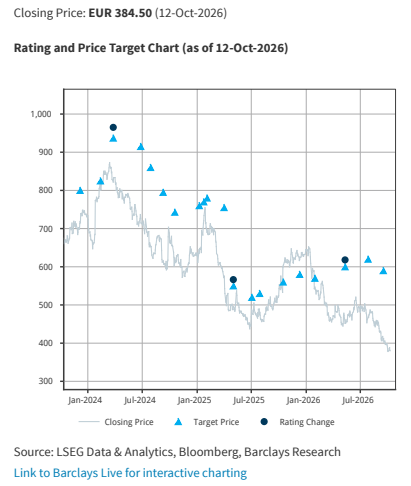
Barclays lowers its earnings estimates and target price for LVMH, reflecting a soft luxury spending environment and uncertainty around China's recovery. Q3 2026 results missed expectations, with group revenue down 1.8% year over year and organic sales in the core Fashion & Leather Goods division falling 5%, hurt by weak Chinese demand and US logistics issues. The analyst cuts FLG growth forecasts for 2027-2029 to -2%, 2% and 3%, lowers group growth for 2026-2030 from 5% to 4%, and reduces EPS estimates by 2-10%. Watches & Jewelry is expected to sustain high-single-digit growth through 2030, while FX remains a 70bp margin headwind. Applying a 0.5pt higher WACC, the target price drops from EUR 590 to EUR 470, implying 19x 2027 earnings. Despite the cuts, Barclays keeps an Overweight rating, arguing the implied multiple is reasonable for a high-quality consumer company capable of high-single-digit EPS compounding, with FLG growth recovering to about 2.3% in 2027 and stabilizing near 3% by 2030. Near term, the market needs realistic expectation resets and visible delivery on management self-help. Shares closed at EUR 384.50 on October 12, 2026.
Key exhibits
Exhibit 1
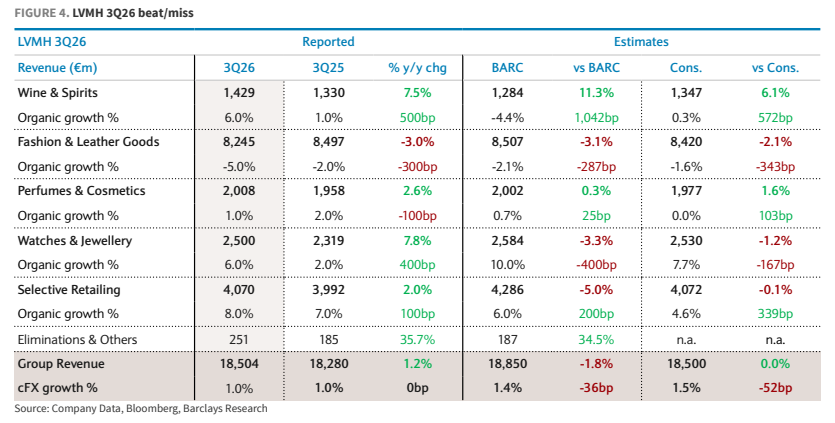
Exhibit 2
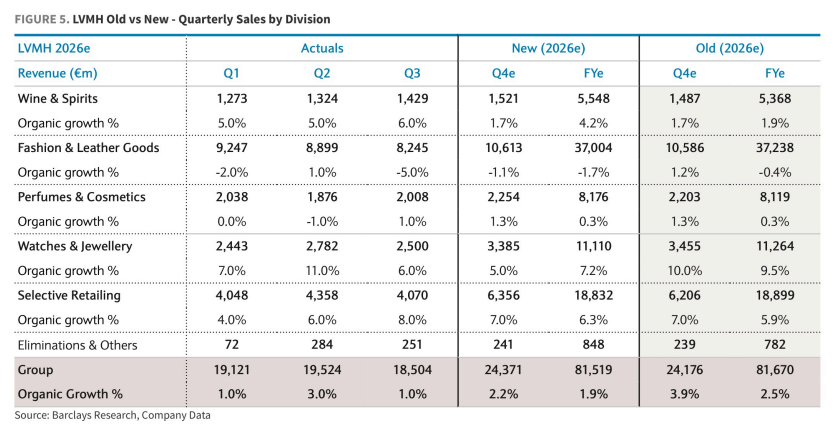
Exhibit 3
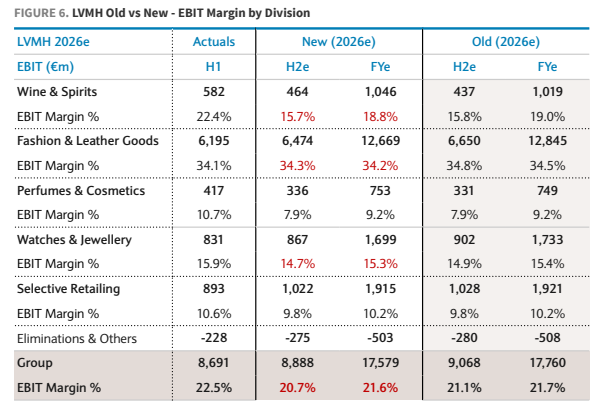
Exhibit 4
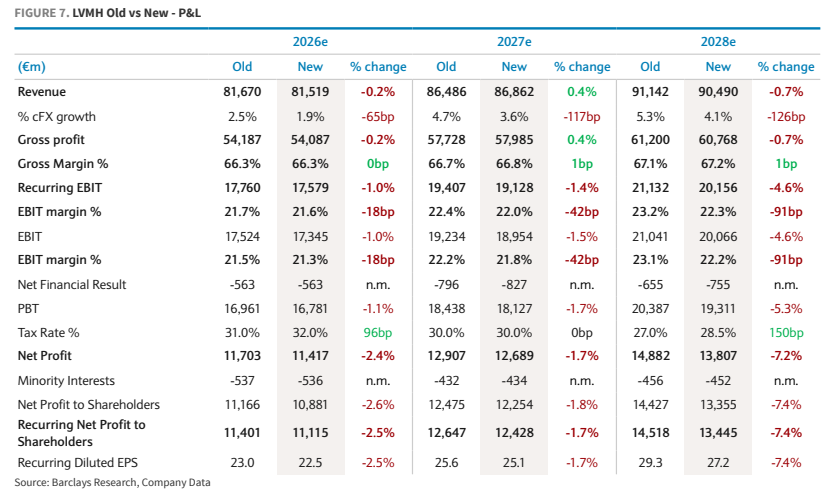
Exhibit 5
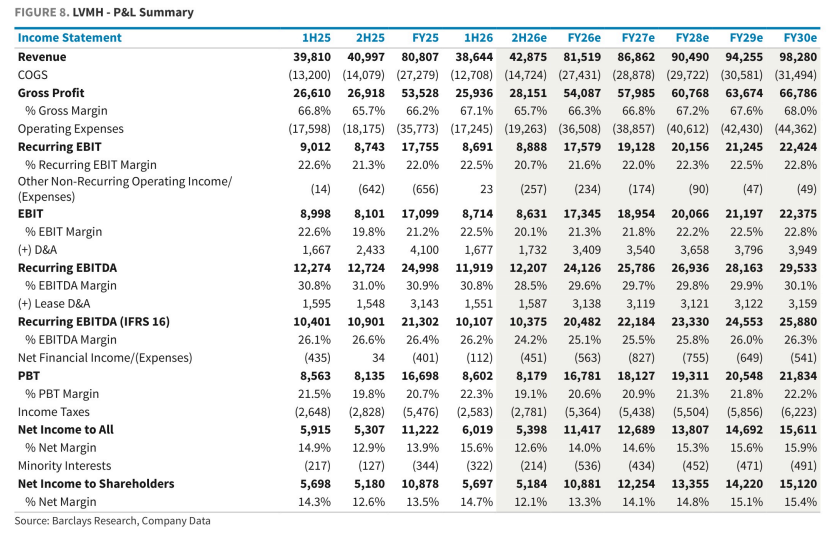
Exhibit 6
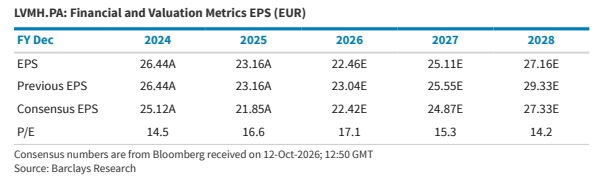
Exhibit 7
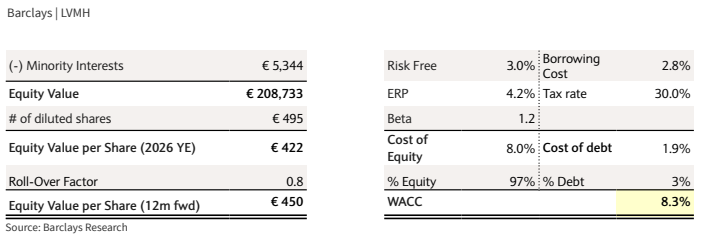
Exhibit 8