Bernstein on Johnson & Johnson (JNJ) 3Q26: Bullish Outlook, but a FY27 EPS Reset
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
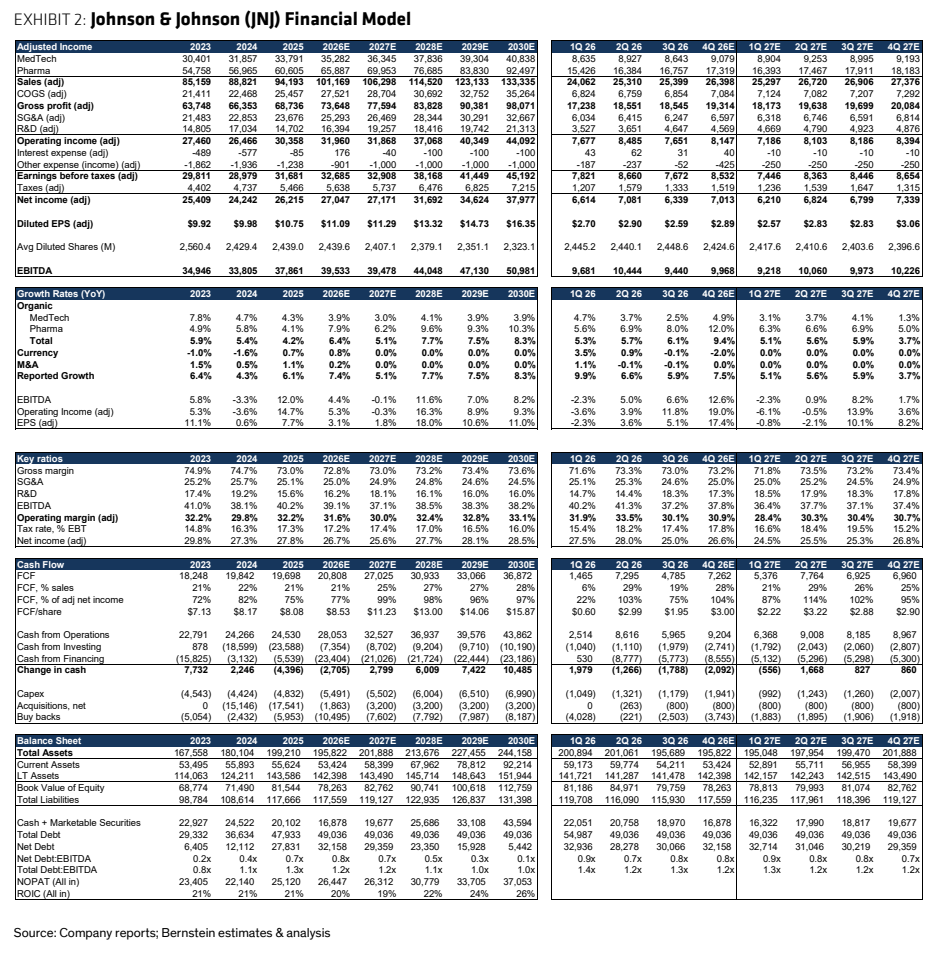
Bernstein views Johnson & Johnson's (JNJ) 3Q26 as solid: organic sales grew 6.1%, in line, and EPS of $2.59 beat by 3%. Innovative Medicine rose 8.0% organically to $16.8bn (1% beat) despite a 690bp STELARA drag, with TREMFYA up 68.2% to $2.4bn, Oncology +16.7% and Neuroscience +17.6%; MedTech grew only 2.5% to $8.6bn (1.4% miss) on Abiomed weakness, OUS surgery headwinds and Asia-Pacific electrophysiology competition. Management raised FY26 guidance—organic sales growth midpoint to 6.4%–6.8% and adjusted EPS to $11.05–$11.15—reaffirming the first $100bn revenue year in 2026 and double-digit sales growth by decade-end. FY27, however, faces three pressures: $4–4.5bn of LOE headwinds (Xarelto ~$2bn, PAH ~$1.5bn, SIMPONI/STELARA ~$1bn), Firefly/Sail dilution rising from $0.64 to $1.36 per share (a $0.72 increment, a 6.5% EPS headwind) and a tougher 53rd-week base. Bernstein models FY27 organic growth of 5.1% and EPS up just under 2% to $11.29, 8.5% below pre-print consensus of $12.34. Operationally bullish but with the EPS reset, it keeps Market-Perform and lifts the target from $261 to $270 (unchanged 21x target PE), roughly 9% above the October 13 close of $248.61. The orthopaedics separation leans spin-off, on track for mid-2027; the December 8 Enterprise Business Review should detail the 2027 outlook.
Key exhibits
Exhibit 1
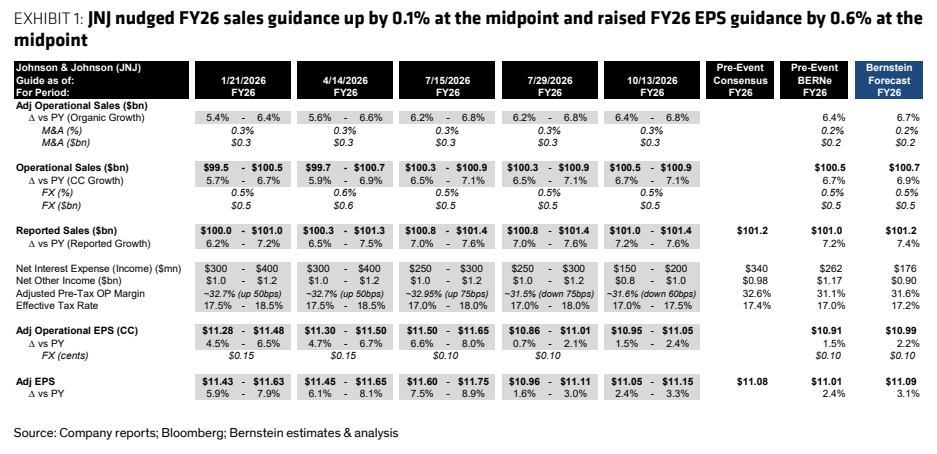
Exhibit 2