BofA - China Solar Industry: Capacity Clearing Accelerates, Leaders to Benefit
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Bank of America highlights that capacity rationalization in China's solar sector is accelerating, with supply and demand expected to approach balance by 2026. The report projects 350 GW of new global solar installations and 120 GW in China for that year. Industry-wide losses widened in 2025 as overcapacity triggered price wars, severely straining cash flows at smaller producers. Tighter policy and financing constraints are expected to force roughly 30% of small and mid-capacity offline by 2026.
Global module capacity is forecast at 500 GW against 350 GW of demand, narrowing the surplus to 150 GW. Module prices are projected to recover from a 2025 low of $0.12/W to $0.15/W in 2026, supporting margin improvement. TOPCon cell market share is expected to rise from 40% in 2025 to 55% in 2026. Leading firms are best positioned: LONGi Green Energy's market share reached 25% in 2025 with gross margins recovering to 18%, aided by cost advantages and scale. Chinese module exports grew 15% year-over-year in 2025, with 10% growth anticipated in 2026, supported by tax incentives and green credit policies. Key risks include escalating trade barriers and raw material price volatility.
BofA maintains a Buy rating on LONGi with a target price of RMB 45, citing solid leadership and technological edge. Tongwei Shares is rated Neutral with a target price of RMB 28, reflecting slower capacity expansion and limited earnings improvement. The report identifies 2026 as an industry inflection point where leaders benefit first.
Key exhibits
Exhibit 1
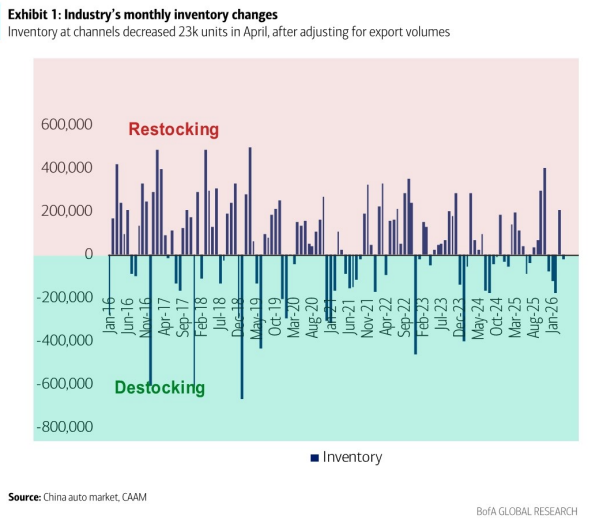
Exhibit 2
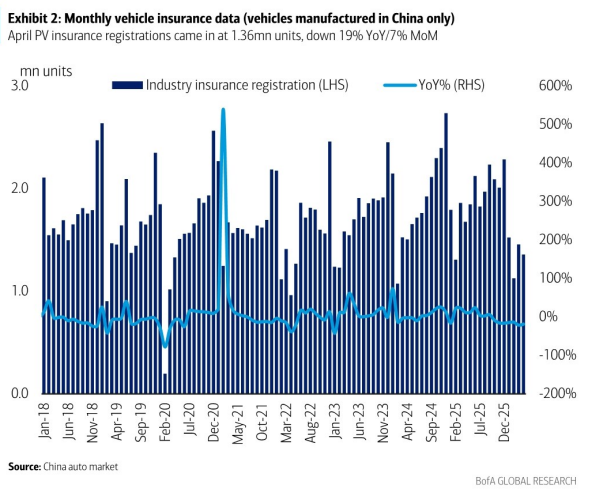
Exhibit 3
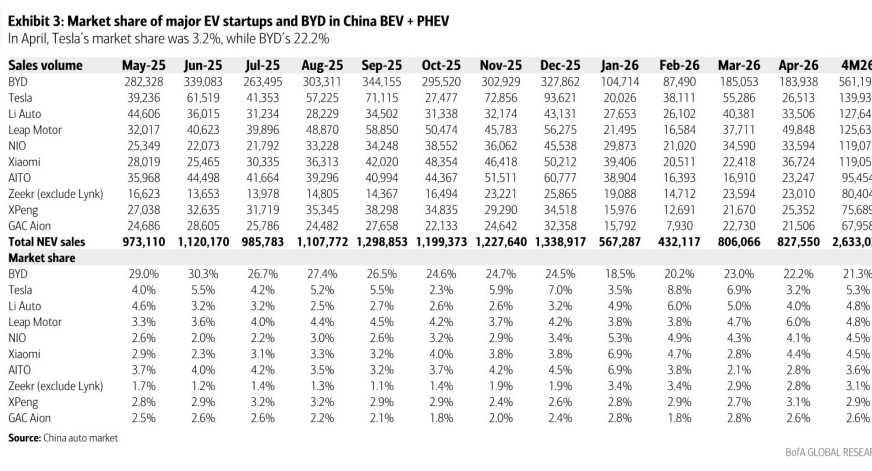
Exhibit 4
Exhibit 5
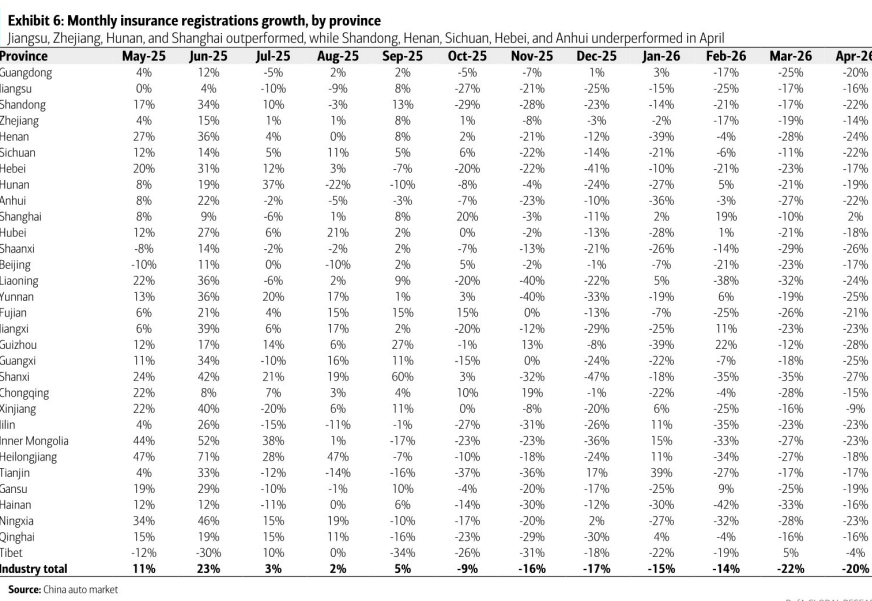
Exhibit 6