Barclays US Money Markets: RMP Likely to Reach Zero by June
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Barclays argues that US funding conditions have loosened significantly, with repo rates approaching the lower bound of the Federal Reserve's target range. Consequently, the Fed will likely reduce reserve management purchases (RMP) to zero by mid-June. This funding softness stems not only from Treasury account declines post-tax deadline but also from the substantial expansion of large bank balance sheets and repo intermediation capacity. If the reserve demand curve shifts left due to regulatory shifts or expanded balance sheet capacity, restarting quantitative tightening (QT) could be debated, though Barclays considers a 2026 restart unlikely. In the near term, the replenishment of the Treasury General Account (TGA) in July and increased bill issuance will drain reserves, potentially pushing SOFR closer to the interest on reserve balances (IORB) rate by August. Regarding positioning, Barclays recommends taking profits on the 1y1yf SOFR/FF widening trade, which moved from an entry point of -5.5 basis points to -3.5 basis points. The Fed remains cautious about creating reserve scarcity due to the asymmetric risk-return profile, as even a slight dip below ample reserves could disrupt rate control and Treasury markets. The effective federal funds rate may decline further but lag behind a potential SOFR rebound.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3

Exhibit 4

Exhibit 5
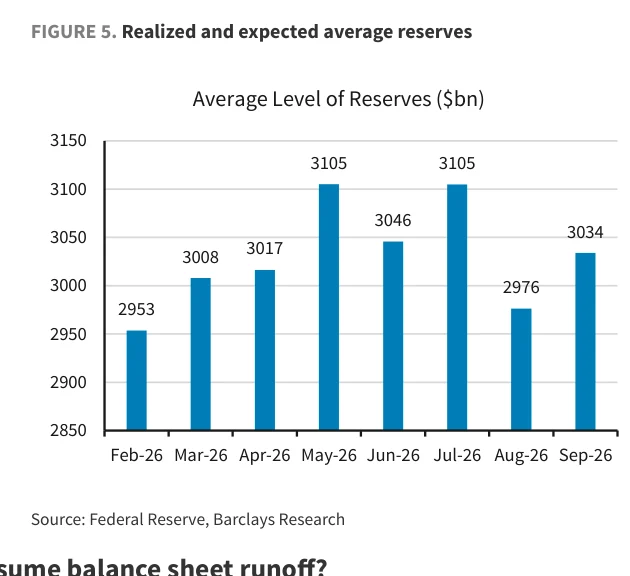
Exhibit 6

Exhibit 7
