Goldman Sachs Big Oils: Oil Price Implied in EU Big Oils and Sensitivities on a Potential Hormuz Reopening
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs conducted a detailed analysis of the long-term Brent crude oil prices currently implied by European major oil equities and assessed the potential market sensitivities surrounding a possible reopening of the Strait of Hormuz. The report determines that the share prices of EU Big Oils are discounting a long-term Brent crude price of approximately $65 per barrel, which sits below the prevailing spot price of around $75 per barrel.
In a scenario where the Strait of Hormuz reopens, global oil supply could increase by an estimated 2 million barrels per day. Goldman Sachs estimates this supply addition could pressure Brent prices downward by $5 to $10 per barrel. Through sensitivity analysis, the bank quantifies the earnings impact: for every $5 per barrel decline in oil, BP's earnings would drop by roughly 8%, Shell by 7%, and TotalEnergies by 6%.
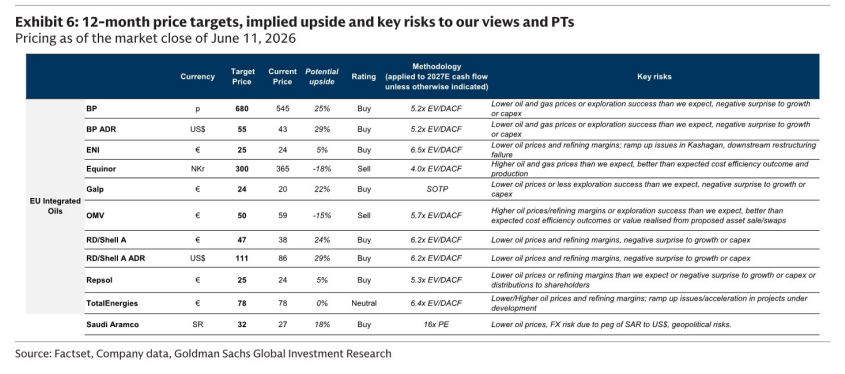
The firm maintains its specific stock recommendations based on these risk assessments. BP is rated Buy with a target price of 600 pence, as its current valuation implies a lower oil price than Goldman Sachs's long-term forecast. Shell is rated Neutral with a 2,800 pence target, reflecting fair valuation balanced by high earnings sensitivity. TotalEnergies is rated Sell with a target of 55 euros due to elevated valuation multiples despite lower sensitivity.
The report notes that EU Big Oils currently trade at historically low valuations of roughly 8 times forward earnings. If oil prices sustain levels below $65 per barrel, dividend sustainability and share repurchase programs could face material risks.
Key exhibits
Exhibit 1
Exhibit 2
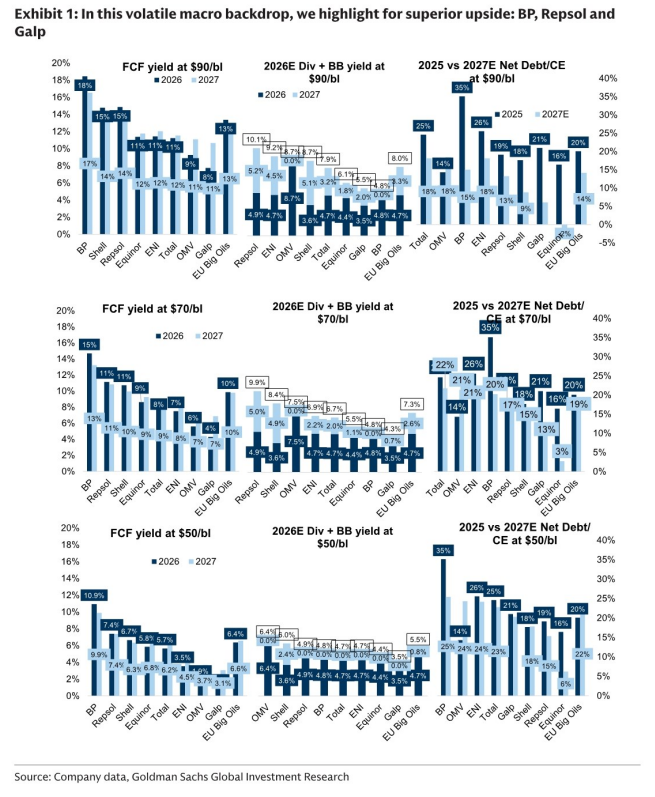
Exhibit 3
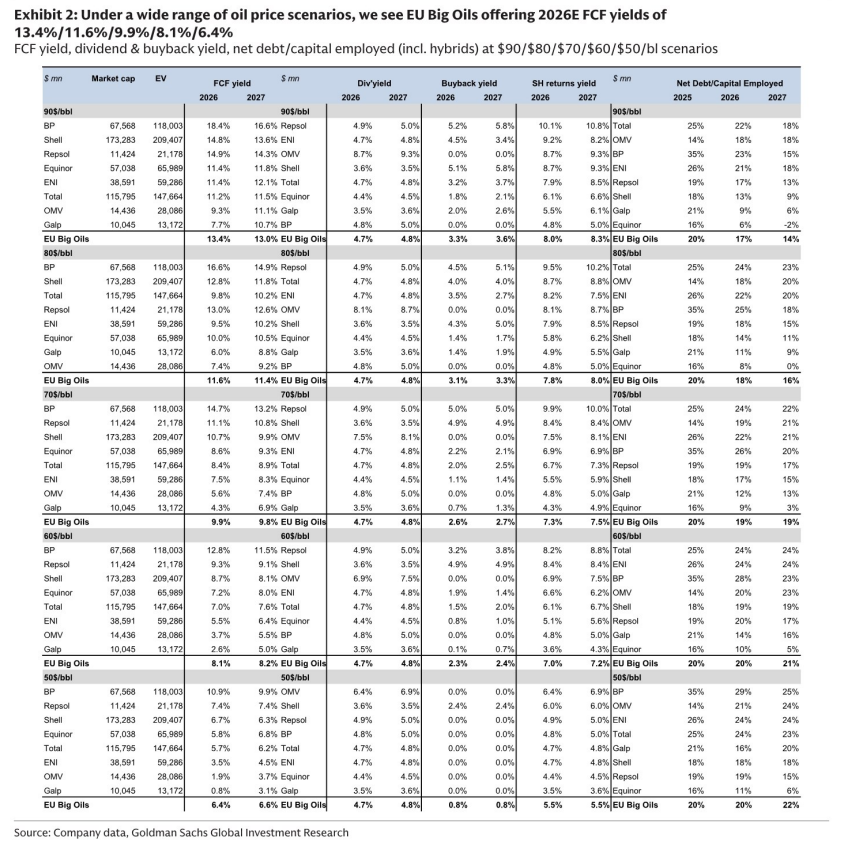
Exhibit 4
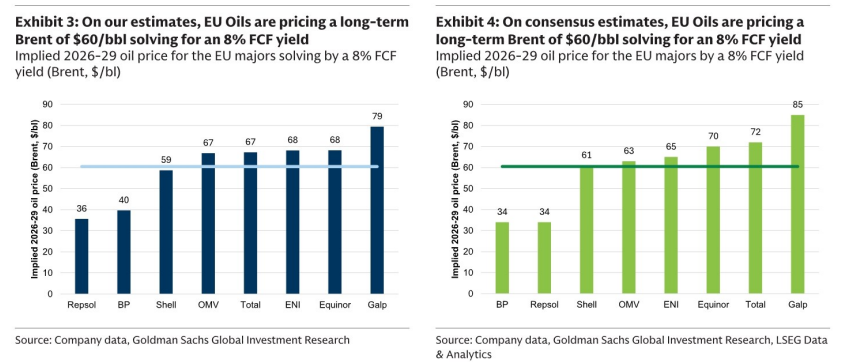
Exhibit 5
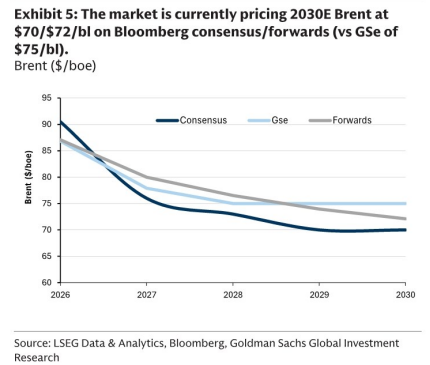
Exhibit 6