Deutsche Bank on Coca-Cola (KO.US): Q3 2026 Earnings Watch Points
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Ahead of Coca-Cola's (KO.US) Q3 2026 results, Deutsche Bank reiterates its Buy rating and USD 98.00 target price. The company maintains strong global momentum, with its franchise model shielding it from pressures facing consumer goods peers. Softness in Mexico, Turkey/Middle East and Thailand is being offset by relative strength in Europe and Brazil. Deutsche Bank forecasts Q3 organic growth of 4.3% on total revenue of USD 12.91 billion, with regional organic growth of +4% North America, +6.5% EMEA, -4% Asia Pacific, +7% Latin America and +7% Bottling Investments Group. Q3 EPS is estimated at USD 0.85, below consensus of USD 0.88. For full-year 2026, the bank models organic growth of 5.1% and EPS of USD 3.30, expecting management to reaffirm guidance of 5% organic growth and 9-10% EPS growth. For FY2027, organic growth is projected at 5.3% with 7% EPS growth, though currency headwinds and the CCBA refranchising could each impose low-to-mid single-digit drags on revenue and EPS. The IRS tax case appeal outcome remains a key consideration.
Key exhibits
Exhibit 1
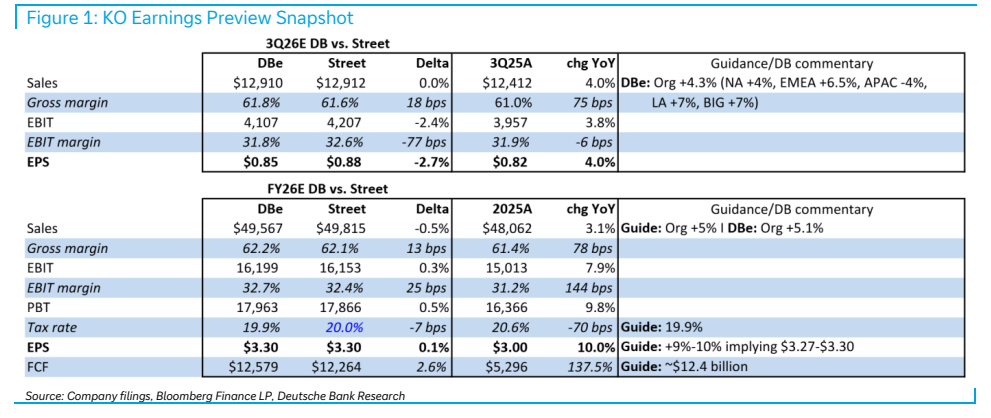
Exhibit 2
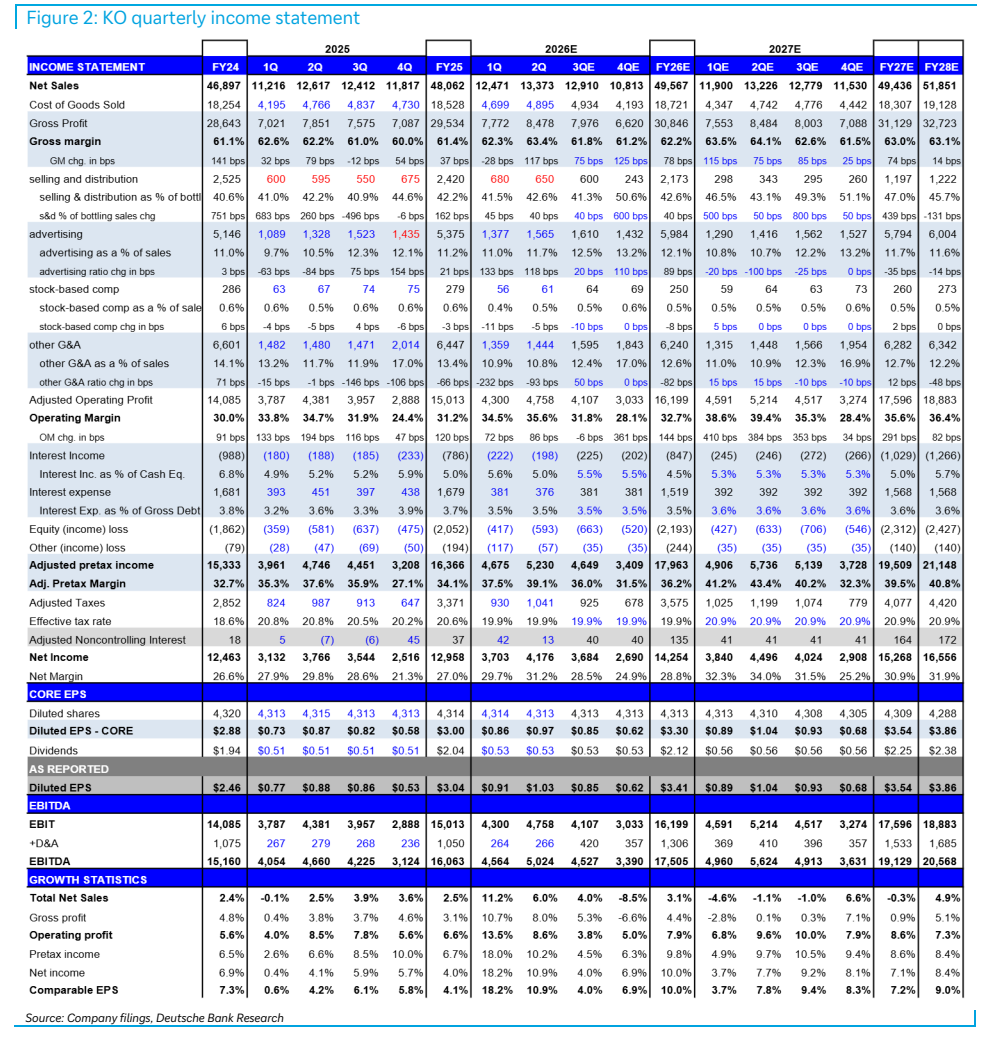
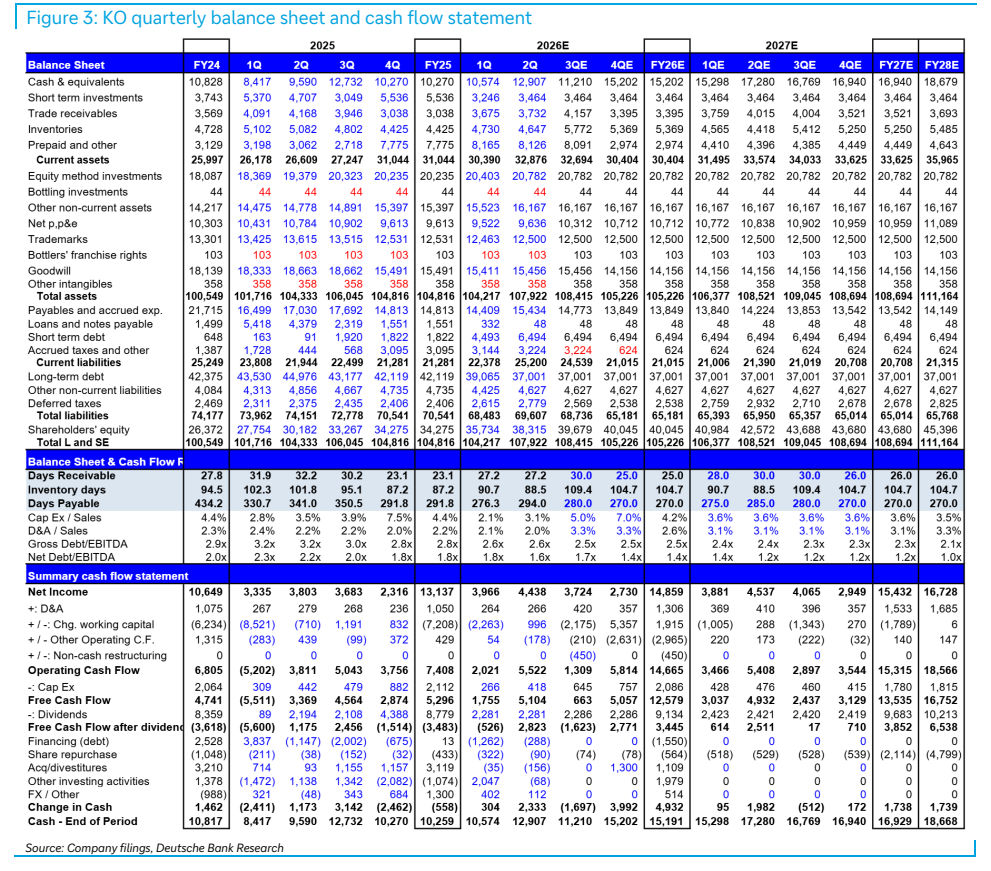
Exhibit 3