Goldman Sachs on StubHub Holdings (STUB): Q3 2026 Earnings Preview — Framing the Key Debates and Themes
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Abstract
Goldman Sachs' Q3 2026 preview for StubHub Holdings (STUB) frames the key debates ahead of results. The bank forecasts gross merchandise sales of $2.65 billion, revenue of $510 million, and adjusted EBITDA of $117 million, implying a 23.0% margin, with the full-year take rate near 20%. Despite macro volatility and concerns about some event cancellations, channel checks point to robust live-event demand, with operating leverage building in the second half—Q3 and Q4 margins are seen at 23% and 25%, respectively. September global app downloads grew 50% year-over-year and monthly active users 12%. Regulatory risk appears fragmented rather than a coordinated wave, and implementation is proving more complex and time-consuming than initially expected, implying less near-term structural pressure.
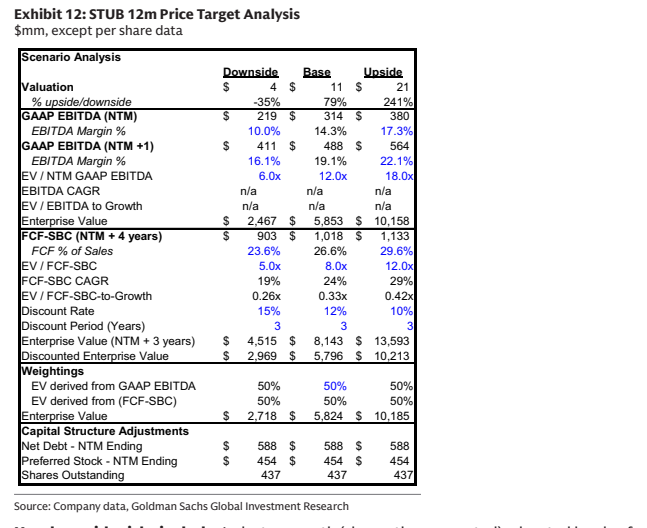
The analysts reiterate a Buy rating but cut the 12-month target to $11 from $16, reflecting the current valuation environment for consumer internet and marketplace stocks. Key themes include marketing efficiency, the evolving regulatory backdrop, and future growth drivers, and the company is expected to reaffirm its 2026 guidance.
Key exhibits
Exhibit 1
Exhibit 2
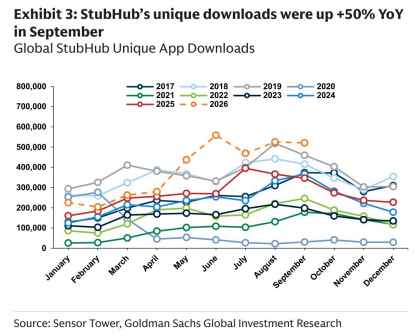
Exhibit 3
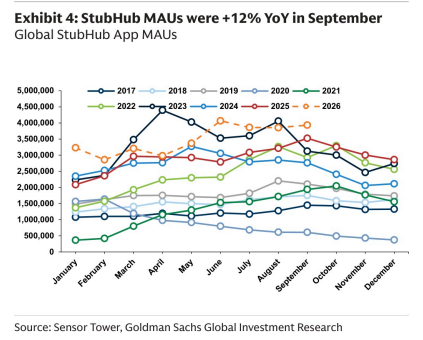
Exhibit 4
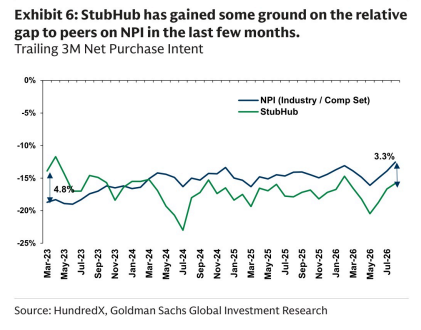
Exhibit 5
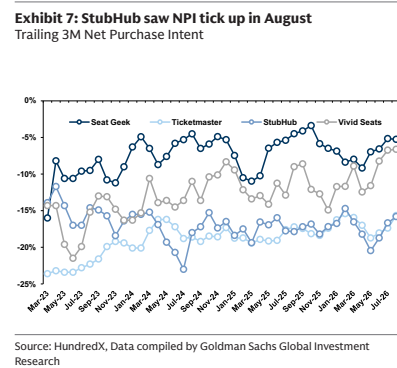
Exhibit 6
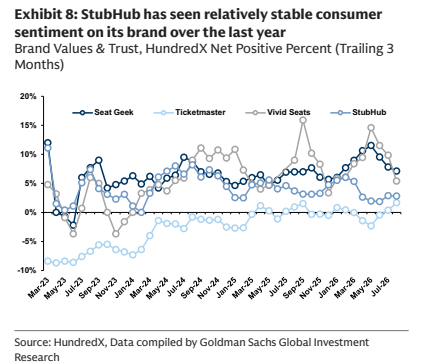
Exhibit 7
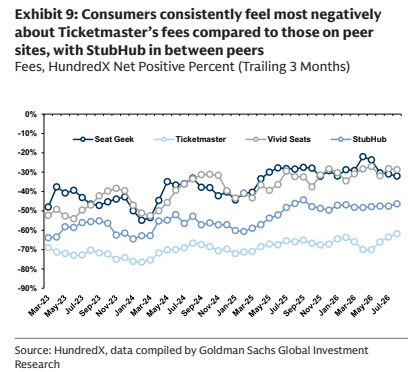
Exhibit 8
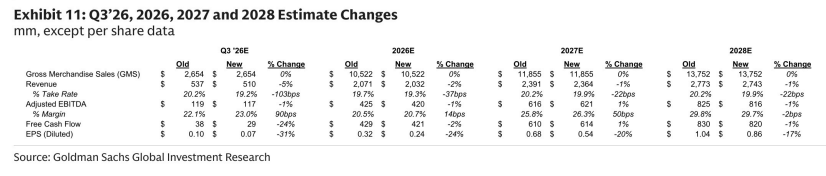
Exhibit 9