UBS Rode & Speyer: Why You Should Care About the Powertrain Portfolio
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
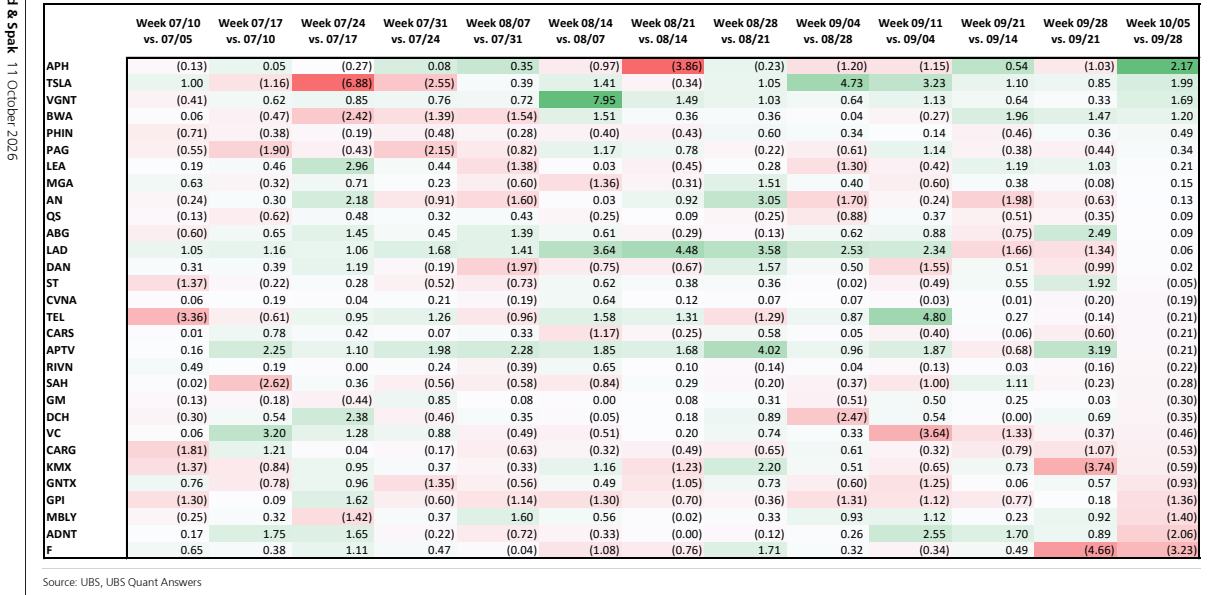
UBS's Rode & Speyer report argues that auto parts suppliers face persistent geographic and customer-mix headwinds driven by dynamics in China and Europe. Chinese domestic OEMs are taking share from foreign manufacturers producing in China, the customers many suppliers have historically depended on, while European luxury demand weakens and Chinese OEM exports to Europe rise, with suppliers often lacking content on exported models. Western OEMs may increasingly source from Chinese suppliers to cut costs, starting in Europe, with Chinese supplier plants in the US not ruled out longer term. Parts standardization, as pursued by BMW, is a double-edged sword: it can lift scale but may compress pricing and margins amid intensified competition. 2026 may mark the peak year of China ICE sales declines. In Europe, EV adoption is accelerating - BEVs grew 39% year-over-year through August 2026 to roughly 23% share - while UBS expects European ICE/hybrid production to fall 8% in 2027, versus North American levels that should stay stable over the decade. PHIN, BWA and MGA could be hurt by the European production decline, though BWA and MGA may offset via EV powertrain programs; APTH, APH, TEL, VGNT and ST have cited rising electrification content.
Key exhibits
Exhibit 1
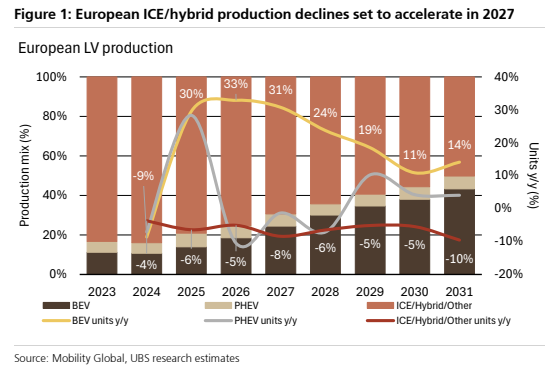
Exhibit 2
Exhibit 3
Exhibit 4
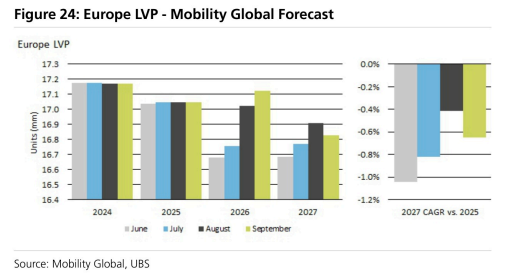
Exhibit 5
Exhibit 6
Exhibit 7

Exhibit 8
Exhibit 9
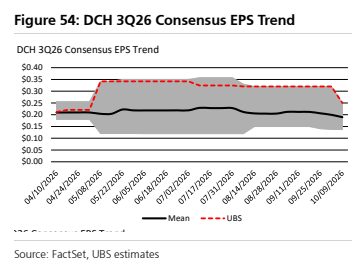
Exhibit 10
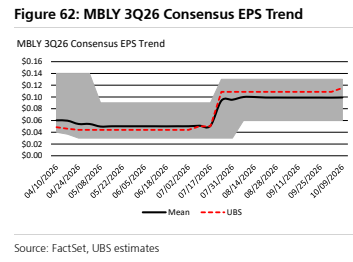
Exhibit 11
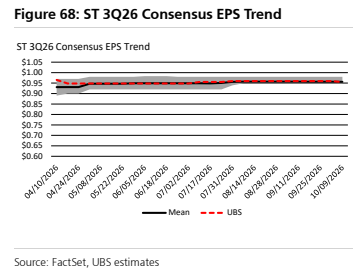
Exhibit 12