Goldman Sachs: LG Energy Solution (373220.KS) Core 2Q Operating Margins Miss; Buy Rating Maintained
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs maintains its Buy rating on LG Energy Solution (373220.KS) with a 12-month target price of KRW 520,000, arguing the market underestimates the company's utilization recovery and medium-term earnings visibility. On July 7, LGES released preliminary 2Q26 results showing ex-AMPC revenue of KRW 7.3 trillion, up 15% quarter-over-quarter and 32% year-over-year, broadly in line with consensus. AMPC came in at KRW 241 billion, implying US battery shipments recovered to approximately 5 GWh from around 4 GWh in 1Q26.
However, operating profit reached KRW 113 billion, falling short of Goldman Sachs' KRW 224 billion estimate and Bloomberg consensus of KRW 204 billion. The ex-AMPC operating margin improved sequentially to negative 1.7% from negative 6.2% in 1Q26. Goldman Sachs attributes the softer margins to timing of OEM take-or-pay compensation and ESS production line conversion costs.
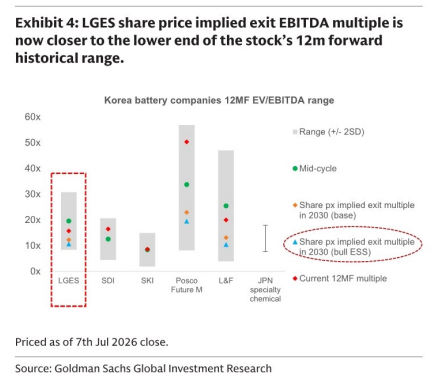
Revenue growth was driven by the ESS ramp and resilient cylindrical battery demand, while US EV pouch capacity remained constrained by the GM JV shutdown. The analyst call on July 30 will likely focus on the path to core profitability, ESS margin sustainability amid potential overcapacity, and the GM JV restart timeline. Goldman Sachs expects EBITDA to double from FY26E through FY28E, with utilization rising from approximately 42% in FY26E to roughly 67% by 2028E. Key downside risks include slower market share gains and weaker global EV penetration.
Key exhibits
Exhibit 1
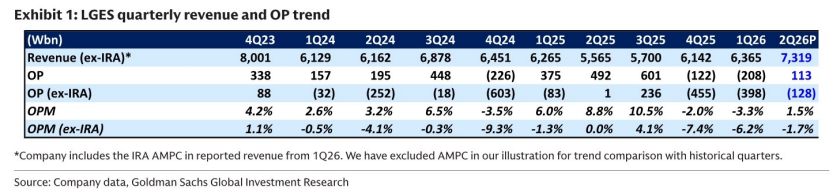
Exhibit 2
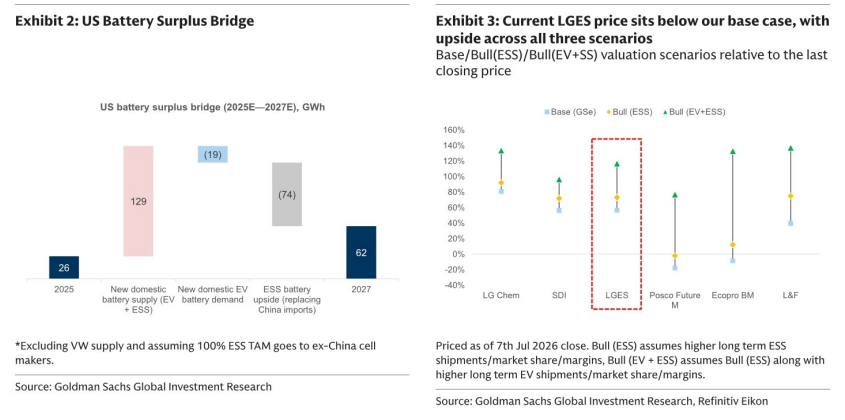
Exhibit 3