UBS: China Aluminium — Capacity Limit Intact; Valuation Reset Creates Opportunities
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS maintains that China's aluminium supply-side reform capacity cap of 45.43 million tonnes (mt) remains firmly intact, arguing that market fears regarding oversupply are overblown. The firm projects Chinese aluminium production at 45.6 mt in 2026 and 46.0 mt in 2027—marginally above the capped capacity but far from a return to the unconstrained expansion seen between 2009 and 2017. Effective capacity utilization has anchored at approximately 100% (plus or minus 2%) since 2021. On a global scale, the aluminium market is expected to see a deficit of 1.1 mt in 2026 before reaching a basic balance in 2027.
In response to softer near-term demand projections, UBS has lowered its 2026-2027 aluminium price forecasts to Rmb23,000/t and Rmb22,500/t, respectively. Consequently, earnings estimates for covered companies were cut by 9-33%, and target prices were reduced by 19-21%. Despite these downward revisions, the current valuations still imply a compelling 60-80% upside.
Chinese demand remains weak in 2026, dragged down by real estate and solar sectors, though robust export growth (up roughly 40% year-over-year in the first five months) provides a buffer. In 2027, improving automotive lightweighting, machinery sales, and power transmission demand are expected to offset property drags. UBS reiterates Buy ratings on China Hongqiao (target HK$36.80), Chalco H-shares (target HK$14.20) and A-shares (target Rmb13.50), and Tianyuan Manganese (target Rmb18.10).
Key exhibits
Exhibit 1
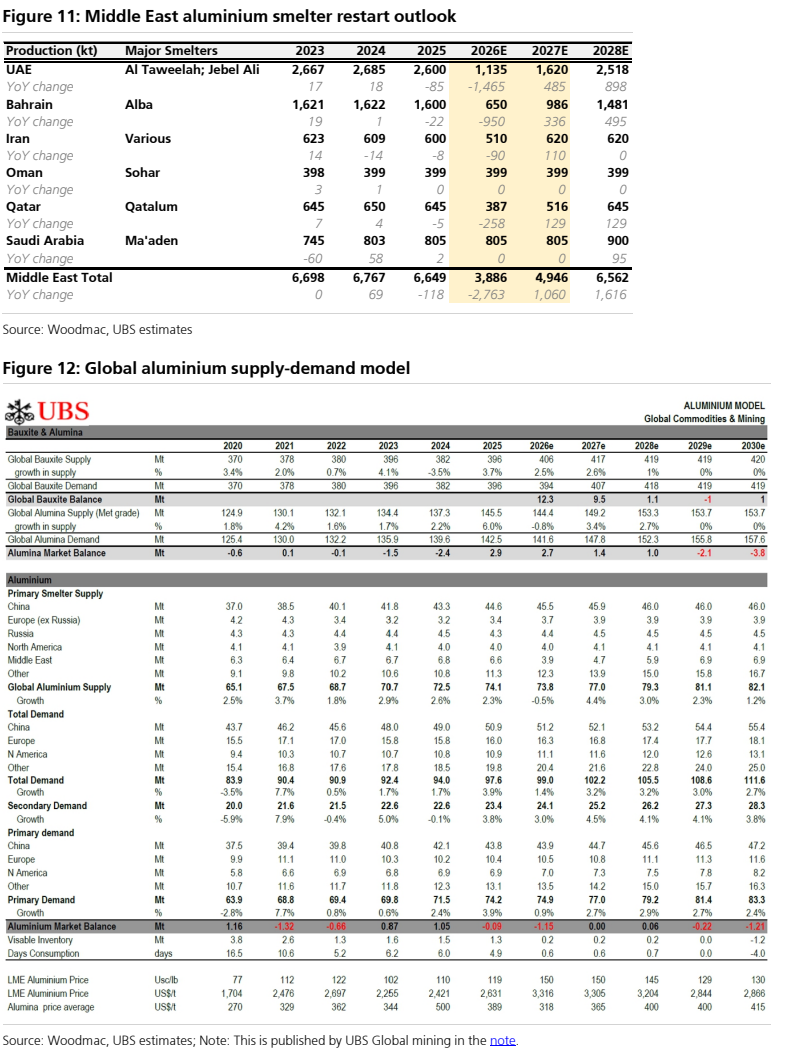
Exhibit 2
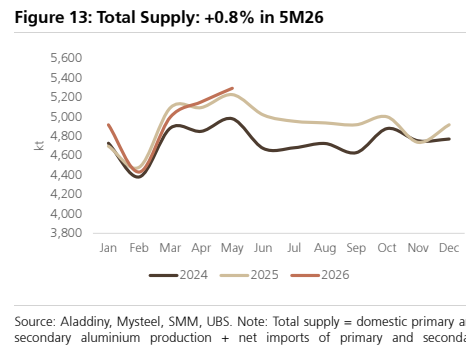
Exhibit 3

Exhibit 4
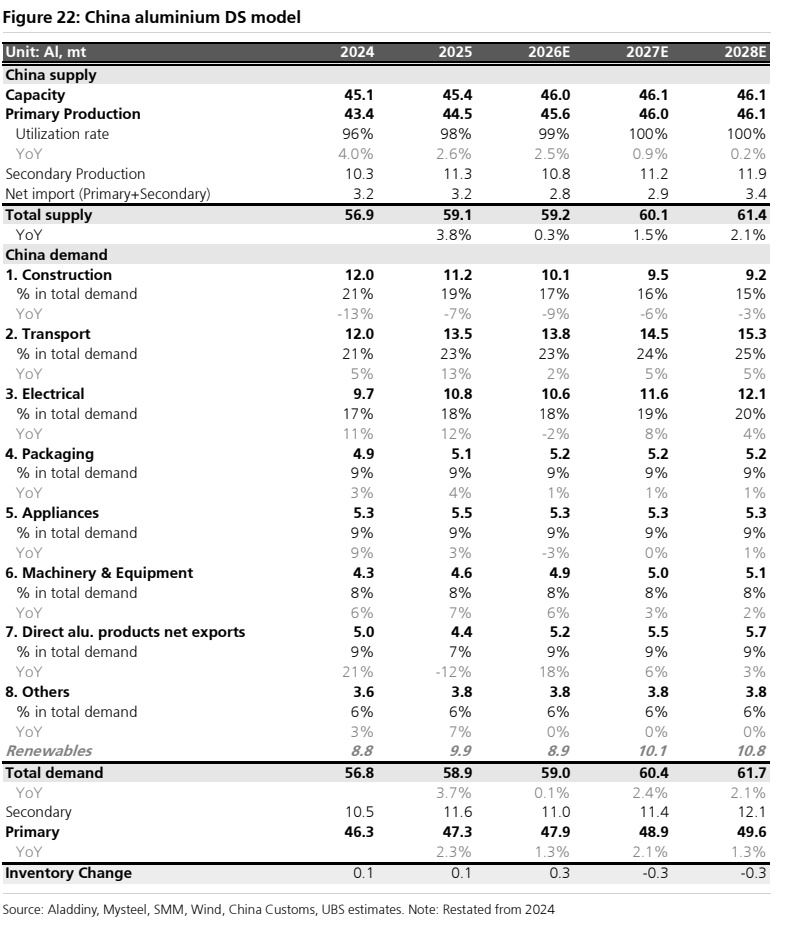
Exhibit 5

Exhibit 6
