Goldman Sachs | CATL (300750): 3Q26 Preview - Strong Volumes, but Unit Margins in Focus; Buy (Conviction List)
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
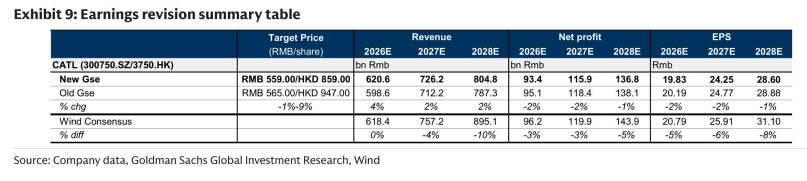
Goldman Sachs previews CATL's third-quarter 2026 results ahead of the October 20 release, forecasting net profit of RMB 24 billion, up 30% year-on-year and 7% quarter-on-quarter. Battery sales are seen at 260 GWh (+58% YoY, +11% QoQ), supported by production above 300 GWh (+64% YoY, +17% QoQ) based on monthly run-rate and utilization analysis. The focus falls on unit profitability: unit net profit is expected to slip 4% sequentially to RMB 93/kWh from RMB 97/kWh in the second quarter, reflecting raw material swings, as lithium carbonate prices fell 14% quarter-on-quarter, inventory impairment risk on a high stock balance of about RMB 131 billion at end-2Q26, and the battery consumption tax raised from 0% to 2% in September, which could drag on results by up to RMB 700 million if not passed through. Goldman estimates CATL built 64 GWh of battery inventory in 1H26, taking the balance to 250 GWh. Key swing factors include the energy storage mix and tax pass-through. The bank forecasts 2026 EPS of RMB 19.83 and maintains Buy (Conviction List) with target prices of RMB 559 for the A-shares (300750.SZ) and HKD 859 for the H-shares (3750.HK).
Key exhibits
Exhibit 1
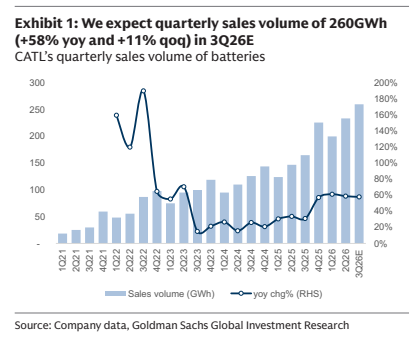
Exhibit 2
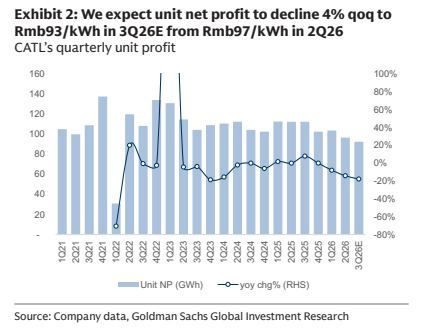
Exhibit 3
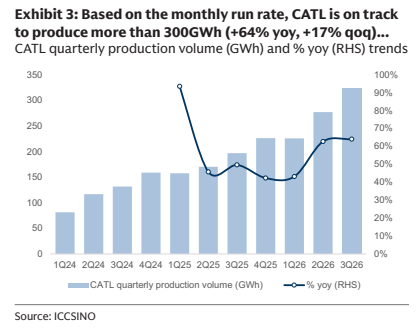
Exhibit 4
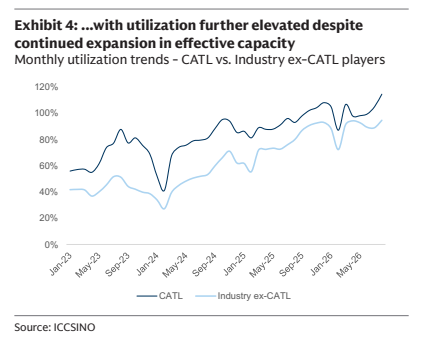
Exhibit 5
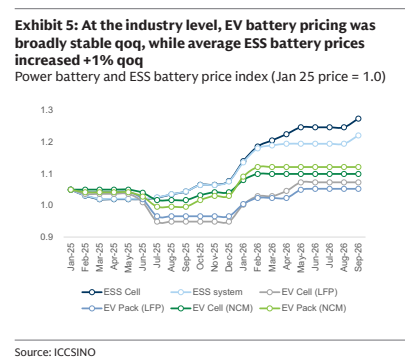
Exhibit 6
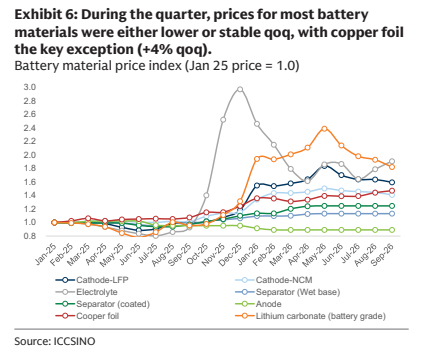
Exhibit 7
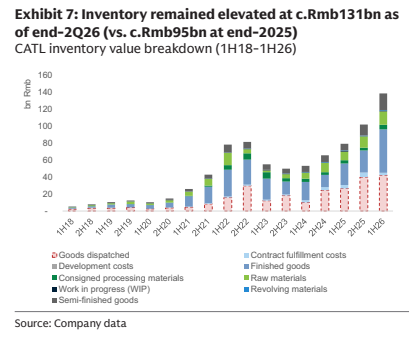
Exhibit 8
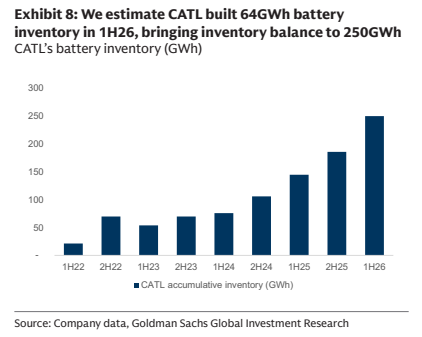
Exhibit 9