Goldman Sachs | WUS Printed Circuit (002463): AI Server and Switch Demand Drives AI PCB Ramp; Spec Upgrades Lift Gross Margin; Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
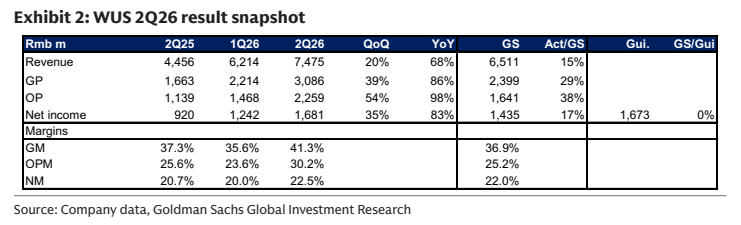
Goldman Sachs maintains its Buy rating on WUS Printed Circuit (002463.SZ), citing rising demand for AI servers and switches. The company is expected to post third-quarter 2026 revenue of RMB 7.8 billion, up 5% quarter-on-quarter, with gross margin improving to 37.6% on a better product mix, versus 35.8% a year earlier. Goldman lifted its 2026-2028 earnings forecasts by 8%, 4% and 4% respectively, driven by data center PCB revenue growth, and raised its 2027 total addressable market for AI server PCBs to $38 billion. Revenue from high-speed network PCBs and AI server PCBs is projected to compound at 63% annually over 2026-2028 as specification upgrades lift pricing and margins. The company continues to expand AI PCB capacity in China and Thailand while advancing new product technologies. The thesis runs from growing AI server and switch demand, to PCB specification upgrades and capacity ramps, to an optimized product mix that supports both gross margin and revenue, underpinning the earnings upgrades.
Key exhibits
Exhibit 1
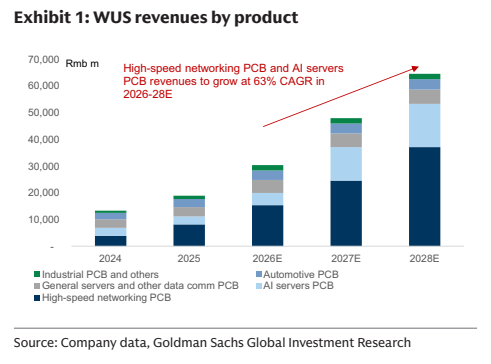
Exhibit 2