Barclays Global Semiconductors: BAPT - September 2026: Pricing Decelerating but Still Strong
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Barclays updates its Analog Pricing Tracker (BAPT), adding a lead-time indicator for the first time. The September 2026 semiconductor pricing environment remained positive but decelerated versus August, with 12 of 15 core categories posting sequential price increases. Power semiconductors led, with IGBTs and silicon carbide (SiC) showing the strongest gains. Although month-end inventories rebounded, monthly average levels indicate the industry is still destocking. Lead times extended broadly, with SiC products longest at 35-49 weeks. Barclays views MCU and power semiconductor trends as constructive for STMicroelectronics, Infineon, NXP and Texas Instruments. Early signs of industrial MCU restocking and pricing resilience offer potential upside: these dynamics could support STMicroelectronics exceeding its Q4 revenue guidance, while pricing tightness at Infineon may support positive FY2027 guidance when it reports this quarter. NXP and Texas Instruments continue to see steady pricing, with the inventory backdrop more favorable for Texas Instruments. The tracker's combined view of pricing, inventory and lead times frames channel conditions and company-level guidance implications across the analog and embedded semiconductor names covered.
Key exhibits
Exhibit 1
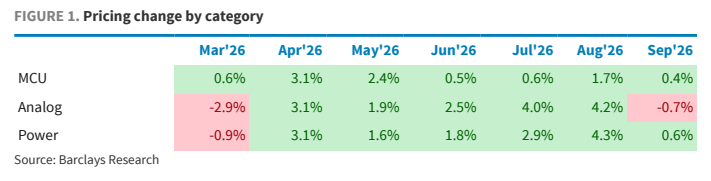
Exhibit 2
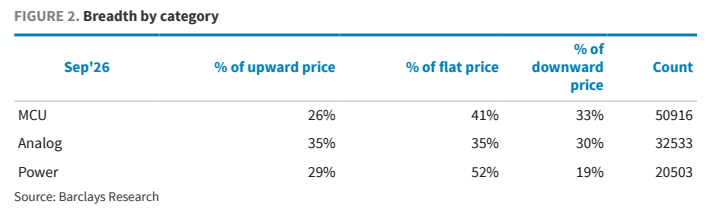
Exhibit 3

Exhibit 4
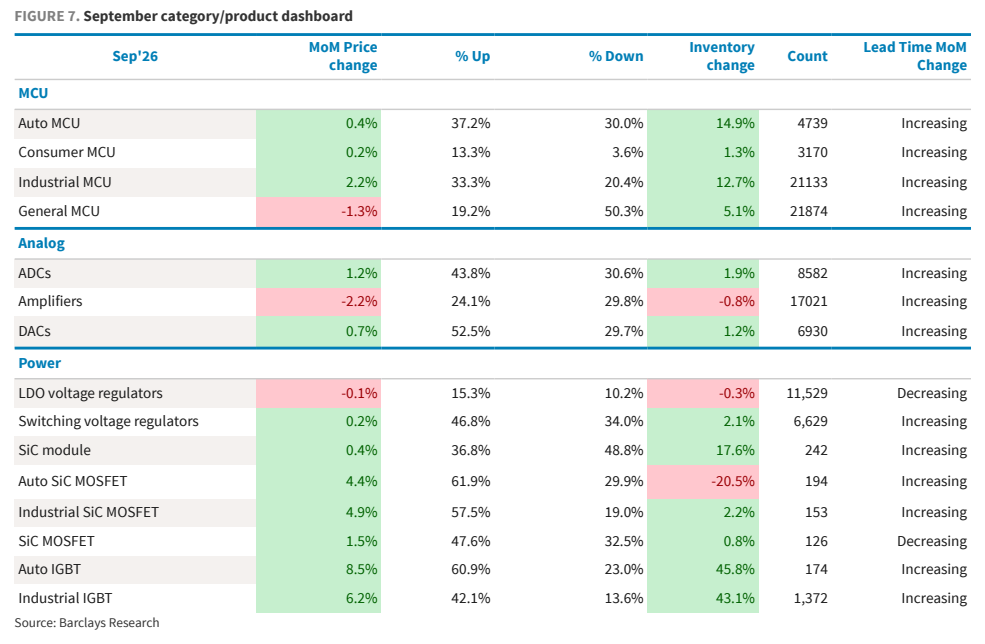
Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8

Exhibit 9
