Goldman Sachs: Shanghai Jinjiang Int'l Hotels (600754) 1Q26 Results Inline — RevPar Improved as Guided but Hotel Adds Lagged Peers; Sell
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
RevPar improved 3% YoY, driven primarily by higher average daily rates, while occupancy remained largely flat. Same-store RevPar grew 2%, below the industry average of 4%. Gross margin edged up 0.5 percentage points to 35%, though rising expense ratios partially offset profit growth. Operating cash flow increased 10% YoY to RMB 800 million, with capital expenditure remaining elevated.
The company net-added 50 hotels in 1Q26, compared with 100–150 for major peers, underscoring a significant lag in expansion. Management guided 300 net new hotels for full-year 2026, but Goldman considers this target difficult to achieve.
Outlook
Persistent underperformance in hotel additions relative to peers could lead to further market share erosion and potential downward earnings revisions. Key risks include faster-than-expected RevPar recovery, accelerated expansion, and intensifying industry competition.
Recommended Securities
- Shanghai Jinjiang International Hotels (600754): Sell; target price RMB 24. Rationale: slow expansion pace and elevated valuation.
Key exhibits
Exhibit 1
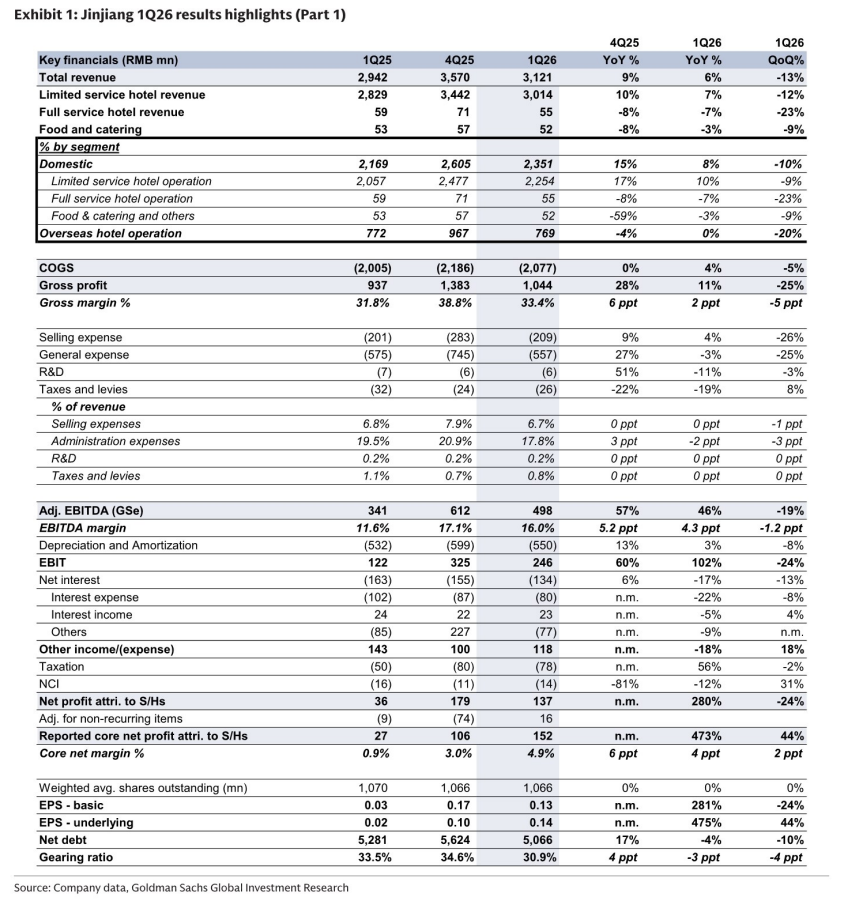
Exhibit 2

Exhibit 3
