Deutsche Bank: Tencent (0700.HK) Steady Progress in AI Development Powers Future Growth
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Deutsche Bank maintains a Buy rating on Tencent Holdings (0700.HK) with a target price of HKD 550, representing a 20% upside from the current share price of approximately HKD 458. The investment thesis centers on Tencent's steady AI advancements driving sustainable, long-term growth across its core ecosystem.
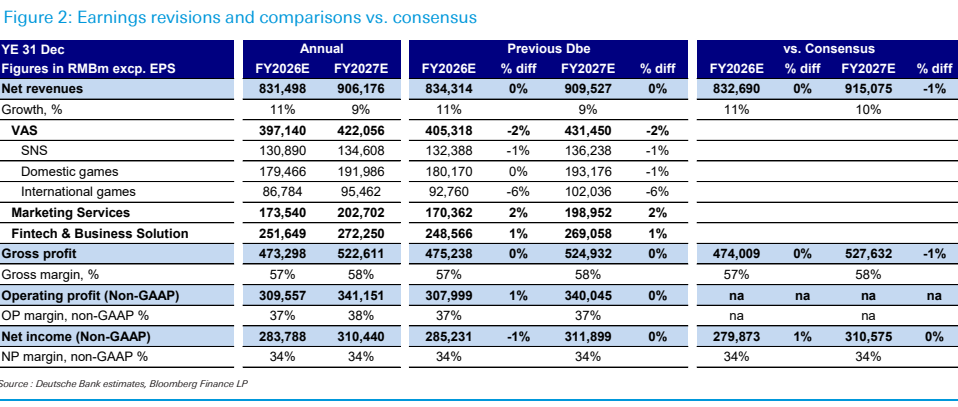
Tencent has fully integrated AI into its primary operations. AI-driven targeting has lifted advertising click-through rates by 20%, while AI-generated content has reduced gaming development costs by 15%. In Q1 2026, revenue grew 8% year-over-year to 160 billion yuan and net income surged 15% to 450 billion yuan, both exceeding market expectations. AI-related revenue, spanning cloud services and advertising tools, is projected to contribute 10% of total 2026 revenue, around 640 billion yuan.
Cloud services are benefiting massively from AI demand, with Q1 revenue jumping 25% year-over-year as AI cloud services increased their mix to 30%. Management plans to expand 2026 capital expenditure by 30% to 80 billion yuan, predominantly funding AI infrastructure. Within the WeChat ecosystem, the AI assistant has surpassed 200 million users, boosting mini-program transaction values by 40%.
Tencent repurchased roughly 20 billion HKD in shares during 2026. At 25x earnings, the valuation remains attractive below its 30x historical average.
Key exhibits
Exhibit 1