Nomura: Analysis of China's Q2 GDP by Sector
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
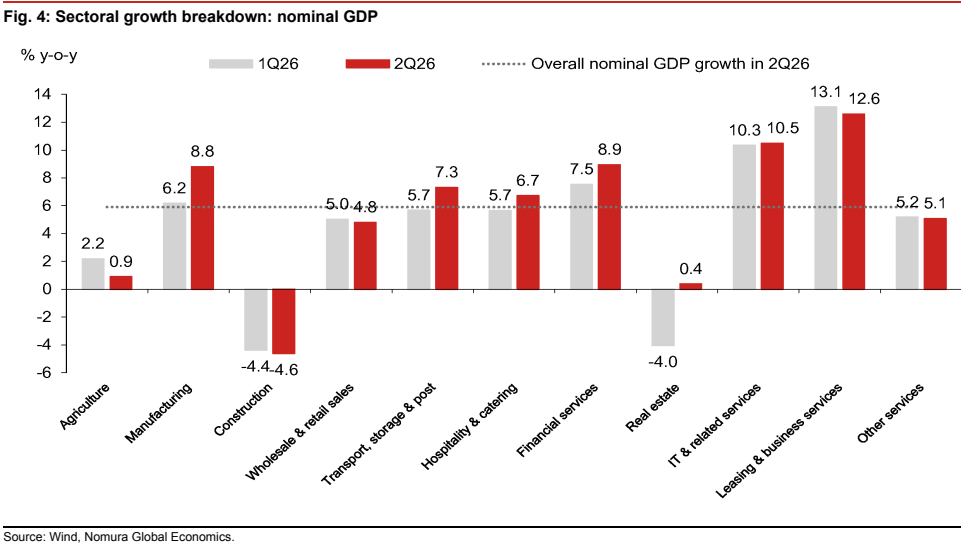
Nominal-real growth divergences stem largely from price effects; the manufacturing deflator swung from -0.1% to 1.4%. Dollar-denominated nominal export growth reached 20.2%, though largely price-driven. Financial services real growth hit 6.9%, the highest since Q1 2016, contributing 0.66 percentage points to nominal GDP. However, this contrasts with slowing credit growth—aggregate financing and RMB loans decelerated to 7.4% and 5.2% respectively—while bank net interest margins fell to a record low of 1.40%.
Real estate and construction combined real growth worsened to -2.3%. Goods consumption weakened further, with monthly average retail growth falling to 0.0%.
Outlook
Nomura expects the mid-year Politburo meeting to announce new support measures, though likely modest in scale. Bank profitability may remain pressured through Q2 2026 due to slowing credit and deteriorating margins. Nomura questions the consistency of investment data, noting infrastructure and property investment fell sharply while combined nominal GDP for construction and real estate improved.
Recommended Securities
No specific securities, ratings, or target prices were provided.
Key exhibits
Exhibit 1