Bernstein China Autos: The Second Shoe Has Dropped — Export VAT Rebate Cut Confirmed; Is a Clearing Event Imminent?
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Abstract
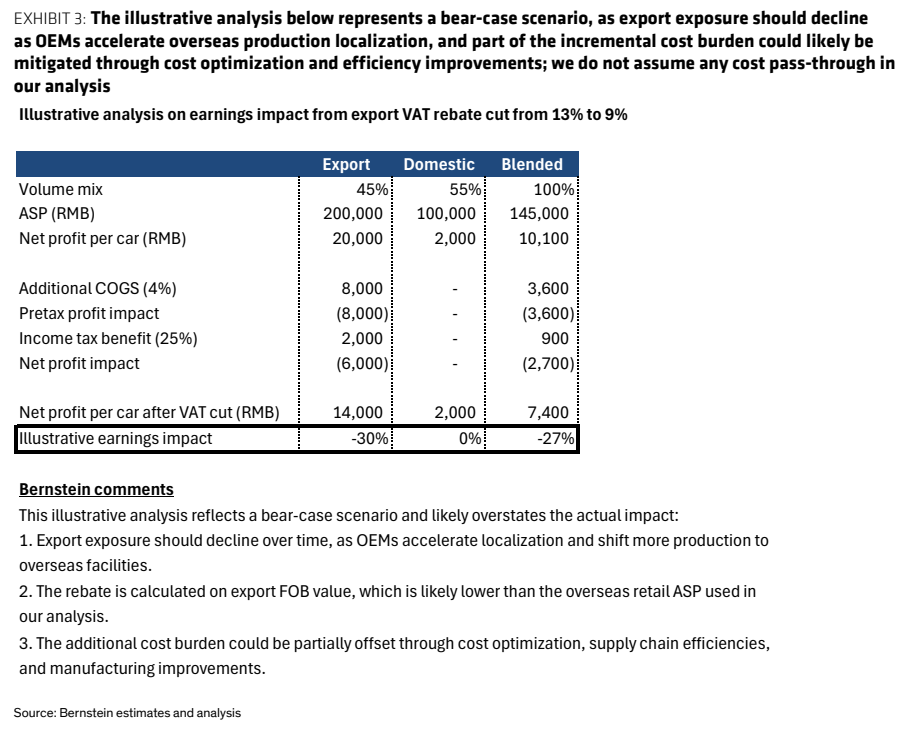
China's Ministry of Finance and State Taxation Administration will cut the export VAT rebate on new-energy vehicles (BEVs and PHEVs) from 13% to 9%, effective April 1, 2027. Bernstein argues that, given intense competition, OEMs are unlikely to raise prices materially and will largely absorb the 4-percentage-point cost through margin compression near term. With China–EU trade talks reaching consensus, the sector's two big policy overhangs have largely cleared and the market is approaching a clearing event. BYD has the highest export exposure at roughly 45% of sales overseas, followed by Chery (36%), SAIC (27%), and Geely and Leapmotor (24% each); localized production in Thailand, Brazil and Hungary (ramping by end-2026) should cut BYD's effective exposure below 40%. Phased rebate cuts previously applied to batteries, solar and aluminum/copper products suggest further NEV reductions are possible. BYD holds roughly 950k units of potential overseas capacity by 2027—about 40% of its 2.5 million-unit overseas sales target. With the sales base improving from December 2026, a full reset in Q1 2027 and low valuations, Bernstein favors gradual accumulation. BYD (1211.HK/002594.CH) is Outperform at HK$130.00/RMB114.00; Geely (175.HK) and Xiaomi (1810.HK) are Outperform at HK$25.00 and HK$35.00; Great Wall (2333.HK), GAC (2238.HK), Li Auto (LI/2015.HK), NIO (NIO/9866.HK), SAIC (600104.CH) and XPeng (9868.HK/XPEV) are Market-Perform.
Key exhibits
Exhibit 1