Goldman Sachs | Orion180 Insurance Group (OIG): Differentiated Homeowners Writer with Significant Growth Opportunities; Initiate at Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs initiated coverage of Orion180 Insurance Group (OIG) with a Buy rating and a twelve-month target price of $13.00, implying 47% total return potential. OIG is an asset-light insurer focused on the US excess & surplus (E&S) homeowners market, ranked second by scale, leveraging its My180 technology platform and a distinctive MGA model to earn fee income while retaining some underwriting risk. Goldman expects managed premiums to compound at 44% over 2025-2028 and adjusted EBITDA at roughly 50%, with the adjusted EBITDA margin expanding 19 percentage points to 53.8% by 2028, helped by share gains in large E&S states—California, Florida and Texas. Around 85% of 2025 direct written premium comes from the Gulf/US Southeast. The Services unit contributes about 70% of revenue before eliminations, and the fronting carrier held roughly $75 million of statutory capital and surplus at end-2025 with an RBC ratio of 388%. Goldman forecasts a 41% adjusted EBITDA CAGR over 2026-2028 and about $50 million of capital injections into insurance subsidiaries over the next three years, including roughly $10 million in 2026.
Key exhibits
Exhibit 1

Exhibit 2
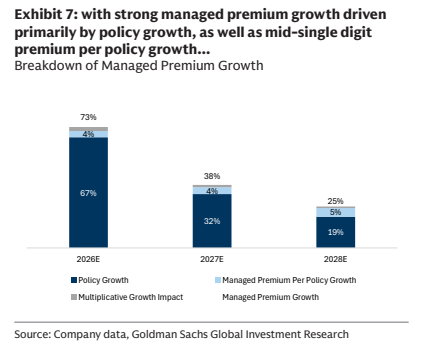
Exhibit 3
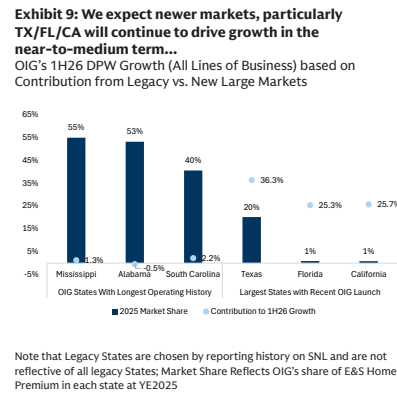
Exhibit 4

Exhibit 5
Exhibit 6
Exhibit 7
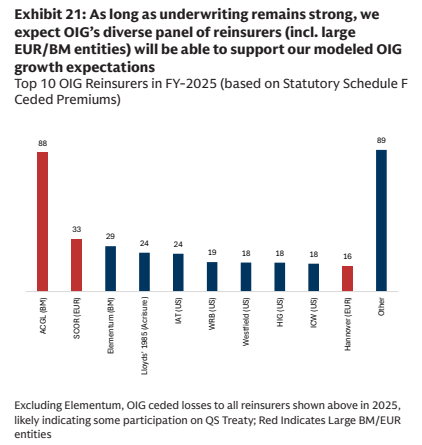
Exhibit 8
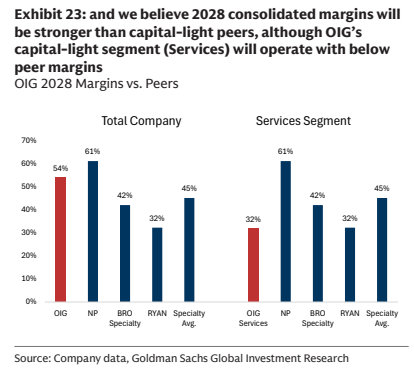
Exhibit 9
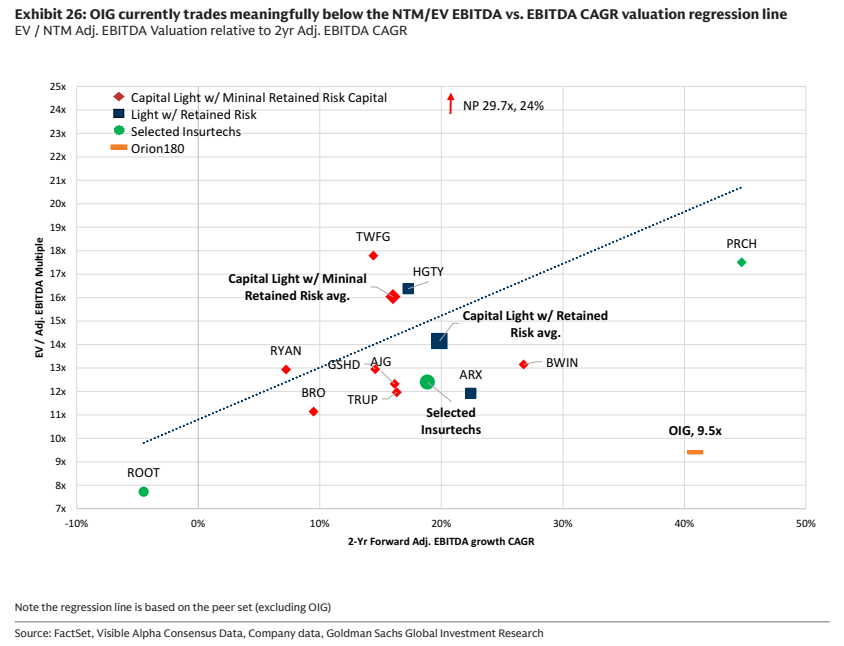
Exhibit 10
