Bernstein McCormick & Co (MKC.US) 2Q26: A Tale of Two Segments — Reasons for Optimism, but Deal Overhang Persists
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Bernstein updated coverage on McCormick (MKC) following its Q2 2026 results, highlighting a divergent performance across two business segments. The Flavor Solutions division continues to deliver strong growth, while the Consumer segment remains soft but shows signs of potential recovery. The firm maintains an Outperform rating with a target price of USD 90, based on a 30-times multiple applied to 2027 adjusted EPS of USD 3.00.
Q2 adjusted EPS came in at USD 0.68, exceeding both Bernstein's estimate of USD 0.65 and market consensus of USD 0.66. Total revenue declined 1% year-over-year to USD 1.62 billion. However, Flavor Solutions grew 4% to USD 850 million, marking its eighth consecutive quarter of expansion, while Consumer revenue fell 5% to USD 770 million due to North American retail destocking and reduced promotional activity.
Gross margin expanded 120 basis points to 38.5%, reflecting cost improvements and favorable product mix. Management reaffirmed full-year adjusted EPS guidance of USD 2.80–2.90, implying roughly 10% second-half growth. Bernstein views the current valuation at approximately 26 times 2027 earnings as attractive relative to historical averages, offering a margin of safety. However, deal overhang concerns, including potential acquisitions or divestitures, are expected to continue weighing on the share price. Key risks include slower-than-anticipated Consumer recovery, raw material cost inflation, and ongoing transaction uncertainty.
Key exhibits
Exhibit 1

Exhibit 2

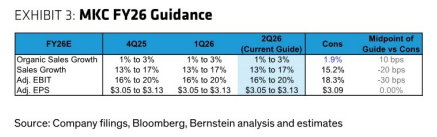
Exhibit 3