Deutsche Bank: Microsoft (MSFT.US) — Margins and Returns Under the Microscope: Azure Edition
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Deutsche Bank provides an in-depth analysis of Microsoft Azure's profitability and capital return trajectory, highlighting that while Azure revenue growth remains above 30%, surging capital expenditure is pressuring free cash flow returns. Capital expenditure is projected to exceed $60 billion in fiscal year 2025, driving the capital intensity ratio from 18% of revenue in fiscal year 2023 to 25% in fiscal year 2025. Free cash flow returns correspondingly declined from 3.5% to 2.8%.
However, Deutsche Bank anticipates margin recovery starting in fiscal year 2026 as AI infrastructure investments mature. Data center utilization, currently around 70%, is expected to improve to 85% in fiscal year 2026. Operating margins may dip to 42% in fiscal year 2025 before rebounding to 44% in fiscal year 2026, as depreciation expense growth lags the capital expenditure cycle by approximately two years.
AI-related revenue contribution is growing significantly, rising from 5% of Azure revenue in fiscal year 2024 to 12% in fiscal year 2025. The competitive landscape remains intense, with AWS and Google Cloud accelerating AI investments, though Microsoft's OpenAI partnership provides meaningful differentiation.
Customer contract durations are lengthening, with deferred revenue growing 20%, enhancing forward revenue visibility. Deutsche Bank maintains a Buy rating on Microsoft without specifying a target price, citing anticipated Azure margin improvement and accelerating AI revenue growth.
Key exhibits
Exhibit 1
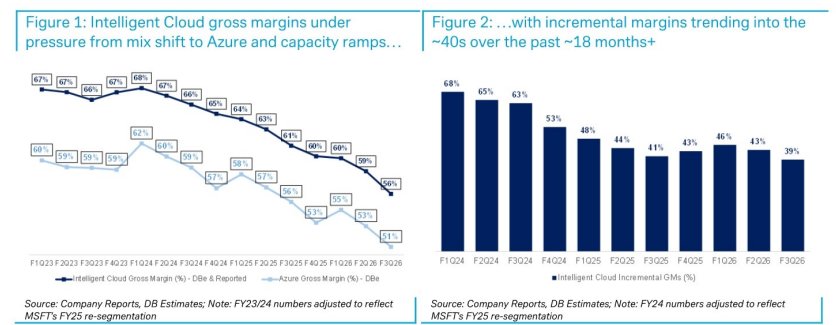
Exhibit 2
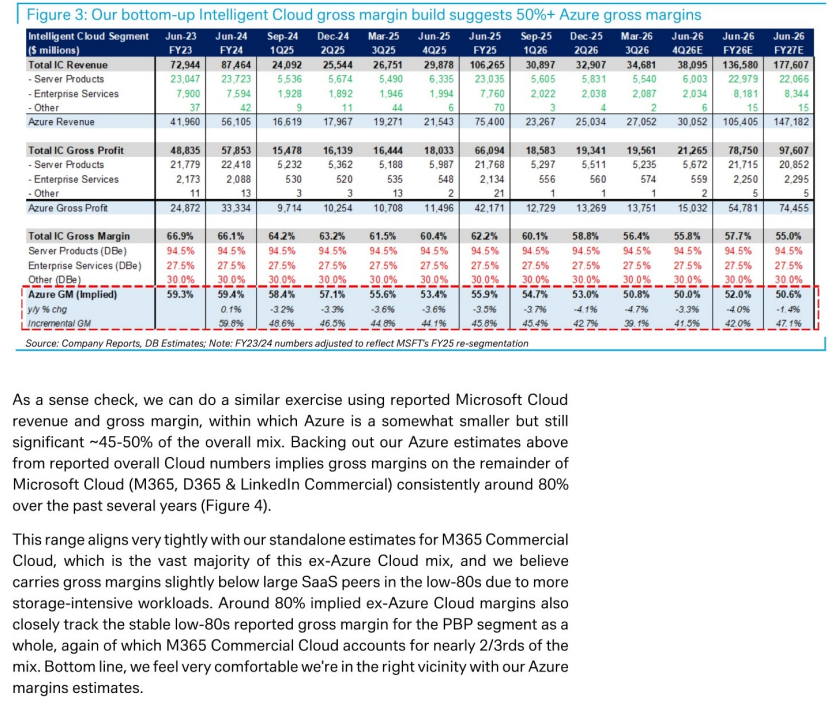
Exhibit 3
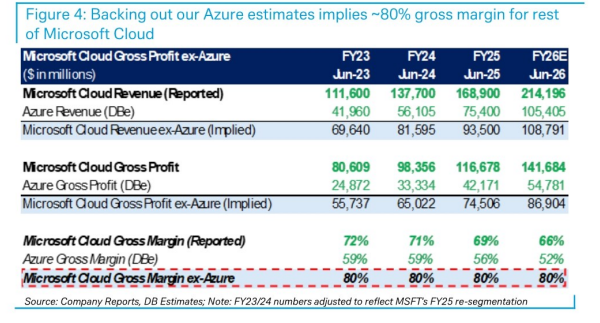
Exhibit 4
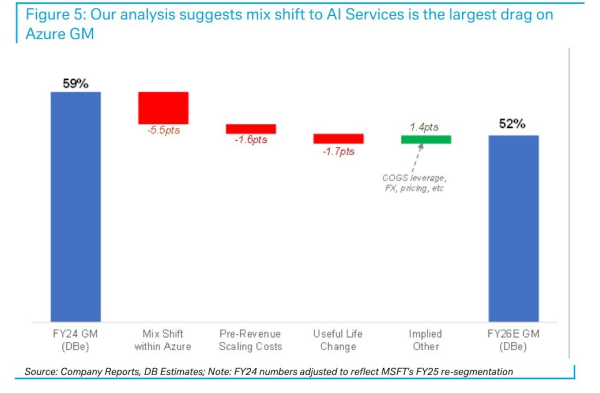
Exhibit 5
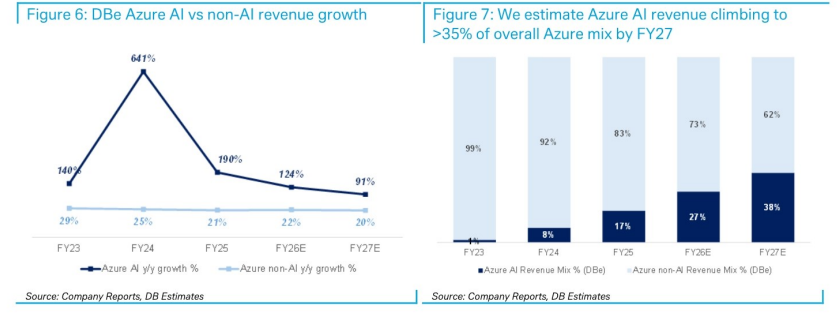
Exhibit 6
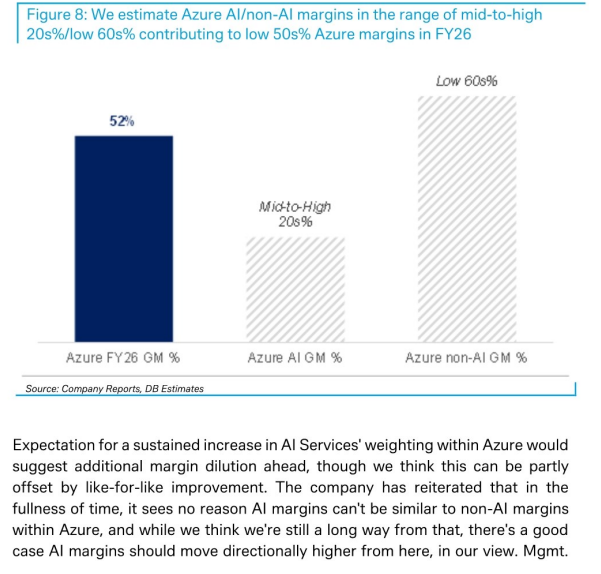
Exhibit 7
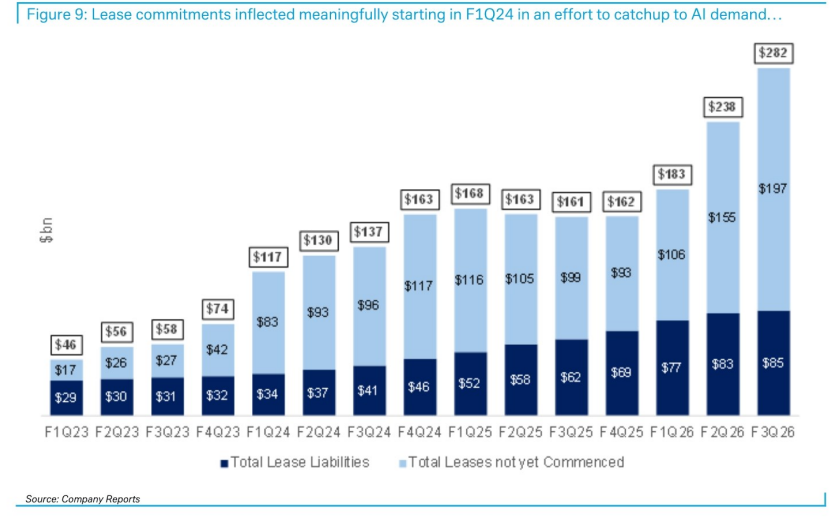
Exhibit 8
