BofA India Oil & Gas 2Q Preview: OMCs Return to Profit; E&P and Gas Midstream Normalize
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Abstract
BofA previews fiscal 2Q26 results for India's oil and gas sector. Oil marketing companies (OMCs) are expected to swing back to profit as auto fuel and LPG marketing losses narrow, helped by the special additional excise duty on exports (SAED), the full-quarter impact of retail price increases, and Brent falling quarter-on-quarter from $104/bbl to $96/bbl.
Upstream earnings should soften on lower realizations: ONGC standalone EBITDA is seen down 8% q/q to INR 261bn, while Oil India falls 6% q/q to INR 38bn despite 5% oil and 12% gas volume growth. Gas midstream normalizes from a high base, with GAIL EBITDA down 23% q/q to INR 49bn on weaker gas trading and marketing margins and lower LPG and other hydrocarbon earnings. City gas distributors MGL and IGL should post 6-7% y/y volume growth, up about 3% q/q, with margin performance diverging. Brent's sharp quarter-end rise on renewed US-Iran conflict could bring inventory gains. Preferred names: BPCL (INR 255, 1.2x FY28 P/B), GAIL (INR 205, SOTP), HPCL (INR 290, 1x FY28 P/B) and Petronet LNG (INR 285, DCF).
Key exhibits
Exhibit 1
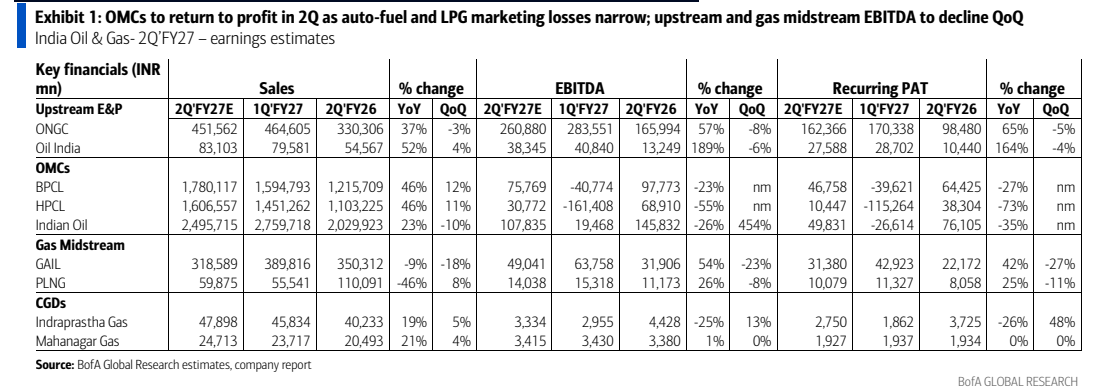
Exhibit 2
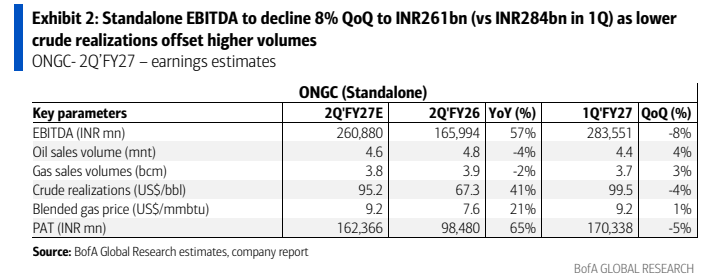
Exhibit 3

Exhibit 4
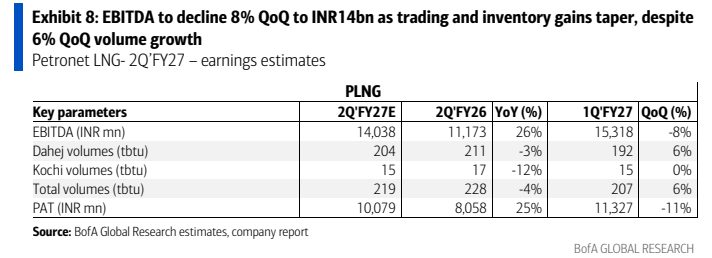
Exhibit 5

Exhibit 6

Exhibit 7
