HSBC SG Micro (300661) Upgrade to Buy: Expanding Beyond the Analog Recovery
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
HSBC has upgraded SG Micro (300661) from Hold to Buy, raising the target price based on the view that the company is successfully expanding beyond a mere cyclical analog chip recovery into a sustained structural growth phase. The upgrade follows impressive first-quarter 2026 results, where revenue exceeded HSBC's expectations, driven by robust momentum in new product lines such as power management ICs and signal chain chips, alongside ongoing market share gains.
The report highlights a notable gross margin improvement from the fourth quarter of 2025 to the first quarter of 2026, largely attributed to favorable product mix optimization. Furthermore, SG Micro is capitalizing on the accelerating domestic substitution trend within the Chinese semiconductor landscape. The company has effectively diversified its client base, expanding its footprint from consumer electronics into the industrial and automotive sectors, with automotive revenue contributing a growing percentage of total sales.
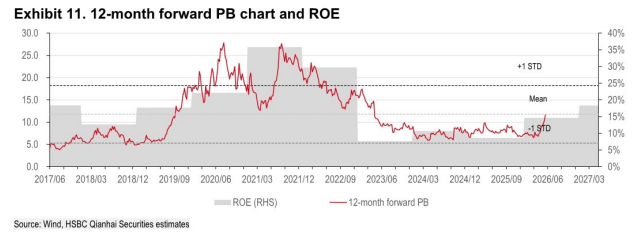
HSBC anticipates that the firm will significantly outpace the industry average revenue compound annual growth rate between 2026 and 2028. The revised target price is anchored on an elevated forward earnings multiple for 2027, reflecting increased confidence in long-term profitability. Key downside risks to this constructive thesis include softer-than-expected downstream demand recovery in the consumer segment and intensifying pricing competition.
Key exhibits
Exhibit 1
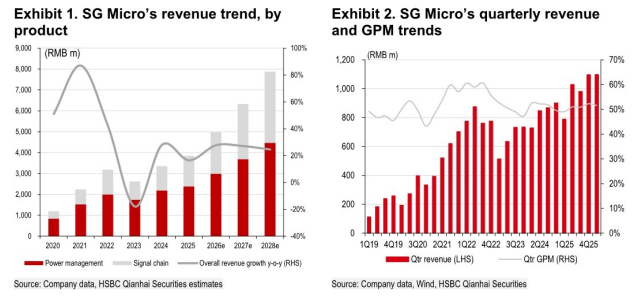
Exhibit 2
Exhibit 3
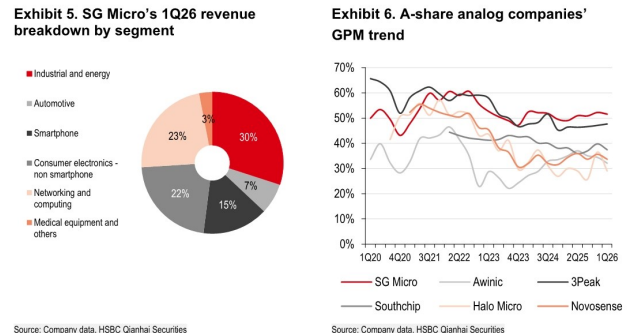
Exhibit 4
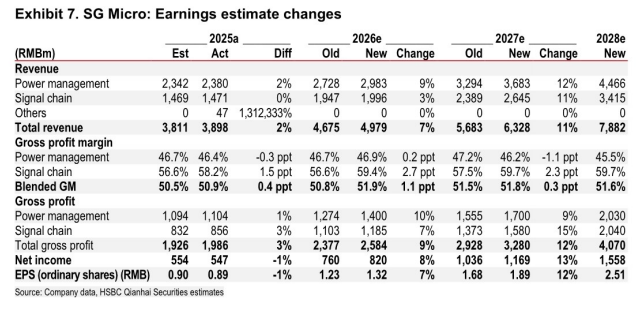
Exhibit 5
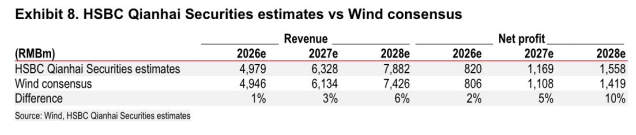
Exhibit 6
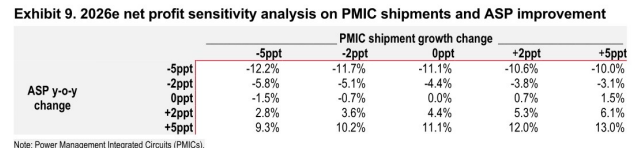
Exhibit 7
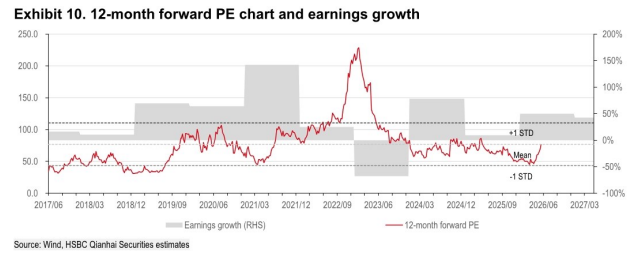
Exhibit 8