UBS: Regulatory Risks, Asset-Light Model, and Strong Revenue Growth — Momenta Initiation
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
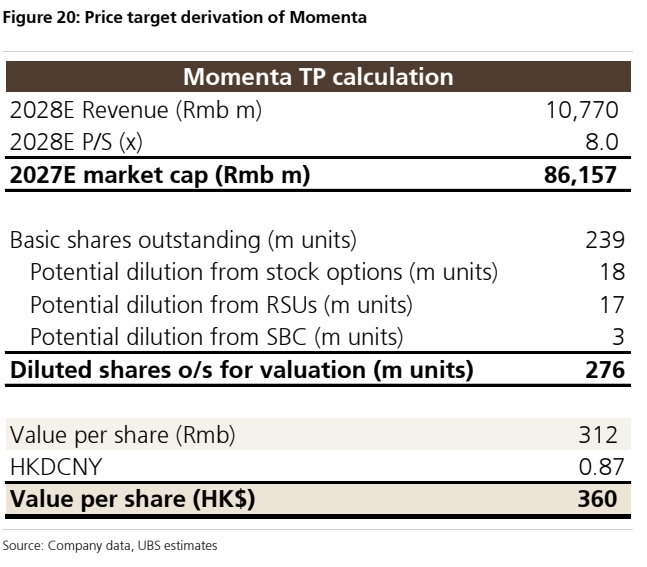
UBS expects annual installations to surge from 51,000 in 2025 to 2.5 million by 2028, raising Momenta's share of China's annual passenger vehicle sales from under 2% to 10%. Revenue is projected to grow at roughly a 50% CAGR over 2025–30E, reaching RMB 10,770 million by 2028E, with EBIT turning positive at RMB 986 million. Of the 510,000 vehicles delivered in 2025, BYD contributed approximately 250,000 and SAIC Motor over 100,000.
Outlook
The high-level ADAS TAM could reach approximately US$142bn by 2030. China's robotaxi market may hit US$183bn by the late 2030s, with the global ex-US market at US$394bn. Key risks include competition from Huawei, Horizon Robotics, and DJI, automaker pricing pressure, rising storage chip costs (up over 3x year-on-year as of Q2 2026), and geopolitical or regulatory constraints.
Recommended Securities
- Momenta (6880.HK): Buy, Target HK$360.00
Key exhibits
Exhibit 1
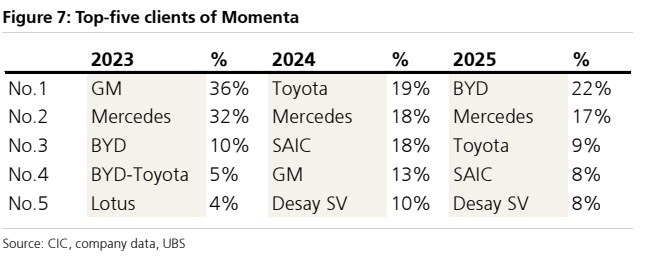
Exhibit 2
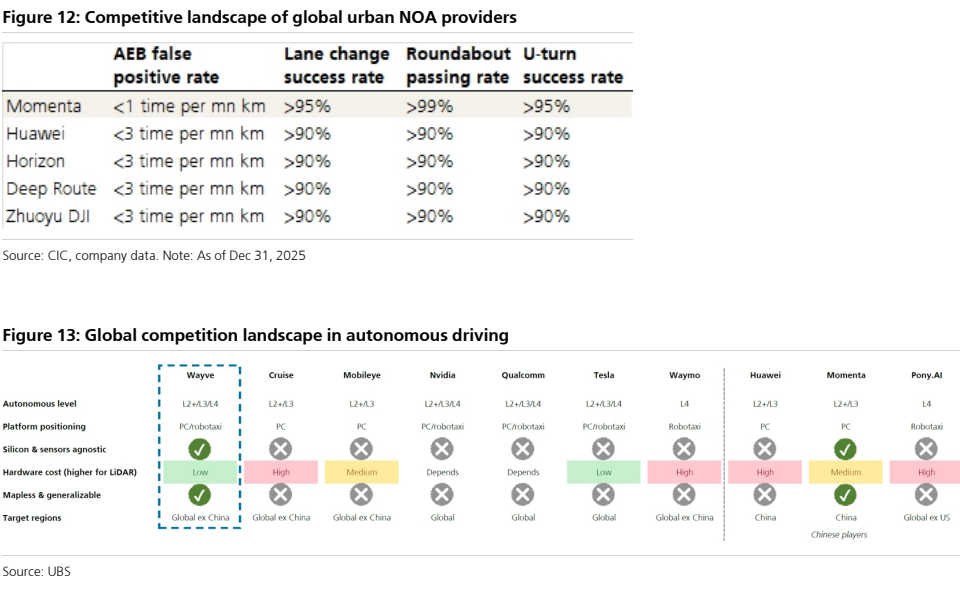
Exhibit 3
Exhibit 4