UBS Broadcom Inc. (AVGO) FQ2 26 (Apr) Preview: Raising Target Price, Adjusting Estimates
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Ahead of Broadcom's FQ2 26 (April) earnings release scheduled for June, UBS has updated its estimates and raised the target price to $220, while maintaining a Buy rating on the stock.
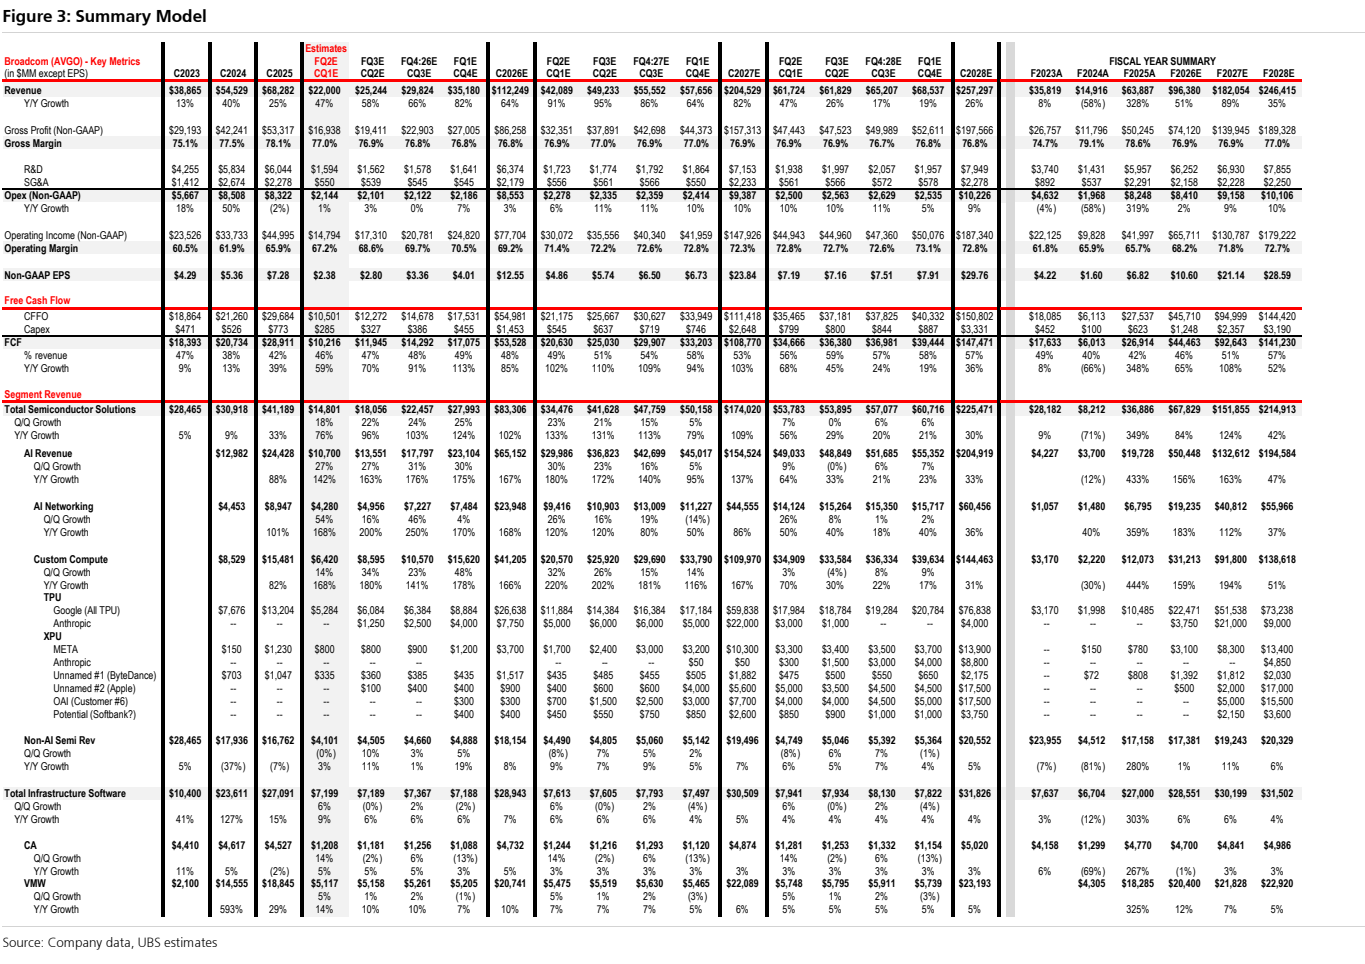
UBS expects FQ2 26 revenue to reach approximately $13 billion, representing 25% year-over-year growth. This expansion is primarily driven by robust demand for AI networking equipment and custom AI silicon (TPUs). Consequently, the firm anticipates that AI-related revenue will increase from 35% to 40% of total sales. Meanwhile, non-AI businesses, such as broadband and storage, are projected to bottom out during the quarter before gradually recovering in the second half of the fiscal year.
The integration of VMware is progressing smoothly. Management expects this segment to contribute $2 billion in revenue for FY26, boasting margins that exceed the corporate average. These positive dynamics have prompted UBS to adjust its full-year EPS forecast upward to $5.20 from $5.00, reflecting anticipated improvements in gross margins and disciplined operational expense control. Free cash flow is projected at $4.5 billion against sustained capital expenditures of $1 billion. The target price of $220 is derived by applying a 42x price-to-earnings multiple, aligning with historical averages.
Key downside risks include a potential slowdown in AI capital expenditures, integration hurdles with VMware, and unforeseen inventory adjustments.
Key exhibits
Exhibit 1