Deutsche Bank: NetEase (9999.HK) Key Releases to Propel 2H Growth
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
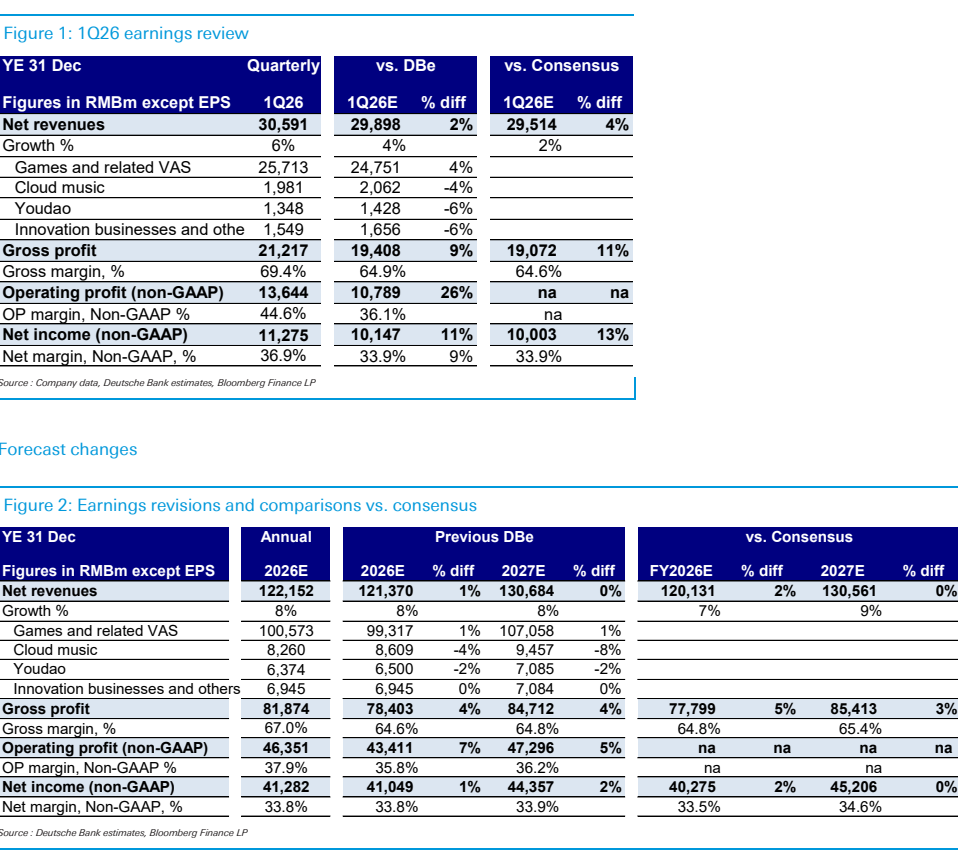
Deutsche Bank maintains a Buy rating on NetEase (9999.HK) with a price target of HK$200, asserting that a pipeline of key game releases will significantly accelerate growth in the second half of 2026. The bank projects revenue growth of 5% year-over-year in the second quarter, expected to accelerate sharply to 15% by the third quarter.
First-quarter performance established a solid foundation, with total revenue growing 7% year-over-year. Gaming revenue specifically increased 9%, driven by a 12% expansion in PC games and an 8% rise in mobile games. Existing popular titles, including Fantasy Westward Journey and Justice Mobile, continue to demonstrate remarkable stability and user retention.
Looking forward, the anticipated launches of major titles like Where Winds Meet in the third quarter and Marvel Rivals in the fourth quarter are poised to deliver substantial incremental revenue. Alongside top-line growth, operating margins within the gaming segment are projected to improve from 25% in the first quarter to 27% in the second half, driven by better operating leverage and monetization efficiencies.
NetEase currently trades at an attractive valuation of approximately 15 times earnings, below its historical average. This compelling valuation, combined with a robust release schedule and expanding profitability, supports the bank's positive thesis. Primary downside risks include the underperformance of newly launched games and unpredictable shifts in the domestic regulatory landscape for the gaming sector.
Key exhibits
Exhibit 1