Morgan Stanley: Kingsoft Office Software Holding Discount Narrows
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
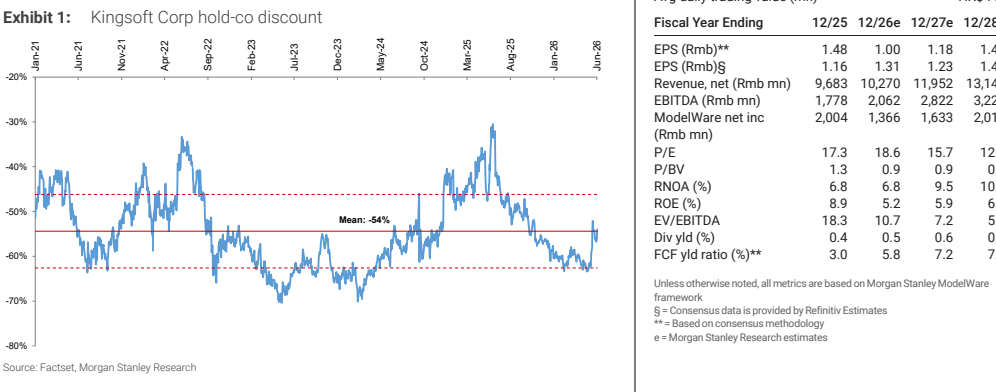
Morgan Stanley notes that the holding company discount for Kingsoft Software (3888.HK) has narrowed since late May, approaching its historical average of approximately 54%. The primary catalyst is Chairman and largest shareholder Lei Jun increasing his stake. His ownership rose from 22.2% on May 28 to 26.18% on June 25, representing a total inflow of roughly HKD 644 million. Morgan Stanley maintains an Equal-weight rating on Kingsoft Software with a target price of HKD 28.00. This target implies a 31% upside potential compared to the closing price of HKD 21.38 recorded on June 26. The firm's industry view remains In-Line. The valuation methodology employs a sum-of-the-parts approach. This includes applying a 10x 2026 price-to-earnings ratio to the online gaming business and utilizing a discounted cash flow model for WPS, assuming a 9.8% weighted average cost of capital and a 3% terminal growth rate. Kingsoft Cloud is calculated based on its current market capitalization and Kingsoft's 32.9% stake. The model assumes a holding discount of 45% and a USD/CNY exchange rate of 7.00. For the years 2026 to 2028, the EPS forecasts stand at RMB 1.00, RMB 1.18, and RMB 1.44, respectively, alongside corresponding revenue forecasts of RMB 10.27 billion, RMB 11.95 billion, and RMB 13.15 billion. EBITDA projections are RMB 2.06 billion, RMB 2.82 billion, and RMB 3.22 billion. Key downside risks include slower domestic procurement progress and a failure to improve WPS monetization rates.
Key exhibits
Exhibit 1