Goldman Sachs on Australia Metals and Mining: Lithium Sector Returns to Growth as Price Outlook Softens; September Quarter Preview; Buy IGO, Sell PLS
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
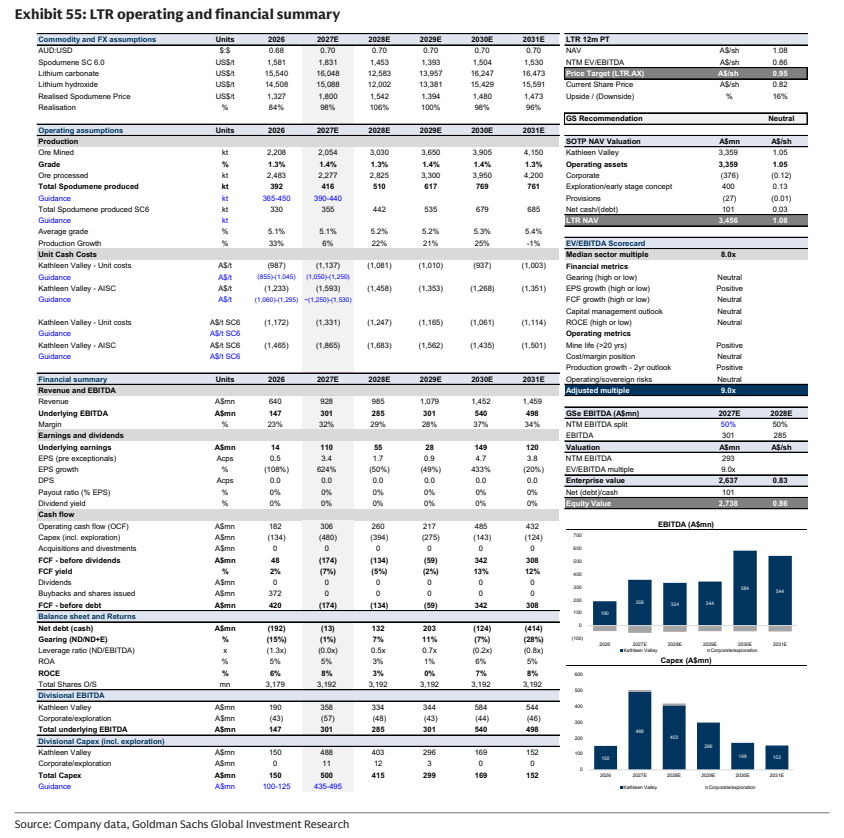
Goldman Sachs folds its latest global lithium supply-demand update into Australian coverage: the market shifts from a 16% deficit through most of 2026 to near balance in 4Q26 and an 8-18% surplus in 2027-28E, as slowing EV/ESS base growth and fading restocking stall apparent demand while supply grows 32% in 2027E and 19% in 2028E across China, Africa and Australia. Revised carbonate prices find marginal-cost support in 2H27E before falling to the 80th percentile of the cost curve in 2028E; spodumene forecasts move -5% to +4% over CY26-30E, with the long-term price nudged up to US$1,300/t SC6. Australian spodumene supply adds over 1Mtpa SC6 (>125kt LCE) in CY27, and although most projects sit below roughly US$1,000/t SC6 on an AISC basis, FY27E growth spending pushes full-cost and FCF breakevens higher, leaving producers FCF-negative even at spot prices. The sector now prices around 0.90x NAV, though local names retain a forward premium to global peers. For the September quarter, Goldman models PLS output of 251kt (consensus 246kt) and IGO at 353kt (consensus 374kt). Goldman rates IGO Buy (A$8.10 twelve-month target, 24% upside from A$6.54), PLS Sell on P2000's >A$2.5bn capex risk, with LTR and CXO Neutral.
Key exhibits
Exhibit 1
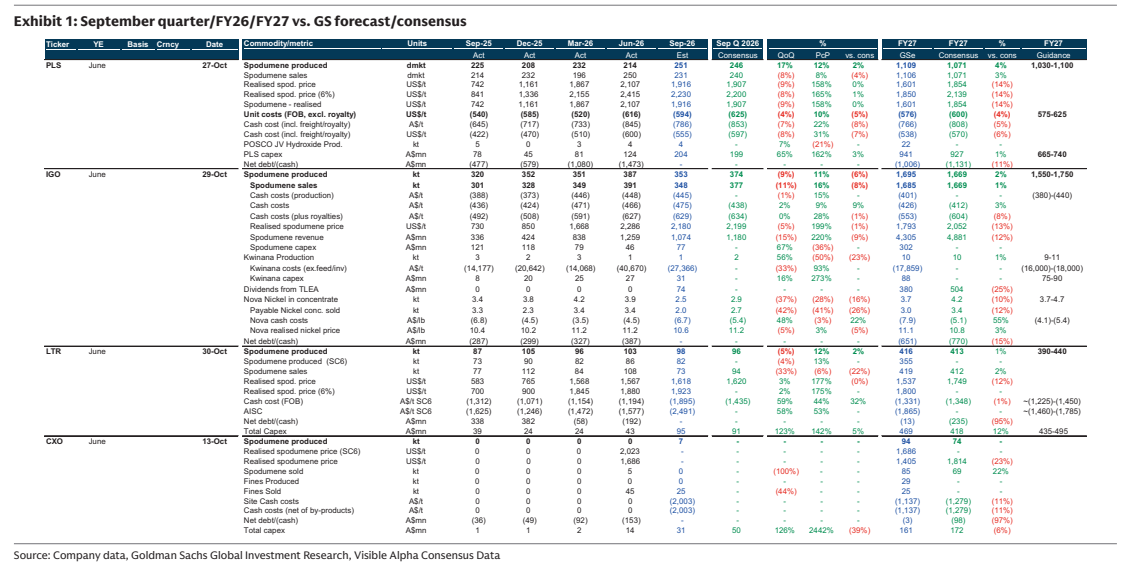
Exhibit 2
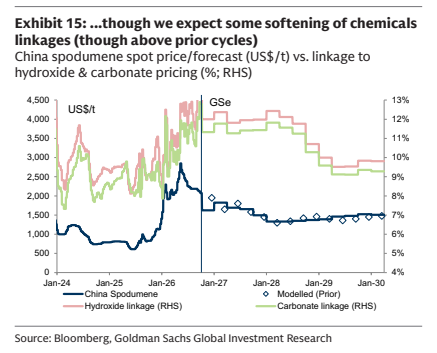
Exhibit 3
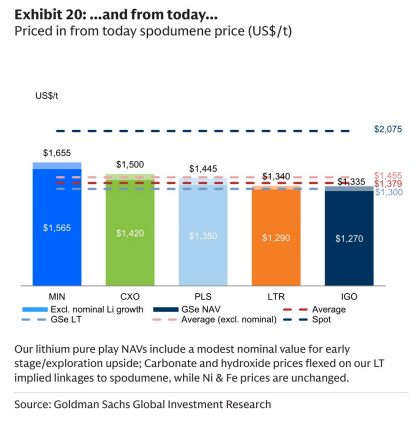
Exhibit 4
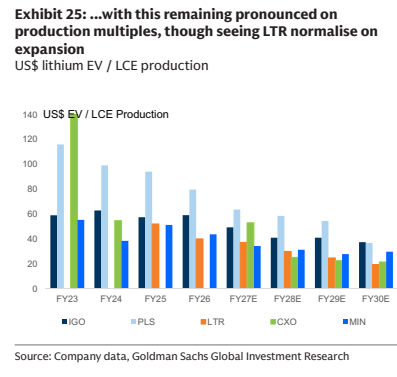
Exhibit 5
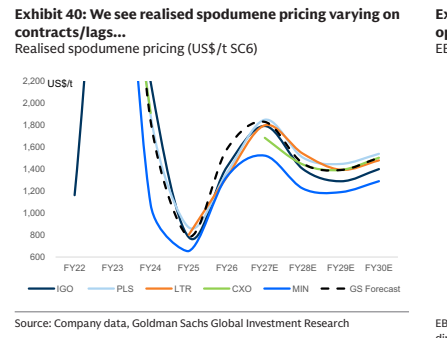
Exhibit 6
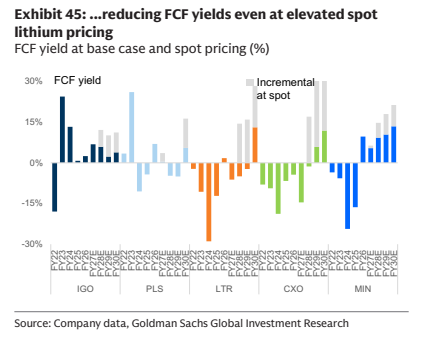
Exhibit 7
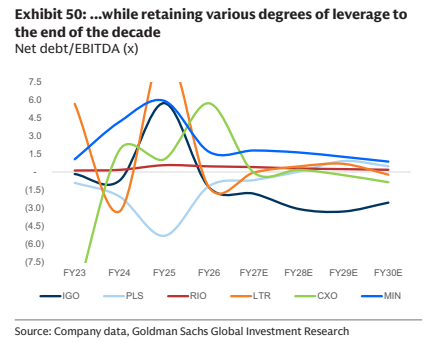
Exhibit 8