Morgan Stanley: New 20/19/18 Framework + APLD Earnings, HUT's Revolver, MARA's Matagorda, WULF's Muskie, CIFR's Extension and GLXY's Caspian
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Morgan Stanley updates its valuation framework for power shell providers (PSPs) from 15/15/15 to 20/19/18, reflecting 20-year leases, a 19% return on capex and $18 per watt of equity value creation. Despite strong AI compute demand and compelling project economics, a worse interest-rate environment has lifted discount rates, partially offsetting higher project values. The bank estimates US data centers face a 32-42GW power shortfall through 2028, making PSP assets a valuable time-to-power solution.
Target price changes: APLD raised from $37.50 to $41.00; WULF from $62.50 to $65.00; CIFR cut from $54.00 to $51.50; GLXY from $48.00 to $43.00; MARA from $11.00 to $10.00; and RIOT from $43.00 to $35.50. TeraWulf (WULF) and Galaxy Digital (GLXY) are both rated Overweight, with targets of $65 and $43, respectively. Management expects APLD to execute roughly 250MW of expansion leases by year-end. The note also covers Hut 8's revolving credit facility, MARA's Matagorda site, TeraWulf's Muskie project, and Cipher's lease extension alongside Galaxy's Caspian, underscoring that strong site quality and management capability remain decisive for success in the current environment.
Key exhibits
Exhibit 1
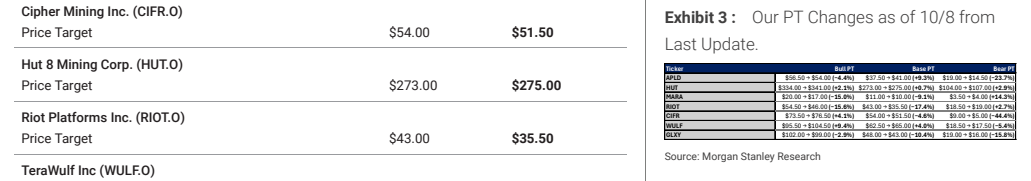
Exhibit 2
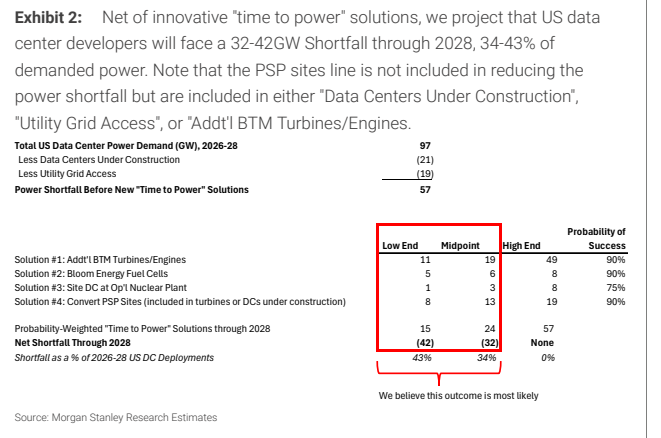
Exhibit 3
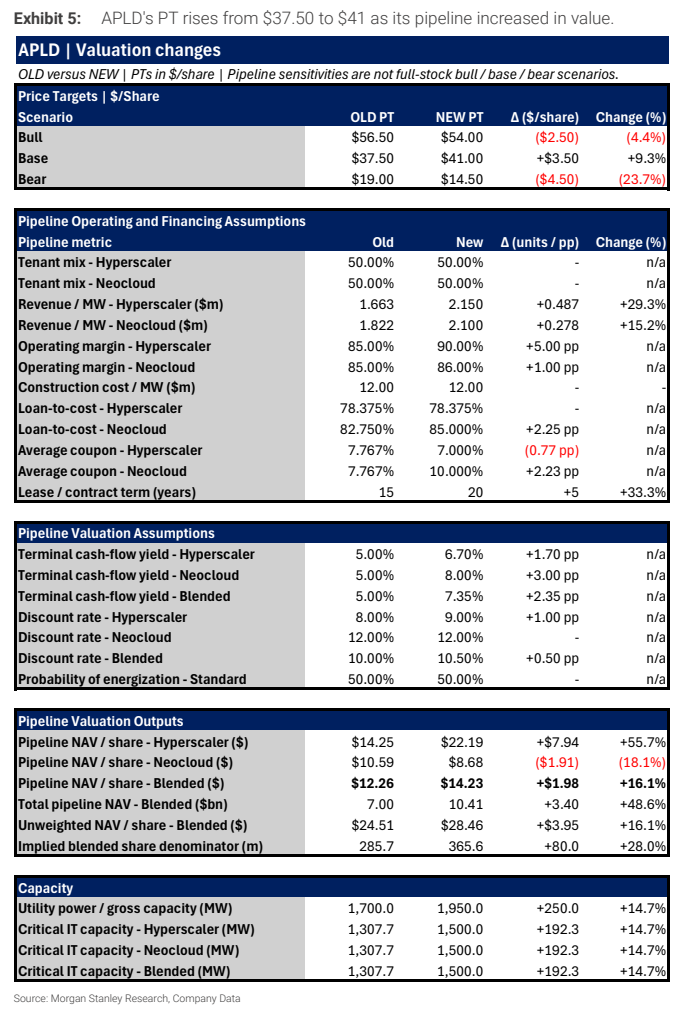
Exhibit 4
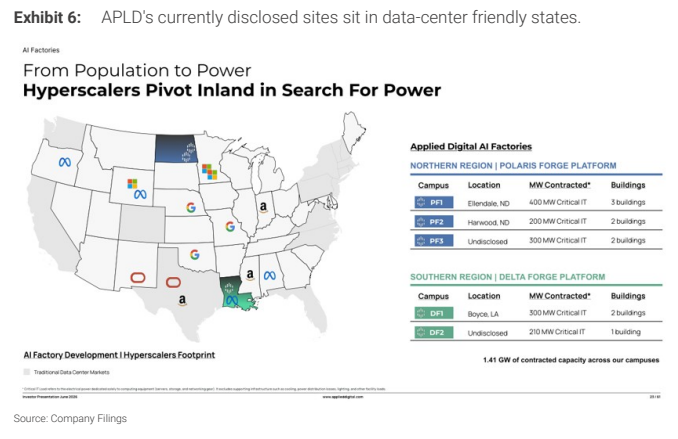
Exhibit 5
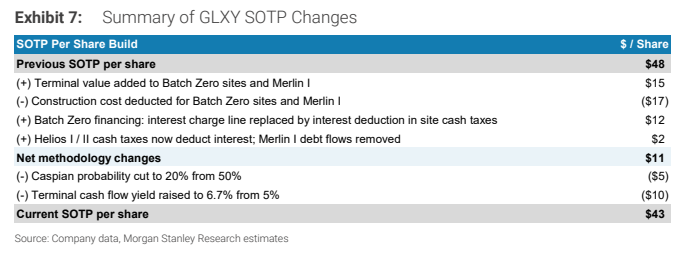
Exhibit 6