Monthly Charts: How Much Further Should Financial Conditions Tighten?
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
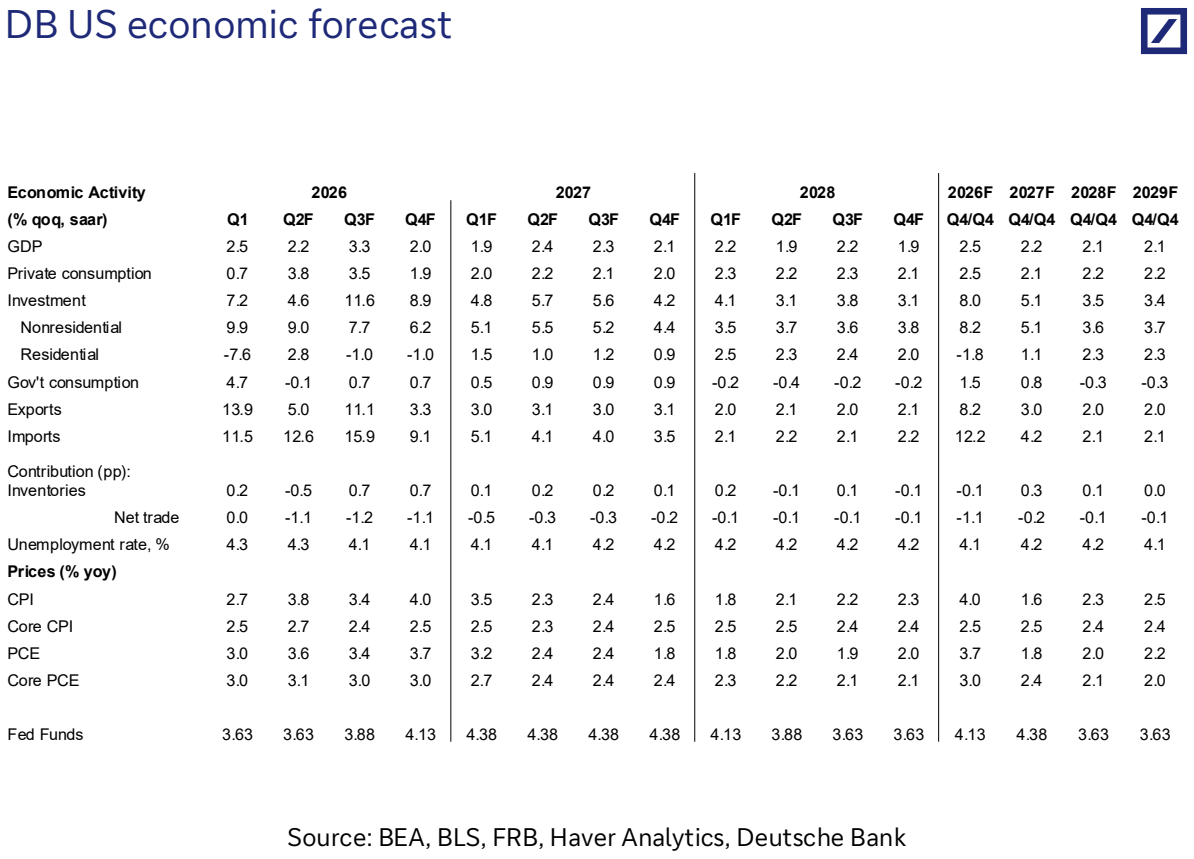
Deutsche Bank's monthly chartbook takes stock of the US labor market, inflation, Federal Reserve policy and growth momentum. The labor market remains stable — unemployment was 4.18% in September 2026 — with the bank estimating breakeven payroll growth of 40,000–50,000 per month. Disinflation remains challenging: downward revisions to core PCE exceeded expectations, demand is still the most important inflation driver, and pipeline inflation pressures stay elevated, with rent disinflation at risk of reversing within the next year. Deutsche Bank's r-star dashboard puts the real neutral rate around 1.6%.
The financial conditions index currently sits in accommodative territory, supporting US potential growth, but given the gap between the prevailing policy rate and what policy rules would suggest, the Fed may need financial conditions to tighten further. AI-related investment is expected to remain extremely high in coming years and could become the largest capex boom relative to GDP in history, a potential boost to productivity growth. The federal budget deficit remains historically high despite a healthy labor market. Betting markets put the probability of Democrats winning the House at 90% and the Senate at over 60% in the midterms.
Key exhibits
Exhibit 1
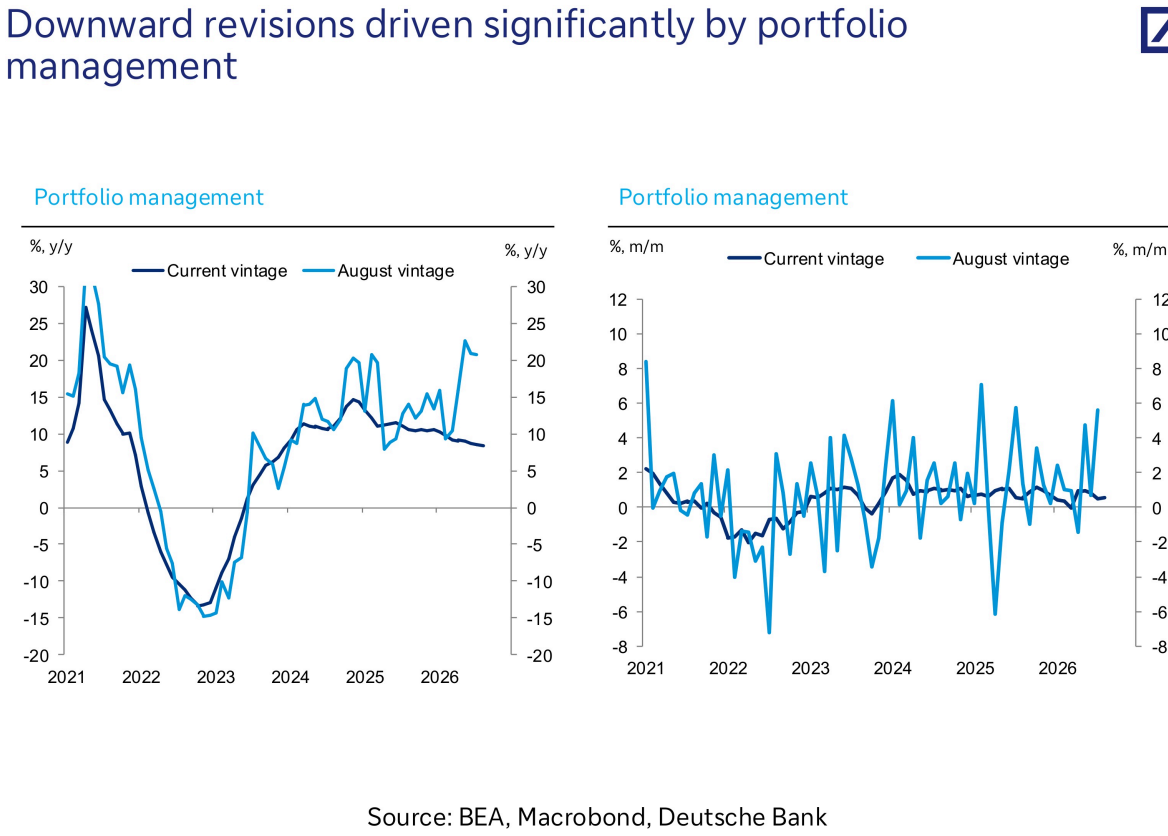
Exhibit 2
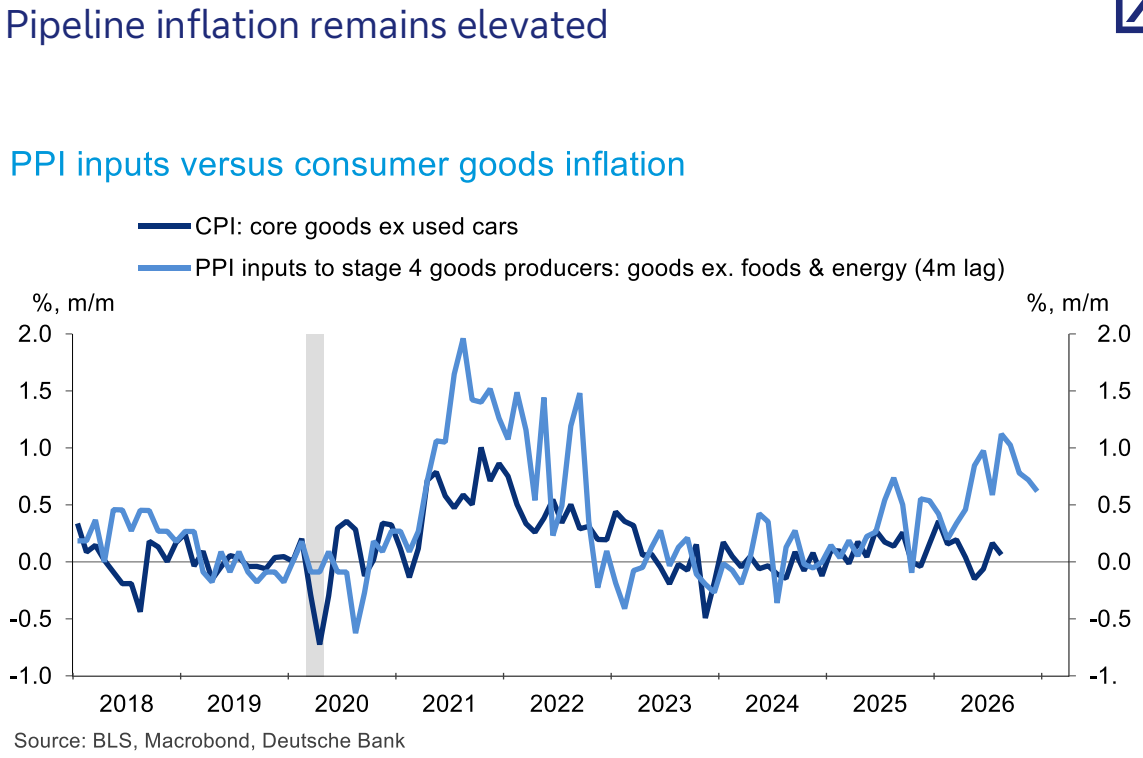
Exhibit 3
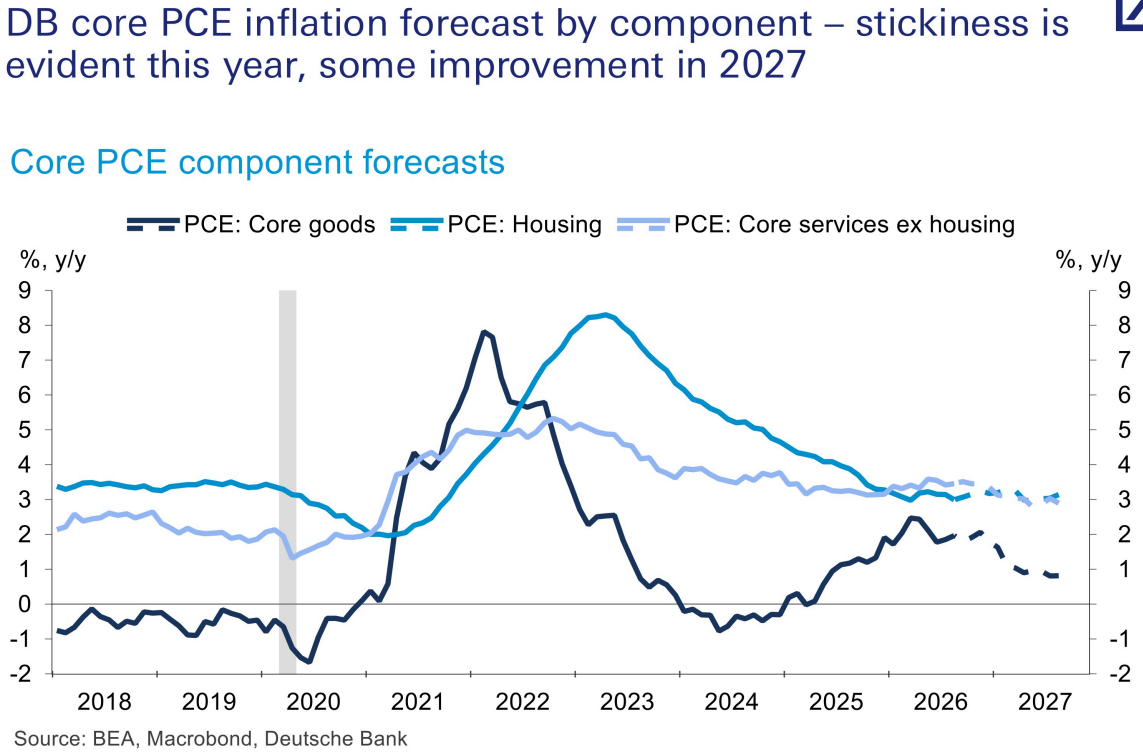
Exhibit 4
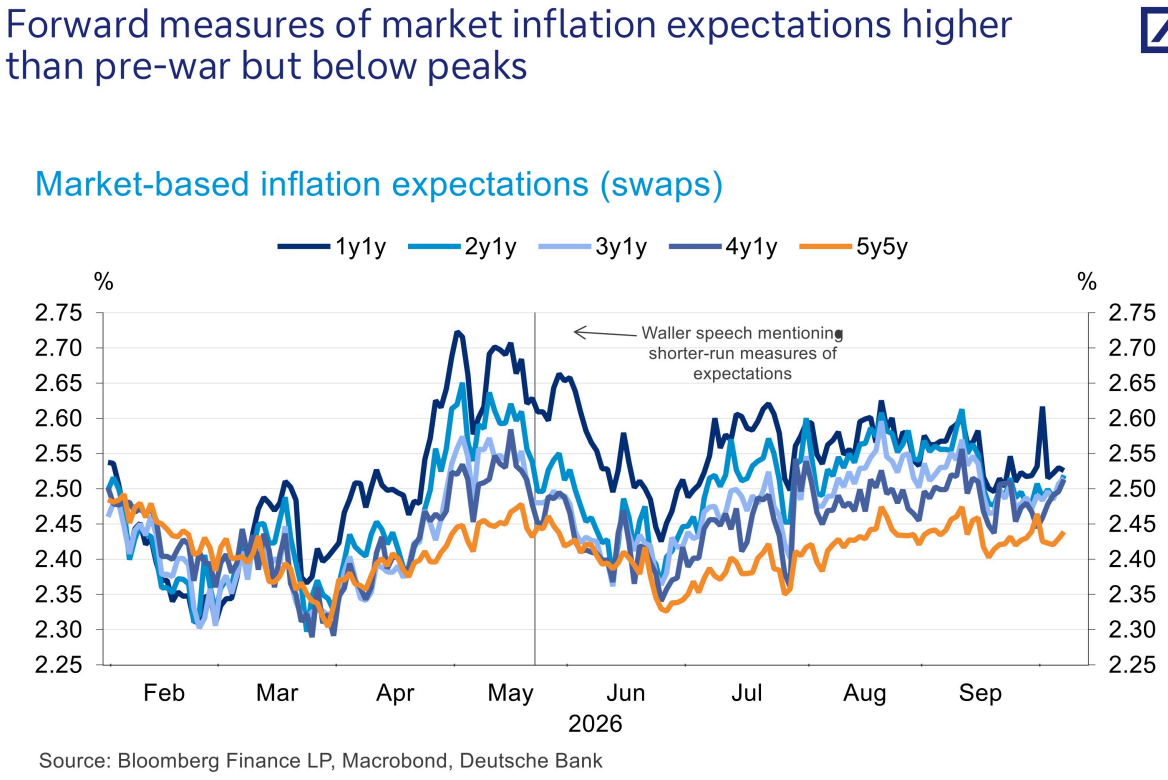
Exhibit 5
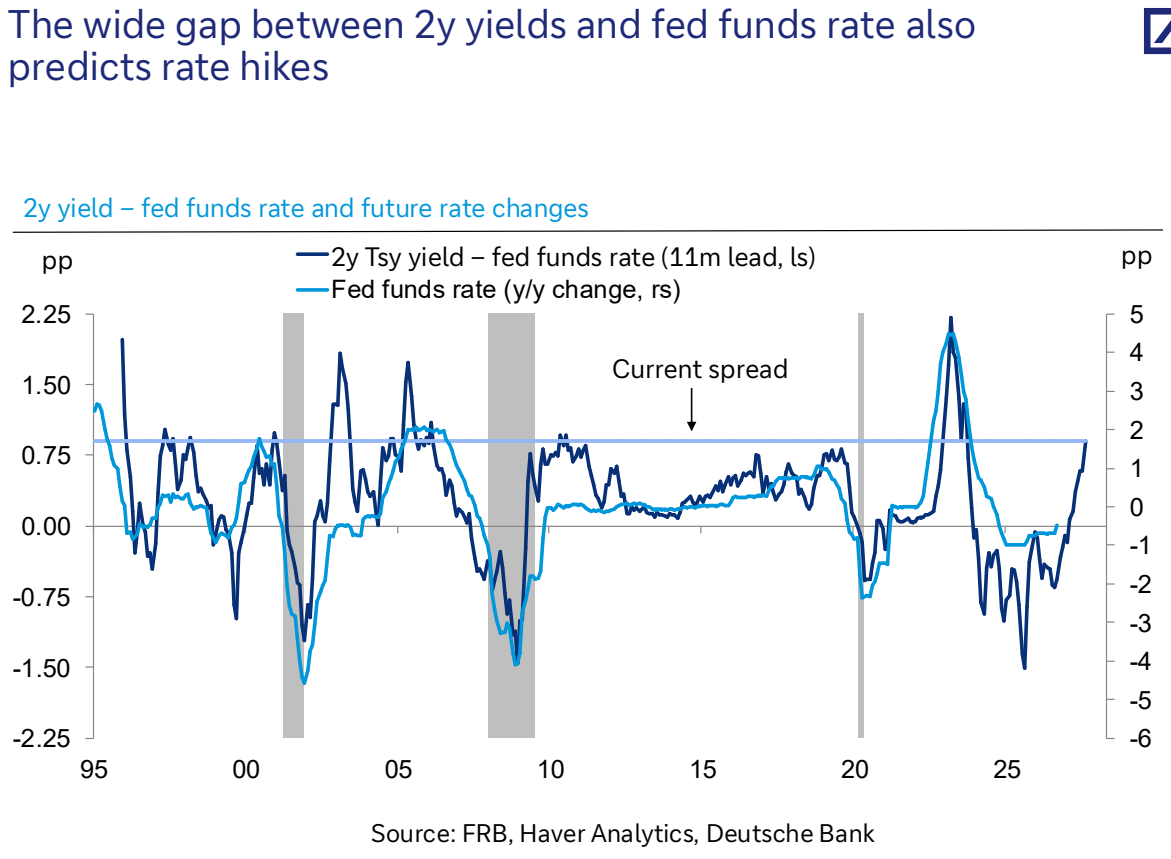
Exhibit 6
Exhibit 7
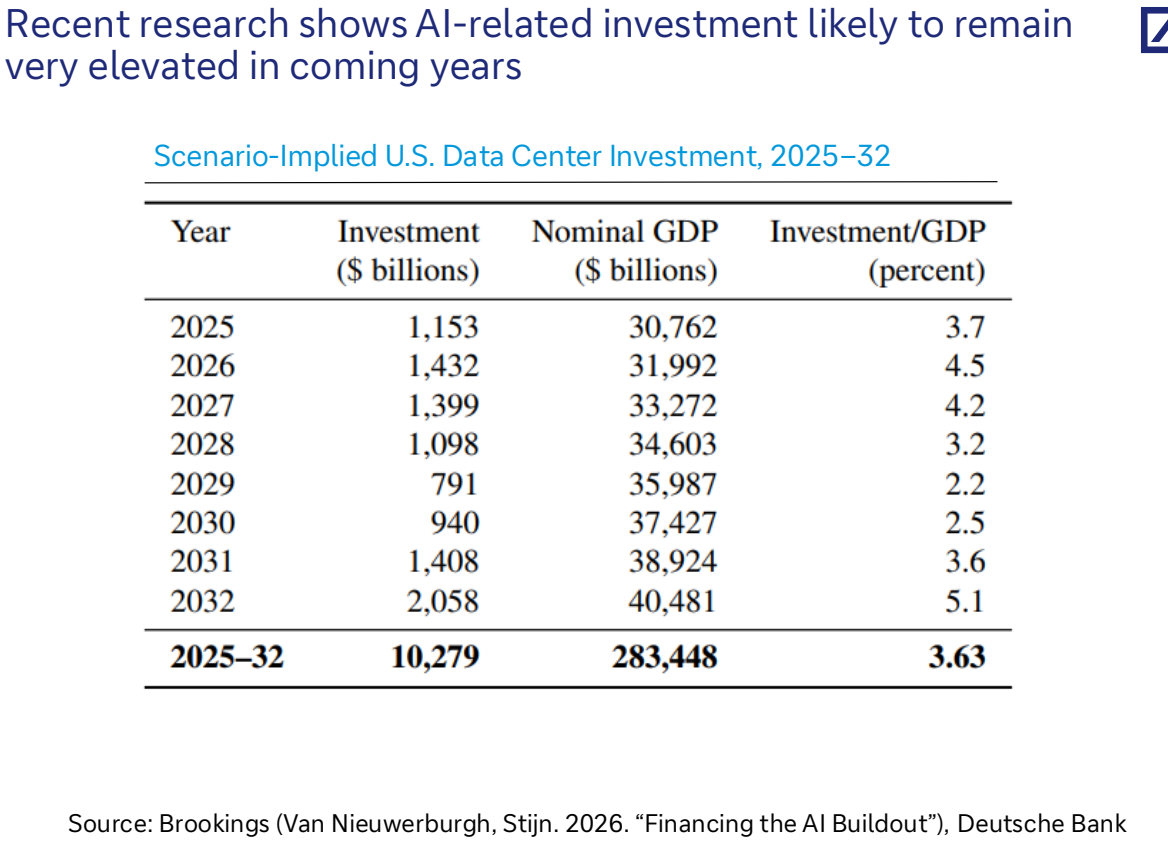
Exhibit 8
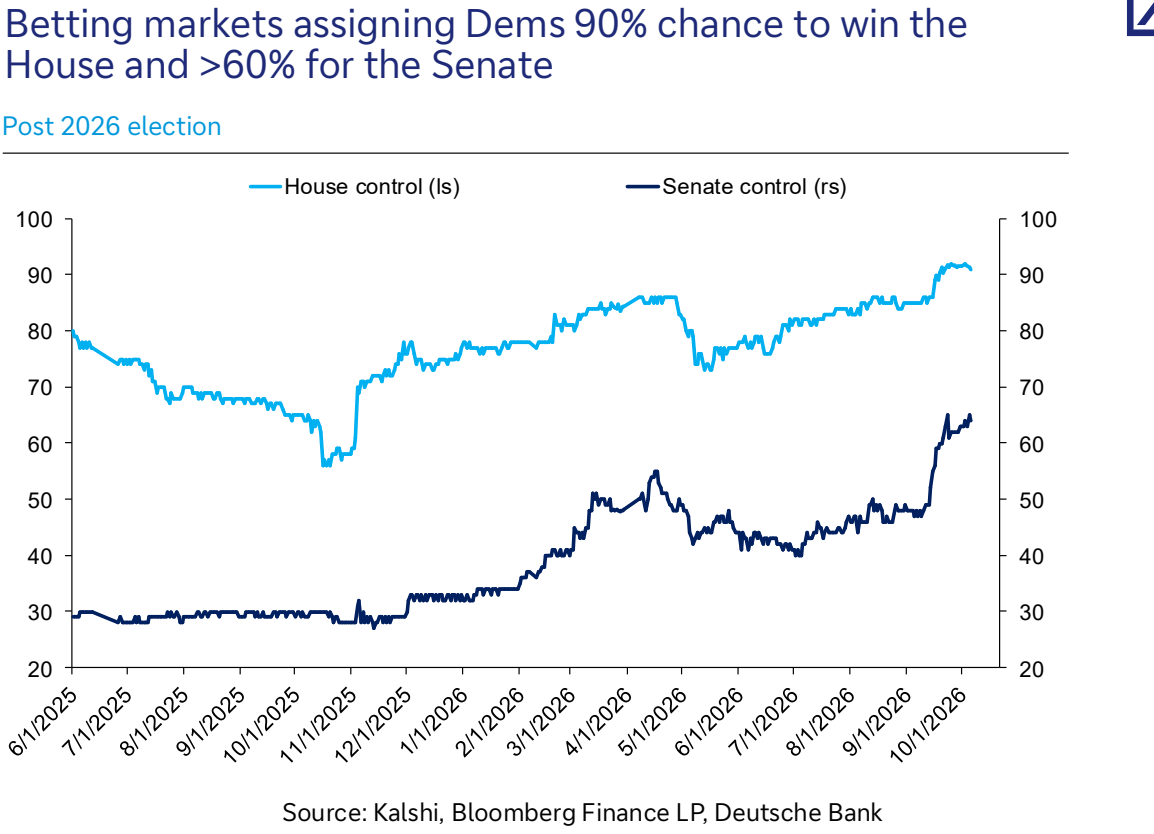
Exhibit 9
Exhibit 10