Goldman Sachs: GCE (2368.TW) 2027–29 Capacity Expansion Signals Solid Long-Term ASIC Demand; Buy, New TP NT$1,585
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs maintains its Buy rating on Giga Computing Electronics (2368.TW) and raises the target price to NT$1,585. The firm observes that the company's planned capacity expansion from 2027 to 2029 reflects robust, long-term demand from its ASIC customers. This expansion is expected to underpin Giga Computing's growth trajectory over the next several years while cementing its competitive positioning within the ASIC market.
Analysts argue that the current equity valuation does not yet fully reflect the long-term value creation potential inherent in this capacity ramp-up. Consequently, Goldman Sachs has adjusted its target price upward to account for these fundamental improvements. The investment thesis is fundamentally anchored on the premise that sustained ASIC customer demand remains the primary growth catalyst for the company. While the specific financial forecasts and granular numerical targets were not detailed in the available summary materials, the strategic emphasis on production scaling highlights management's confidence in future revenue visibility.
However, the institutional report notably did not highlight any immediate short-term catalysts, nor did it explicitly outline specific downside risk factors. The core rationale relies heavily on the structural execution of the 2027–2029 capacity build-out and the enduring strength of underlying artificial intelligence and high-performance computing end-markets driving ASIC adoption.
Key exhibits
Exhibit 1
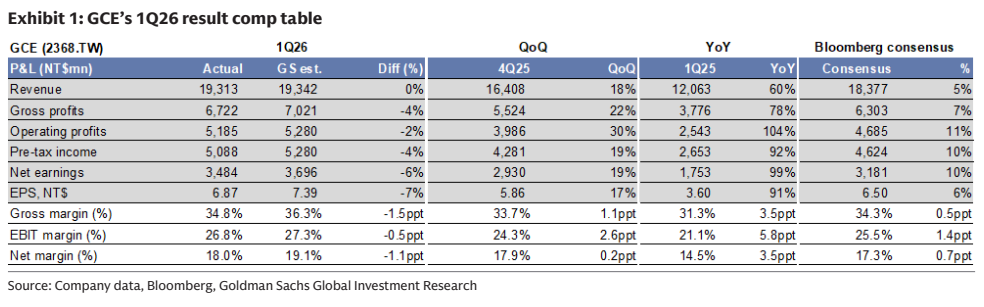
Exhibit 2
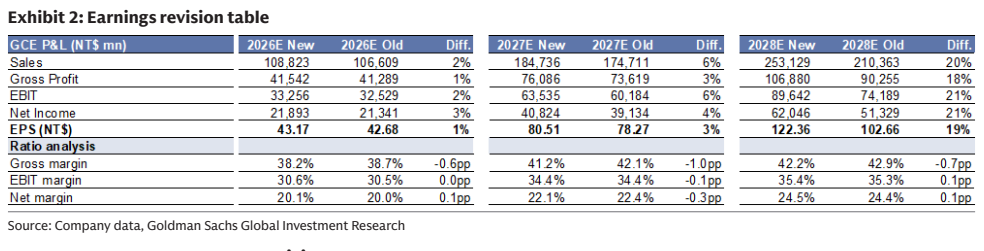
Exhibit 3
