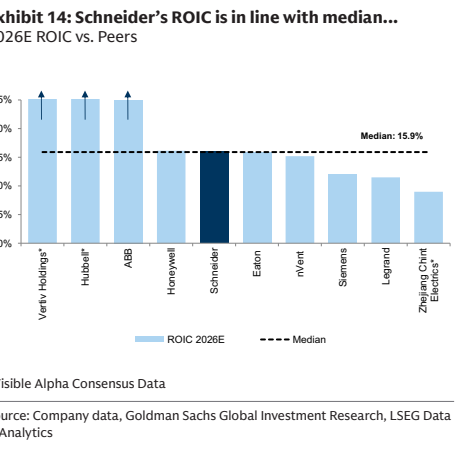
Goldman Sachs: Schneider Electric (SCHN.PA) — Post 1Q26 Update; Reiterate Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs reiterates a Buy rating on Schneider Electric following a solid first-quarter 2026 update, asserting that the long-term secular trends of electrification and digitalization remain robust. The bank highlights that Schneider delivered 8% organic revenue growth, aligning with market expectations. Furthermore, the adjusted EBITA margin reached 17.5%, slightly exceeding consensus estimates of 17.2%.
Management has maintained its full-year 2026 guidance, projecting organic revenue growth between 6% and 8% and an adjusted EBITA margin ranging from 17.5% to 18.0%. The bank notes that order momentum remains exceptionally strong, with first-quarter orders growing 12% year-over-year. This growth is primarily fueled by insatiable data center and infrastructure requirements, which now account for approximately 30% of total revenue and effectively offset lingering weakness in the building and residential sectors.
Schneider continues to demonstrate excellent cash generation, producing 1.2 billion euros in free cash flow during the quarter, a 15% year-over-year increase. Goldman Sachs argues that prevailing macroeconomic concerns have excessively compressed the stock’s valuation. Currently, shares trade at roughly 22 times 2026 estimated earnings, a notable discount to the historical average of 25 times. The bank maintains a 12-month target price of 280 euros, implying meaningful valuation upside as structural growth drivers persist.
Key exhibits
Exhibit 1
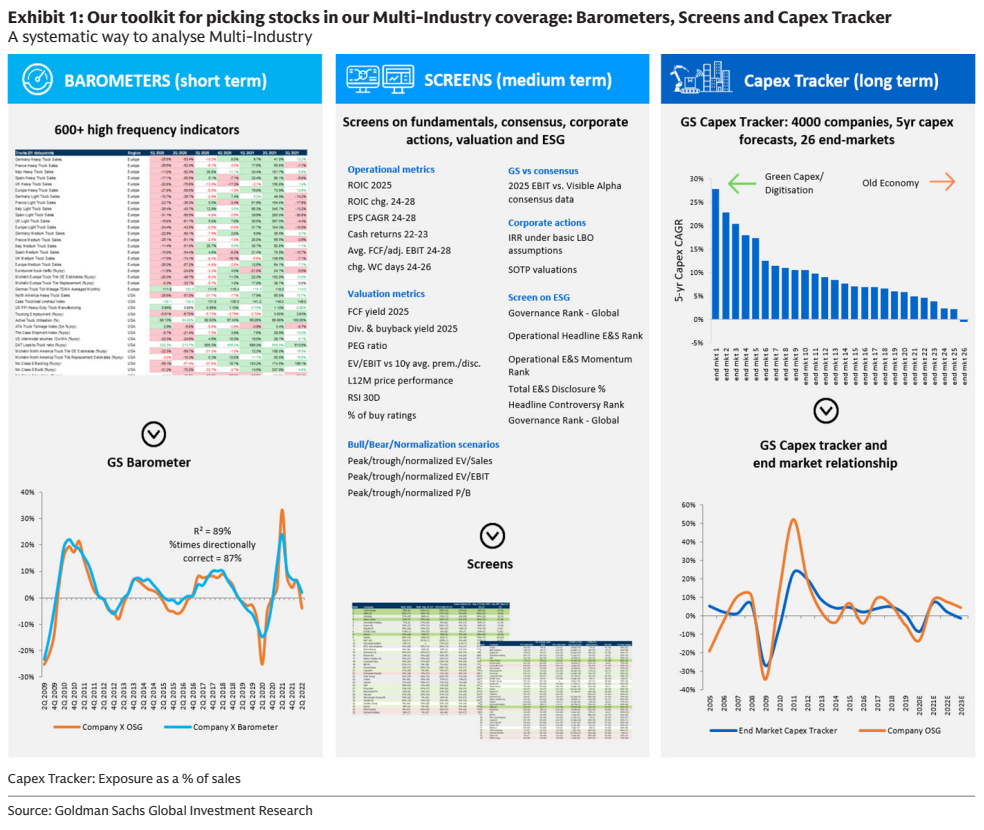
Exhibit 2
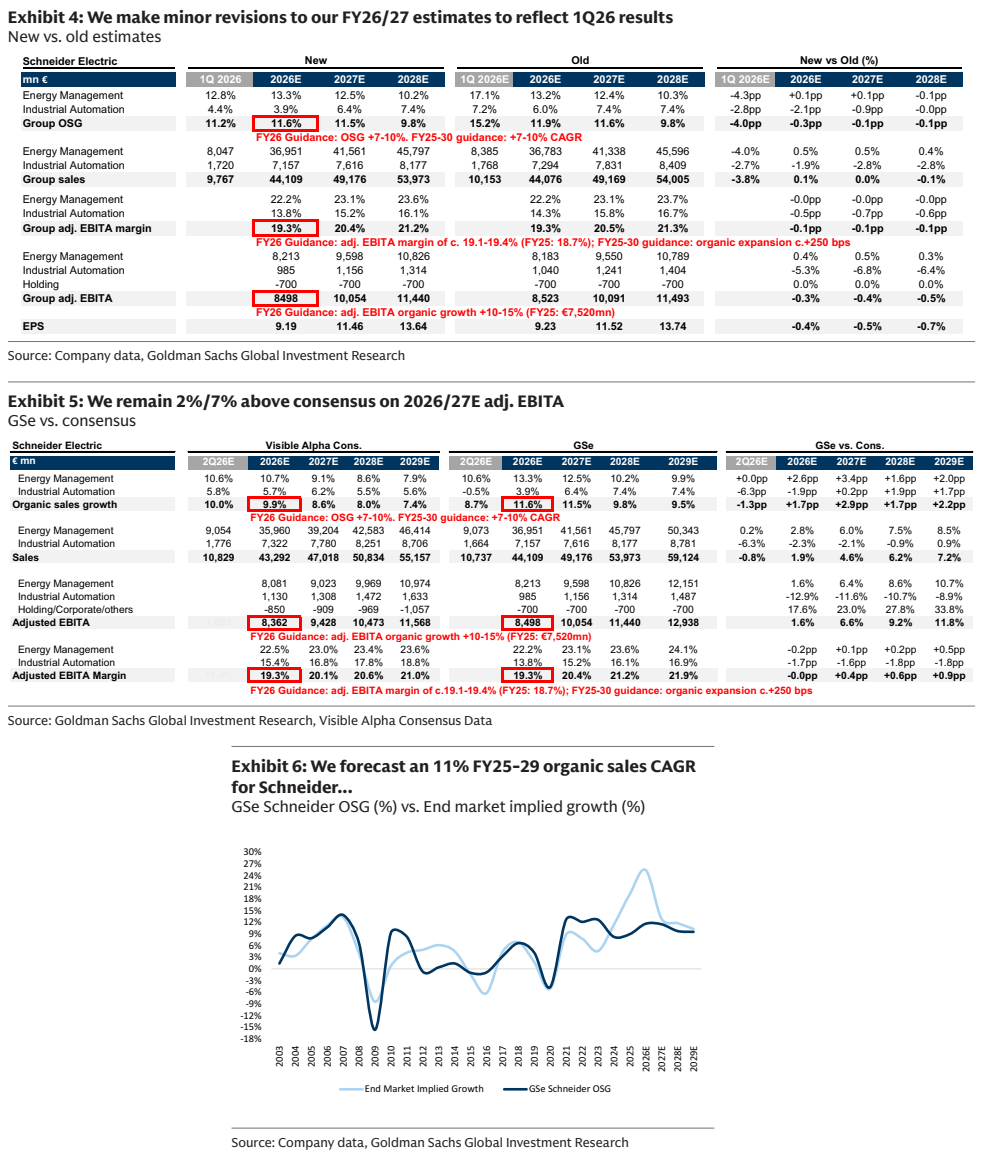
Exhibit 3
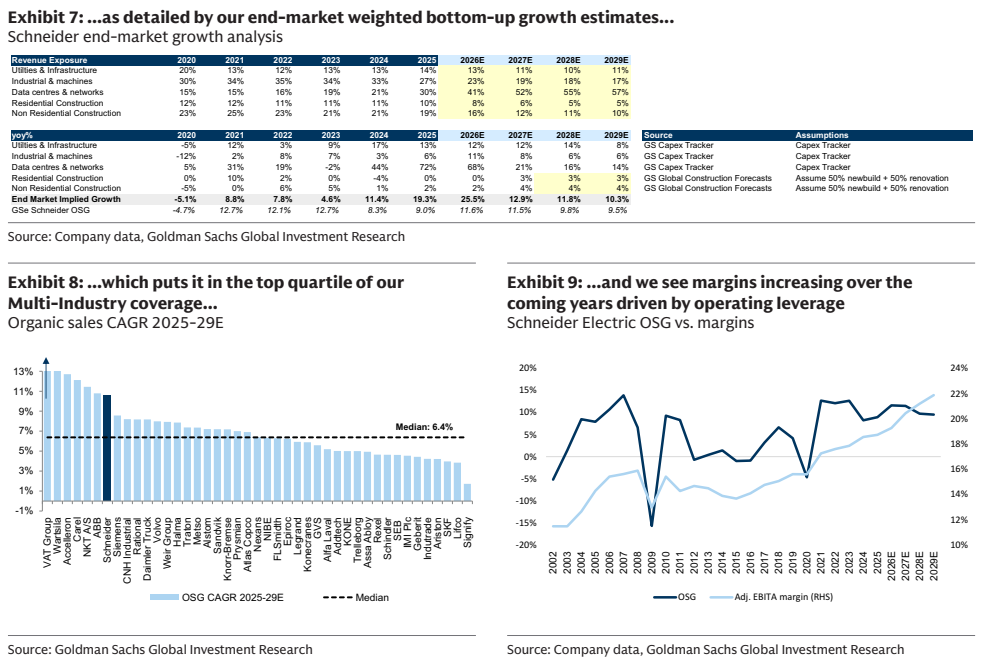
Exhibit 4
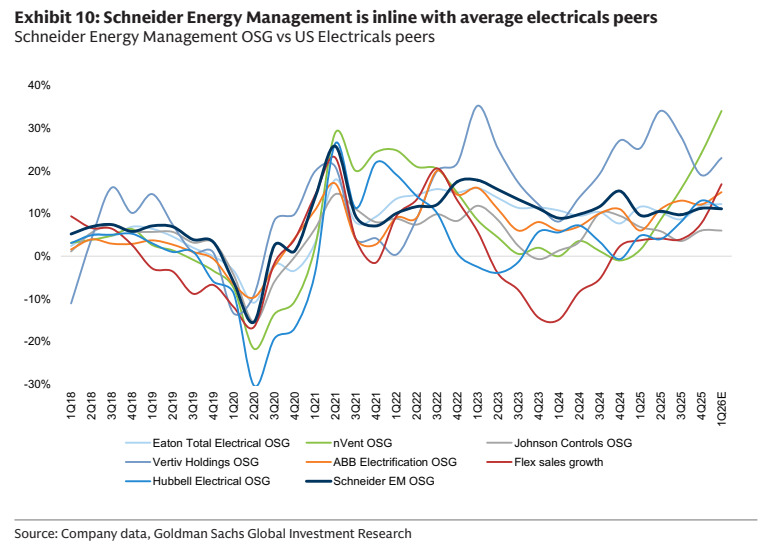
Exhibit 5
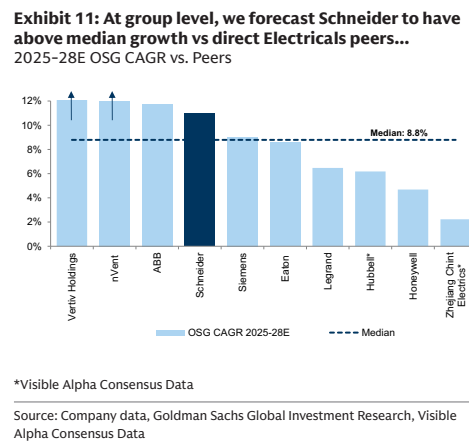
Exhibit 6
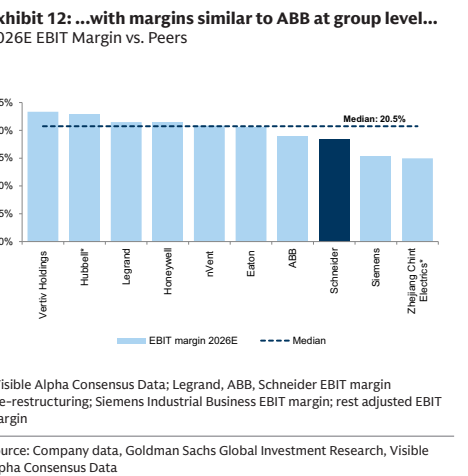
Exhibit 7

Exhibit 8